Sign in to fuzzto save your conversations, follow your research and come back anytime.

Wipro Limited is a global technology services and consulting company headquartered in Bangalore, India. It operates primarily through two business segments: IT Services and IT Products. The IT Services segment provides a wide range of services including digital strategy, technology consulting, custom application development, systems integration, cloud services, analytics, artificial intelligence, and business process services. The IT Products segment offers third-party IT products. Wipro serves clients across various industries globally, with a focus on sectors like banking, financial services, retail, consumer goods, healthcare, manufacturing, and telecommunications. The company has made several strategic acquisitions and partnerships over the years to expand its capabilities and global presence. Wipro is known for its digital transformation services and has been recognized for its ethical business practices.
In the news
IT's AI Race: TCS, HCLTech, Tech Mahindra, and Wipro's Q2 Showdown
Wipro Confirms 7,500 Freshers Hiring Target Despite Q2 Slowdown
Wipro shares surge 6% amid weak Q3 guidance, deal conversion concerns
Wipro Q2 results: Net profit drops 1.9% YoY, shares surge 6.5%
Q2FY27 Results Today: Jio Fin, Yes Bank, Wipro Lead Earnings
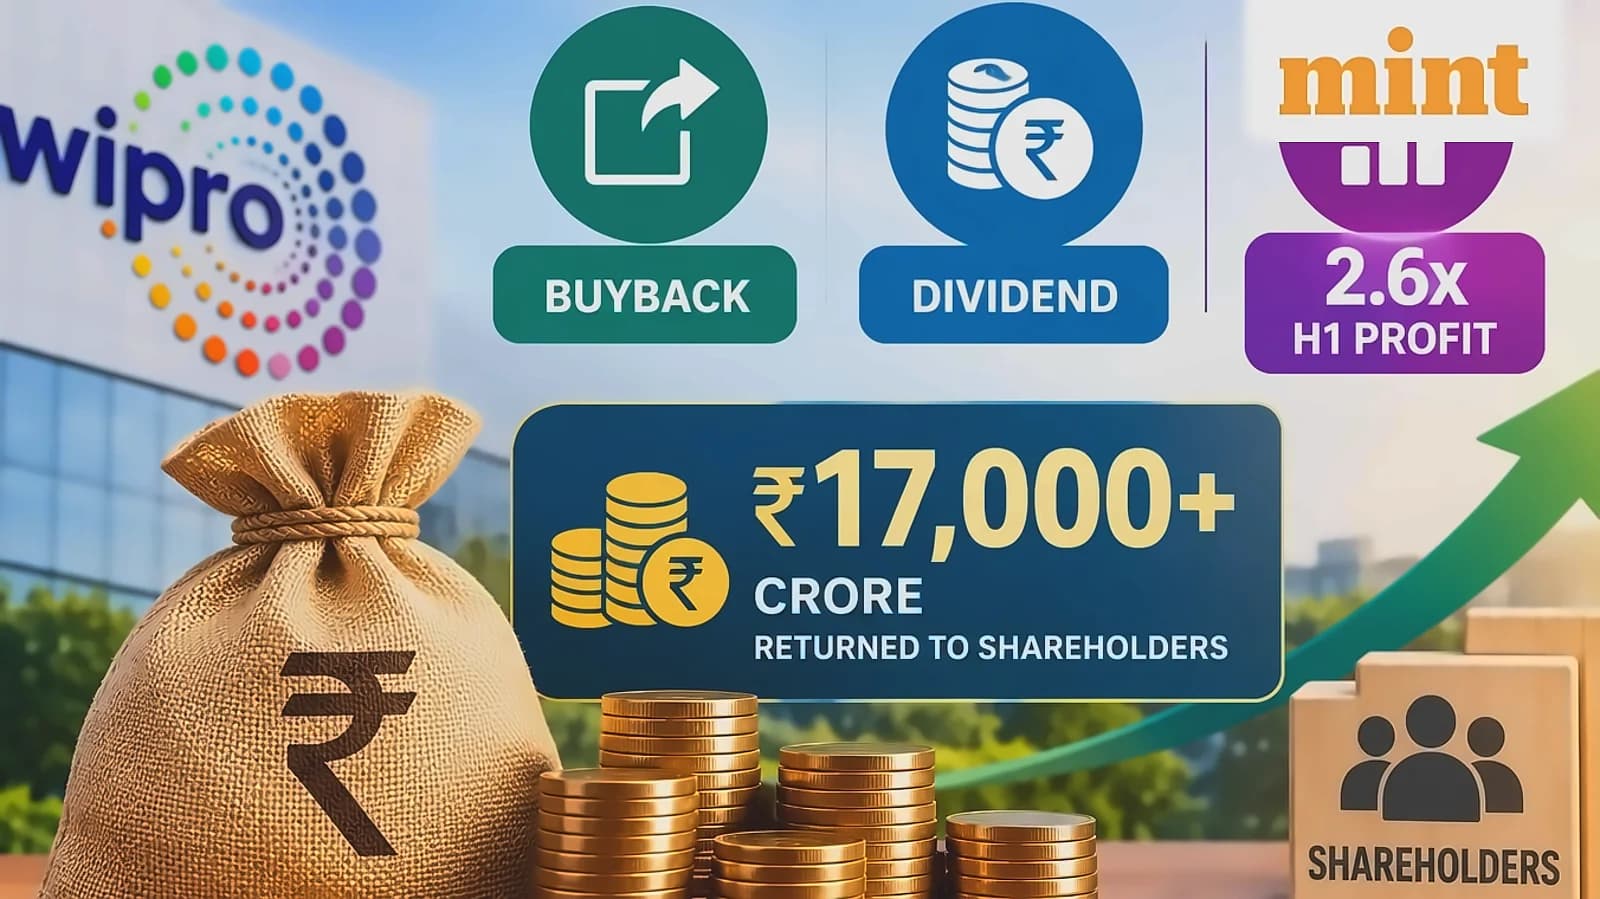
Wipro Returns ₹17,029 Cr to Shareholders in H1 FY27
Wipro's Q2 FY27: Revenue Growth vs Flat IT Services
Wipro, Persistent Systems lead stocks to watch Oct 16
Wipro Q2 Results: Net Profit Falls 4.5% to ₹3,200 Cr, ICICI Securities Cuts Rating
SEBI fines Supriya Kothari ₹10 lakh for Wipro probe non-cooperation
Indian IT Giants Prepared for US PERM Suspension Impact
PERM Freeze: What the Green Card Suspension Means for Tech

Wipro Q2 Results: Oct 15 Declaration, AI Initiatives
Wipro extends bench period to 180 days for junior staff
Tech Mahindra's Bonus Bet: What the Diwali Surprise Means for Shareholders
Wipro leads with 14 bonus issues, L&T follows with 10
NSE Index Rebalancing: Winners, Losers, and the $1.2 Billion Shuffling Game
Wipro ADR at $1.67 support amid 5+ year trainee delays
Oracle Debt, Visa Fees, and AI Deflation: Indian IT's Perfect Storm
Wipro Launches STO360 Solution with Aramco and SAP; Shares Fall 38% YTD
The Quarter story
The two most recent quarterly results, compared side-by-side.
Wipro shows strong talent retention and deal momentum, but margin pressure and regional shifts require close monitoring.
Voluntary attrition fell from 15.1% to 13.9% from Q1 FY26 to Q1 FY27 — better talent retention supports delivery stability
Operating margin slipped from 17.3% to 16.0% from Q1 FY26 to Q1 FY27 — pricing pressure and cost scaling squeeze profitability
Large deal bookings grew from 2.7 to 1,626 in USD from Q1 FY26 to Q1 FY27 — strong pipeline conversion fuels future revenue
Americas 2 revenue share fell from 30.4% to 25.4% from Q1 FY26 to Q1 FY27 — weakening demand in key Western markets
APMEA revenue mix expanded from 10.8% to 12.2% from Q1 FY26 to Q1 FY27 — regional diversification reduces currency risk
Cost of revenues rose from ₹157,247 Cr to ₹171,914 Cr from Q1 FY26 to Q4 FY26 — expanding headcount and project scale drive higher expenses
Tech & Comms sector share increased from 15.5% to 17.0% from Q1 FY26 to Q1 FY27 — growing demand in high-margin digital services
EMR sector share declined from 17.7% to 16.1% from Q1 FY26 to Q1 FY27 — slower enterprise modernization spending impacts growth
Top 10 customer concentration dropped from 24.5% to 23.7% from Q1 FY26 to Q3 FY26 — broader client base lowers dependency risk
Cash conversion ratio dropped from 123.2% to 98.0% from Q1 FY26 to Q1 FY27 — working capital management needs attention
Company insights, generated from the most recent coverage.
Wipro rallied ~6% on management commentary about BFSI and AI-led pipeline despite flat revenue, falling profit and bookings down 22.9% QoQ. The move is relief plus narrative, not a fundamental upgrade.
Wipro's 12.9x P/E and 1.96x P/B are the lowest of the four majors and are consistent with the weakest fundamentals — cheapness here is a signal of broken growth, not mispricing.
Wipro's utilisation fell to 83.4% from 86.4% a year earlier even after cutting 6,716 heads. Shrinking the workforce failed to lift utilisation, which points to weak demand conversion rather than over-hiring as the core problem.