Sign in to fuzzto save your conversations, follow your research and come back anytime.

In the news
Puravankara Q2 pre-sales surge 62% to ₹2,136 crore on housing demand
Puravankara shares jump 1.3% on ₹2,500 cr Bengaluru land deal
NCR Expansion: How Puravankara and Oberoi Are Reshaping Real Estate Geography
Puravankara shares surge 4% on ₹5,200 cr Delhi-NCR land acquisition
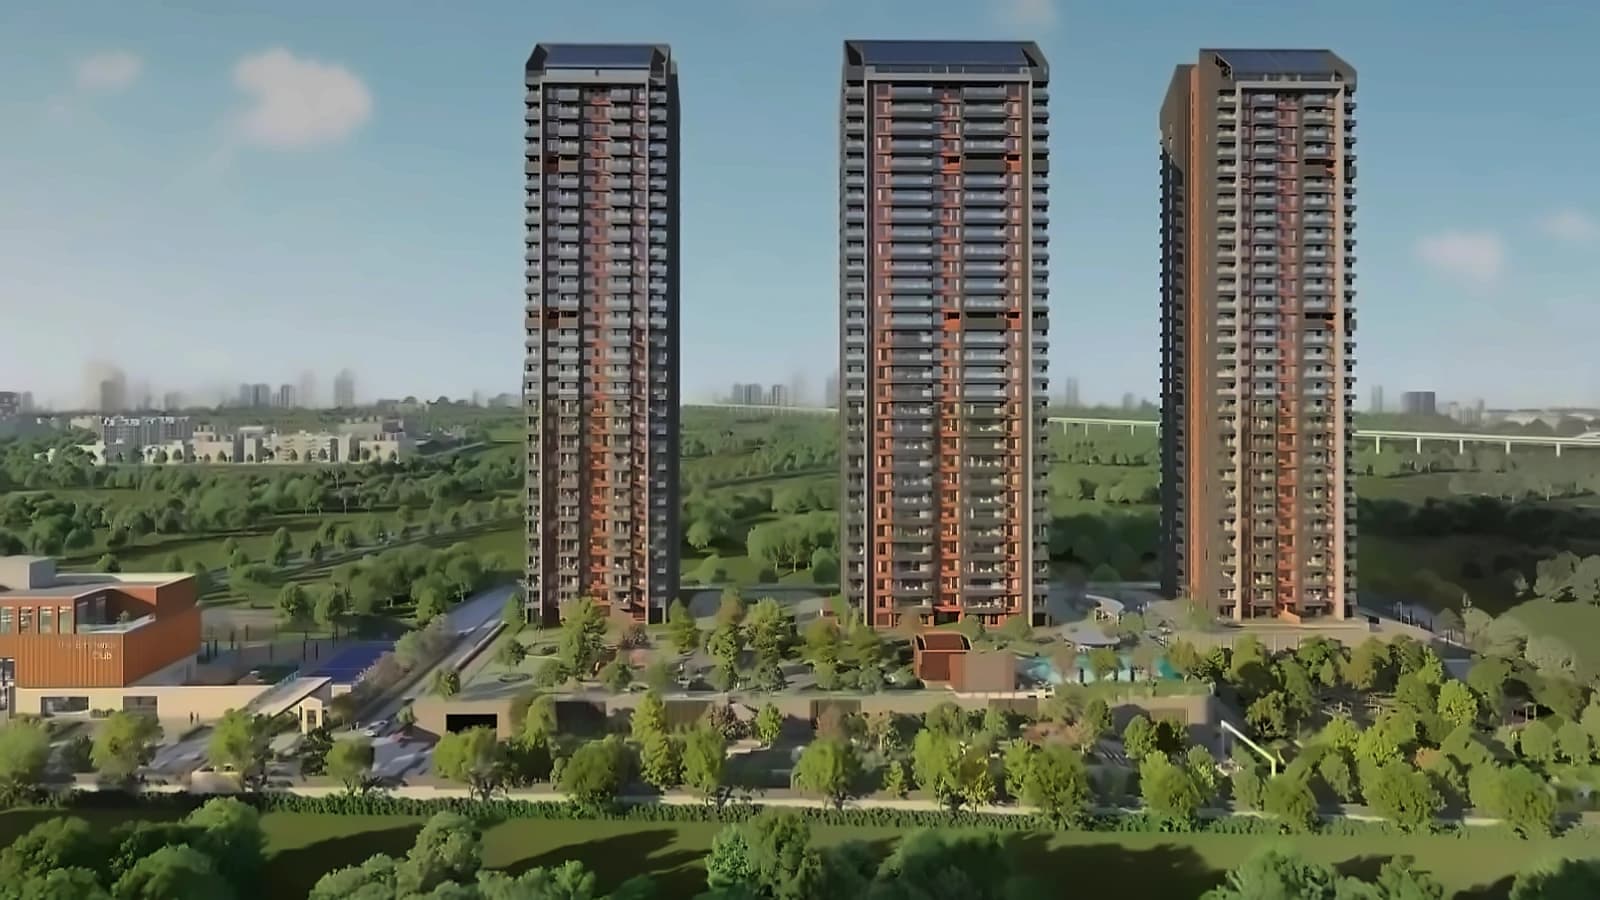
Provident Housing launches PROVIDENT EQUINOX 6 project in Bengaluru
Puravankara shares jump 4% on ₹2,600 cr Mumbai redevelopment project
Puravankara shares surge 12% on strong FY26 results
Puravankara shares rise on ₹175 cr Ritz-Carlton order, ₹1,100 cr Bengaluru JDA
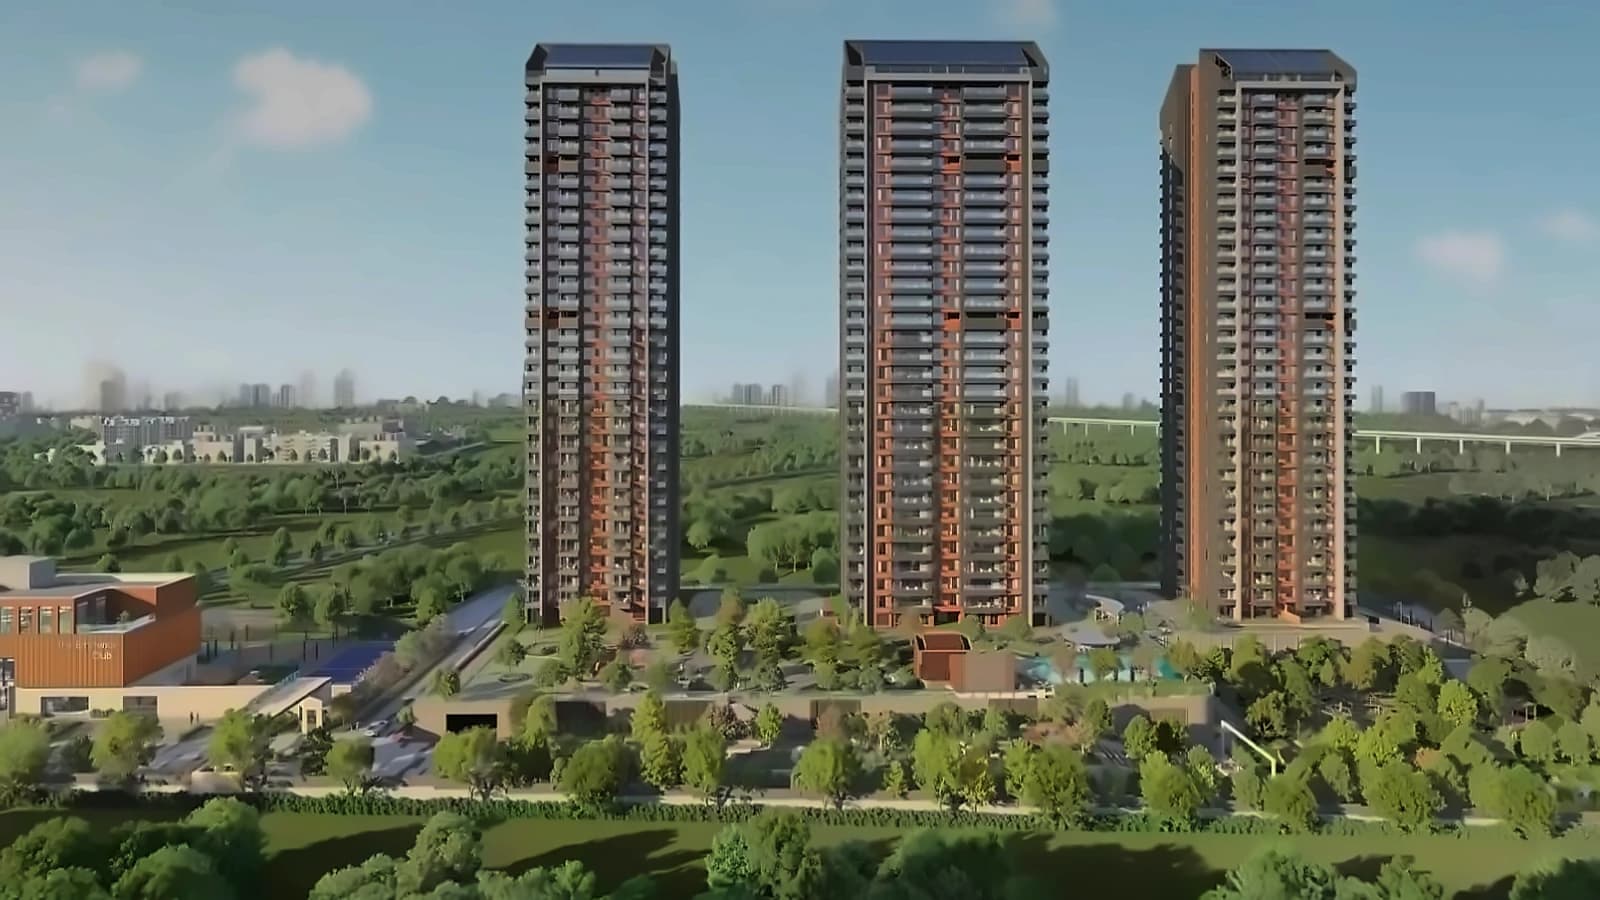
Puravankara shares surge 10.76% on Q1 profit turnaround, 63% revenue jump

Puravankara soars 17% on Q1 pre-sales rise 28% YoY to ₹1,439 cr

Puravankara shares gain 2.64% on ₹1,000 cr Sarjapur JDA deal

Puravankara shares rise 2.10% on 9.73-acre Bengaluru land deal
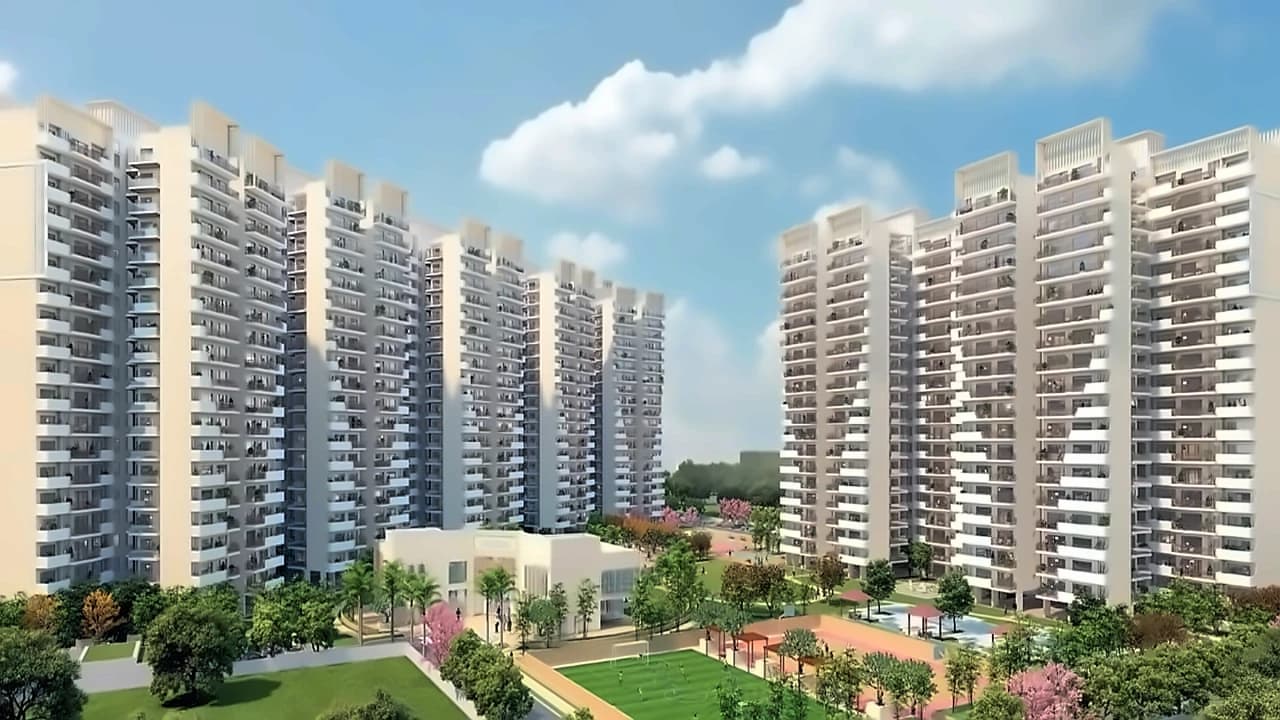
Puravankara forms JV for ₹1,100 cr Bengaluru housing project

Puravankara acquires 14.57-acre land in Bengaluru for ₹2,300 cr project
Puravankara acquires 14.57-acre land parcel in Mandur, Bengaluru
Puravankara plans ₹2,000 cr investment in FY27 amid stable demand

Puravankara secures 14.57 acre land in Bengaluru for ₹2,300 cr

Puravankara secures ₹2,300 cr land parcel in Bengaluru
US Justice Dept Drops Adani Charges, Boosts Borrowing Profile
Puravankara Q4FY26: Net profit at ₹110 cr, revenue doubles
The Quarter story
The two most recent quarterly results, compared side-by-side.
Puravankara delivers strong profitability and cash collection growth, though rising debt and a shrinking developable pipeline require monitoring.
EBITDA margin expands from 15% to 25% from Q1 FY26 to Q1 FY27 — stronger pricing power drives profitability
Gross debt increases from ₹3,543 Cr to ₹3,942 Cr from Q1 FY26 to Q1 FY27 — higher financing needed for land and project development
Collections grow from ₹857 Cr to ₹1,199 Cr from Q1 FY26 to Q1 FY27 — steady cash flow supports ongoing construction
Net debt rises from ₹2,825 Cr to ₹2,836 Cr from Q1 FY26 to Q1 FY27 — new borrowings outpace cash generation in the latest quarter
Average realization rises from ₹8,988/sq ft to ₹10,589/sq ft from Q1 FY26 to Q1 FY27 — premium product mix commands higher prices
Developable area contracts from 24.44 msft to 13.95 msft from Q1 FY26 to Q1 FY27 — pipeline shrinks as projects complete and hand over
Net profit turns positive from a loss of ₹68.55 Cr to ₹25 Cr from Q1 FY26 to Q1 FY27 — clear return to profitability after early-year losses
Cost of debt ticks up from 11.05% to 11.12% from Q4 FY26 to Q1 FY27 — slight pressure on interest expenses
Group's economic interest grows from 59.30 msft to 63.98 msft from Q1 FY26 to Q1 FY27 — larger stake in future development value
Company insights, generated from the most recent coverage.
Puravankara's Greater Noida bet is a volume play into a supply-constrained, end-user market — 7.7 quarters-to-sell versus Gurugram's 9.6. Faster absorption matters more than headline price for a levered developer funding a ₹5,200 Cr GDV.
Entering NCR in 2026 rather than a prior cycle cuts the two risks that killed South Indian entrants before: fund diversion and speculative demand reversal. RERA plus end-user-led absorption makes the downside narrower, even if the upside is now partly priced in.
Peer launches in Greater Noida have booked roughly ₹1,500 Cr each, so Puravankara needs only about 3-4 comparable launches to recover its GDV. That is the concrete absorption benchmark underpinning the investment case.