For many approaching retirement, Social Security represents an important source of future income that requires careful strategic planning. According to recent guidance, deciding when to claim benefits is not as simple as choosing a retirement date, as your age, employment plans, other retirement income, marital status, health and broader financial picture can all influence your decision. Retiring from your career does not necessarily mean you need to begin Social Security immediately. You can generally begin receiving retirement benefits as early as age 62, but claiming before your full retirement age will result in a permanently reduced monthly benefit. Full retirement age varies based on your year of birth, while waiting beyond full retirement age can increase your monthly benefit through delayed retirement credits until age 70.
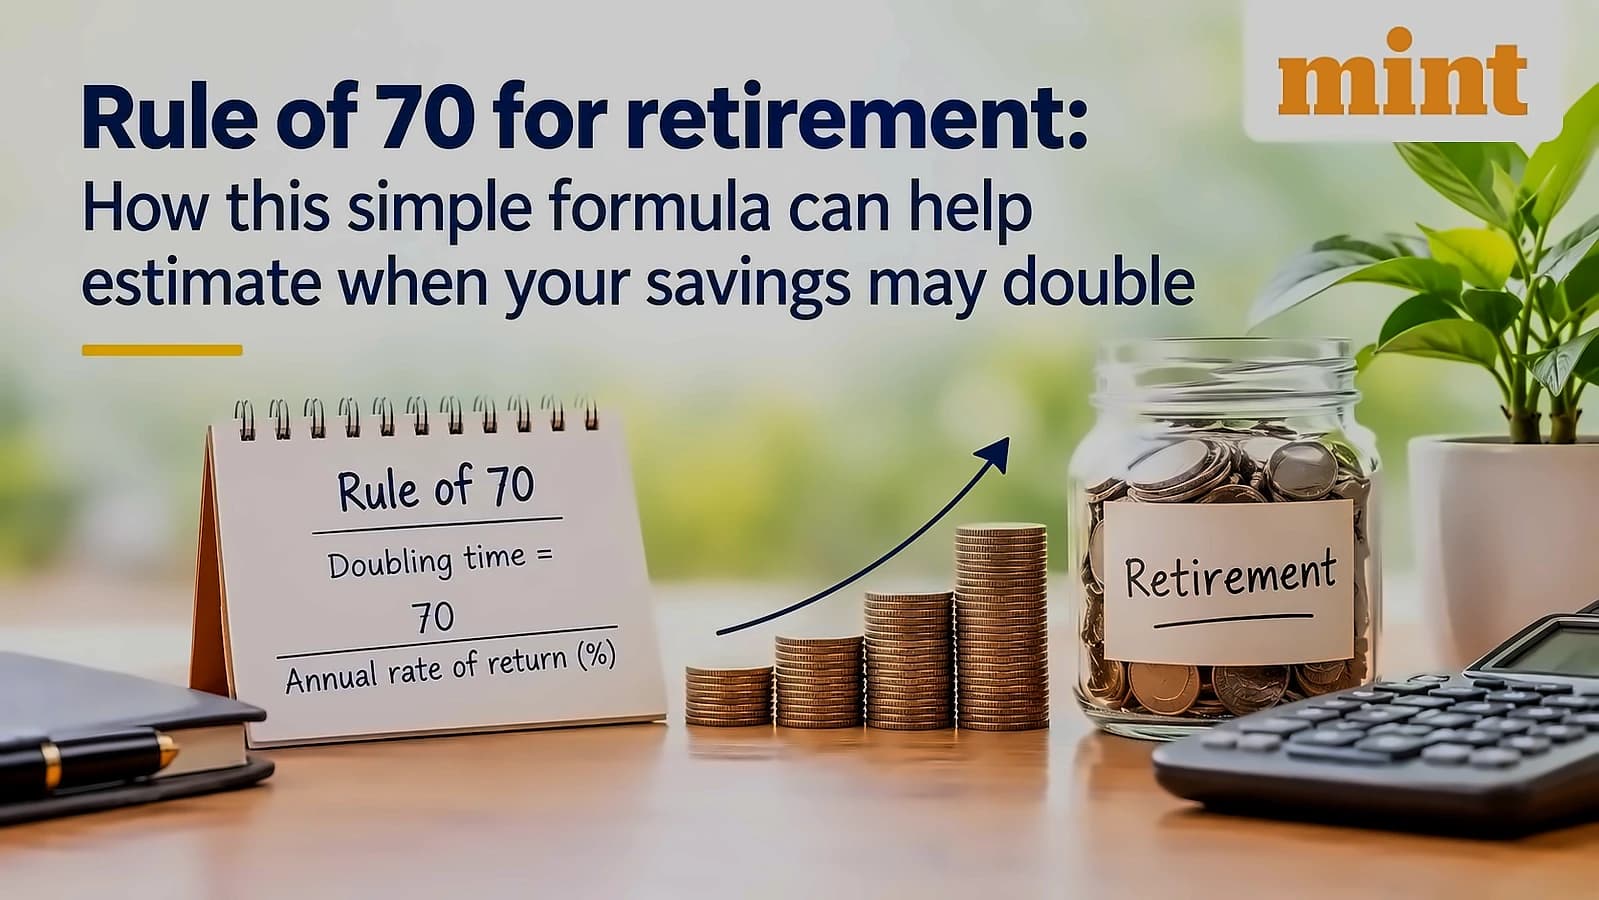
The 'Rule of 70' is a retirement-planning formula that estimates how long an investment may take to double, helping investors gauge corpus growth and make informed decisions about savings, returns and retirement goals. According to reports from Mint, this simple calculation can provide a quick way to understand the potential growth of retirement investments and determine how early one needs to start investing. The formula assumes a constant annual rate of return to ensure clear calculations, with several alternatives available including the 'Rule of 72' and the 'Rule of 69' for constructive retirement planning.
The formula for doubling time is Doubling time = 70/annual rate of return (%). As reported by Mint, for example, if an investment earns about 7% annually, dividing 70 by 7 gives 10 years. This means that an investment can approximately double in 10 years, from ₹1 lakh to ₹2 lakh, if the annual return remains at 7%. Similarly, if an investment earns about 15% annually, dividing 70 by 15 gives 4.6 years, meaning the investment can double in about 4.66 years. The table below shows the doubling time for various return rates:
According to recent retirement planning guidelines, 70% of your annual pre-retirement income is considered a basic requirement to live comfortably in retirement. However, this may not be sufficient for those planning major expenses such as building a dream house, extensive travel, or pursuing advanced education like a Ph.D. For such aspirations, retirees may need 100% of their current income or more to achieve their desired lifestyle. This rule of thumb provides a starting point for retirement planning, though actual requirements can vary significantly based on individual circumstances and financial goals.
As reported by Mint, the 'Rule of 70' should be treated as an initial starting point for planning constructive retirement strategies. It should not be taken as a standalone strategy, as a comprehensive retirement plan should consider income, expenses, expected inflation, investment returns and desired post-retirement lifestyle. The rule helps aspiring investors compare different return assumptions, asset classes and understand the impact of starting early, making it a valuable tool for retirement planning decisions. Additionally, successful retirement planning requires skillful investment approaches and utilization of tax-advantaged savings plans such as 401(k)s and IRAs. For those approaching retirement, understanding Social Security options before claiming benefits can provide more time to evaluate how these income sources fit into overall financial strategies, with the appropriate approach depending on individual circumstances and should be considered with financial advisors and tax professionals.