A family safety net is not measured by what it holds, but by what someone else can do with it. According to financial experts, most households have more protection than they realize but less access than they assume. The gap between protection and access is where families get hurt most. A personal financial plan focuses on accumulation, while a safety net emphasizes redundancy and access for other people. The key question is not whether you can access your money, but whether someone else can reach it when you're unavailable. Most families fail this test because one person holds the logins, knows the accounts, and understands the plan, creating a concentration of knowledge that becomes a vulnerability.
The Rule of 100 provides a basic guideline for determining equity allocation based on age. According to reports from Mint, the formula suggests subtracting your age from 100 to estimate the percentage held in shares. At age 35, the formula indicates 65% in equity investments, with the remaining 35% typically allocated to bonds or defensive assets. However, this rule has limitations as age cannot explain complete financial situations, and two people aged 35 may have different debts, goals, and tolerance for losses. The rule should be used as a starting point for thinking about allocation rather than treating the answer as final.
The Rule of 72 estimates how long an investment might take to double by dividing 72 by the annual percentage return. As reported by Mint, at a steady 8% annual return, the estimate is approximately 9 years, meaning an investment of ₹1 lakh would become roughly ₹2 lakh. This calculation assumes compounded growth with earnings remaining invested throughout the period. However, the rule does not account for taxes, charges, or inflation, and market investments deliver changing returns that can differ considerably from projections.
The 50/30/20 rule provides a simple structure for monthly income allocation, with 50% towards needs, 30% for wants, and 20% for savings and debt repayment. According to Mint, for a ₹50,000 monthly income, these amounts translate to ₹25,000 for needs, ₹15,000 for wants, and ₹10,000 for savings. The rule helps make room for future priorities before optional spending expands, though expensive housing or family responsibilities may require different proportions. Treat these percentages as starting points that can be adjusted based on household circumstances.
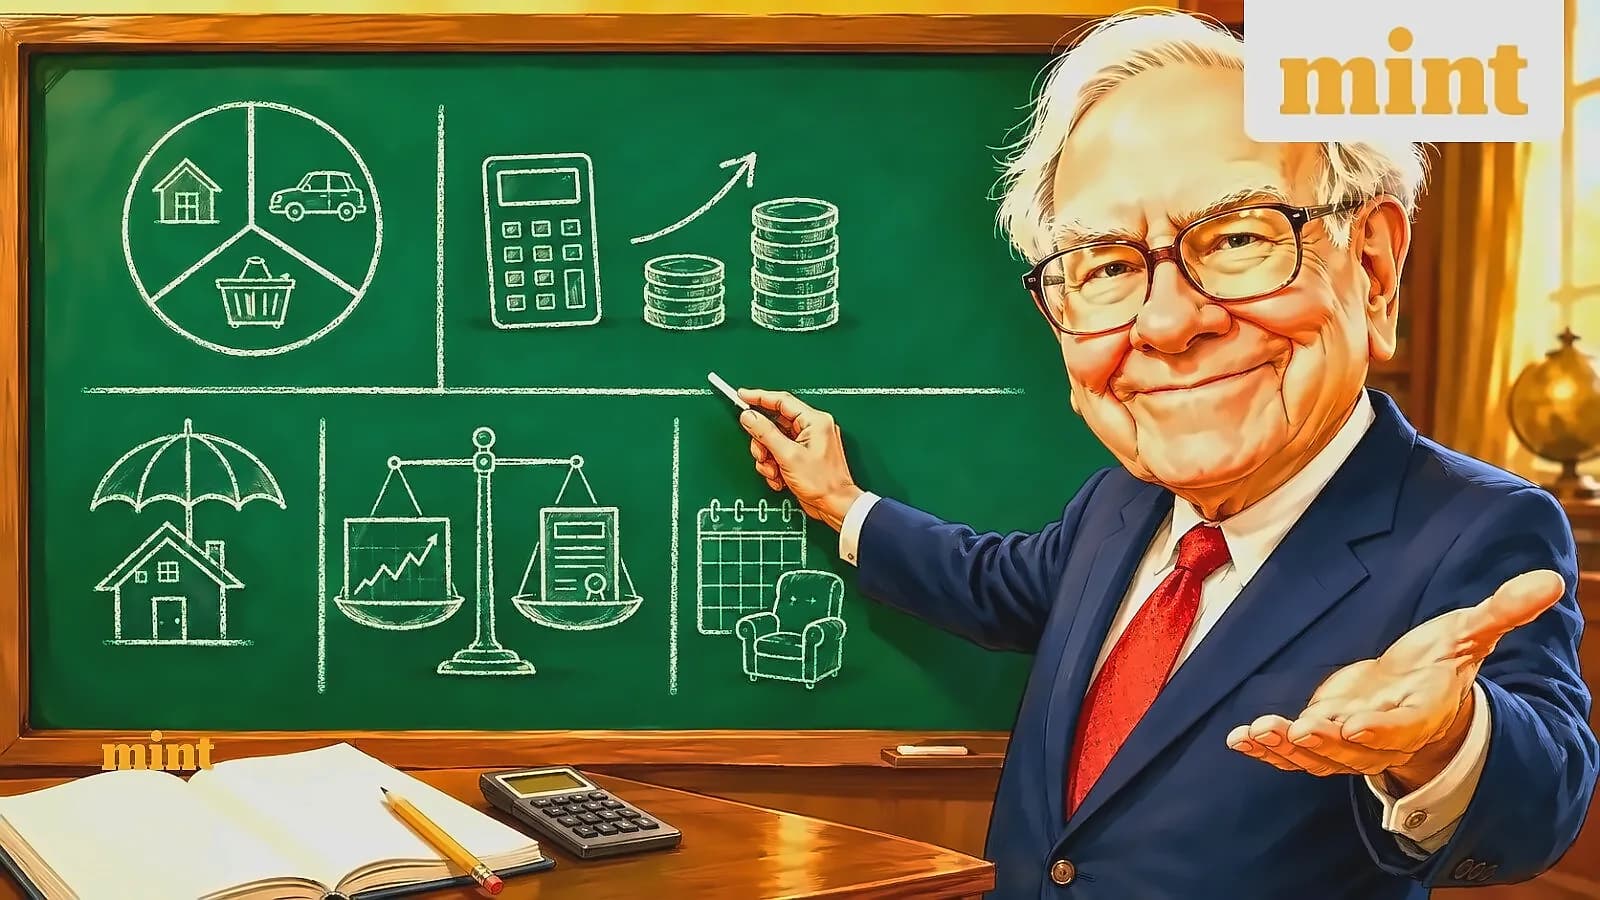
The '6 Months' rule suggests maintaining enough money for six months of essential expenses to help during unemployment, urgent repairs, or unexpected family needs. As reported by Mint, if monthly necessities cost ₹30,000, the suggested emergency fund would be ₹1.8 lakh. The rule should be built gradually if setting aside the full amount immediately feels difficult, with money kept accessible and prioritizing safety over higher returns. Six months serves as a guideline, and irregular earners may need more, with targets reviewed whenever household expenses increase.
The 4% rule serves as a starting framework for planning retirement withdrawals, suggesting withdrawing 4% of the initial retirement portfolio during the first year. According to Mint, with ₹1 crore invested, this means an initial withdrawal of ₹4 lakh, with later withdrawals adjusting that original amount for inflation rather than recalculating 4% annually. The approach emerged from historical American investment research covering roughly 30 retirement years but does not guarantee savings will last under different Indian conditions. Taxes, investment costs, inflation, and retirement length can change outcomes, requiring regular withdrawal reviews instead of following this percentage without adjustments.
A fundamental requirement for family safety is ensuring dual access to all financial accounts. Most families have emergency money, but far fewer have emergency money a second person can access without the first. A fund only one person can reach is not a family safety net - it's a personal one. Hold the fund in a jointly operated account and ensure the mandate allows either holder to operate it alone. Create a comprehensive financial index listing every institution, account type, identifying number, and contact information. This document should include every policy with insurer and policy number, where supporting documents are kept, and who to contact at each institution. Update this index annually on a fixed date, alongside nomination checks, to prevent knowledge loss over time.