For investors choosing between bank fixed deposits (FDs) and debt mutual funds, taxation may no longer provide the clear advantage it once did. According to reports from Mint, both are generally taxed at the investor's applicable slab rate, meaning the decision now depends more on how much certainty an investor wants, how quickly the money may be needed and how comfortable they are with fluctuations in value. The two products may both fall within the fixed-income bucket, but they work very differently - an FD offers a predetermined interest rate for a chosen tenure, while a debt fund's returns depend on the bonds in its portfolio, interest-rate movements and credit conditions.
For investors with a one-to-three-year horizon, the choice is less about tax efficiency and more about certainty versus flexibility, as explained by FundsIndia CEO Rishabh Garg. According to the report, if the money is earmarked for a fixed and non-negotiable requirement within this period, the certainty offered by an FD may be more important than the possibility of a slightly higher return. Investors who have some flexibility and are comfortable with fluctuations can consider short-duration or low-duration debt funds for this time frame, which can offer easier partial withdrawals compared with breaking an FD prematurely. For higher tax bracket investors, arbitrage funds are also worth considering, as they are taxed as equity rather than at the slab rate.
The biggest difference between the two products becomes visible when markets move, with Garg identifying three key risks for debt-fund investors. As reported by Mint, interest-rate risk arises because bond prices generally move inversely to market interest rates - when rates rise, bond prices can fall, putting pressure on a debt fund's NAV. Credit risk is another difference, as bonds held by a debt fund can face rating downgrades or defaults, potentially resulting in a loss for investors. An FD, once booked, is not affected by subsequent movements in market interest rates, with the investor continuing to earn the contracted rate for the agreed tenure, though the rate available when the deposit matures may be different.
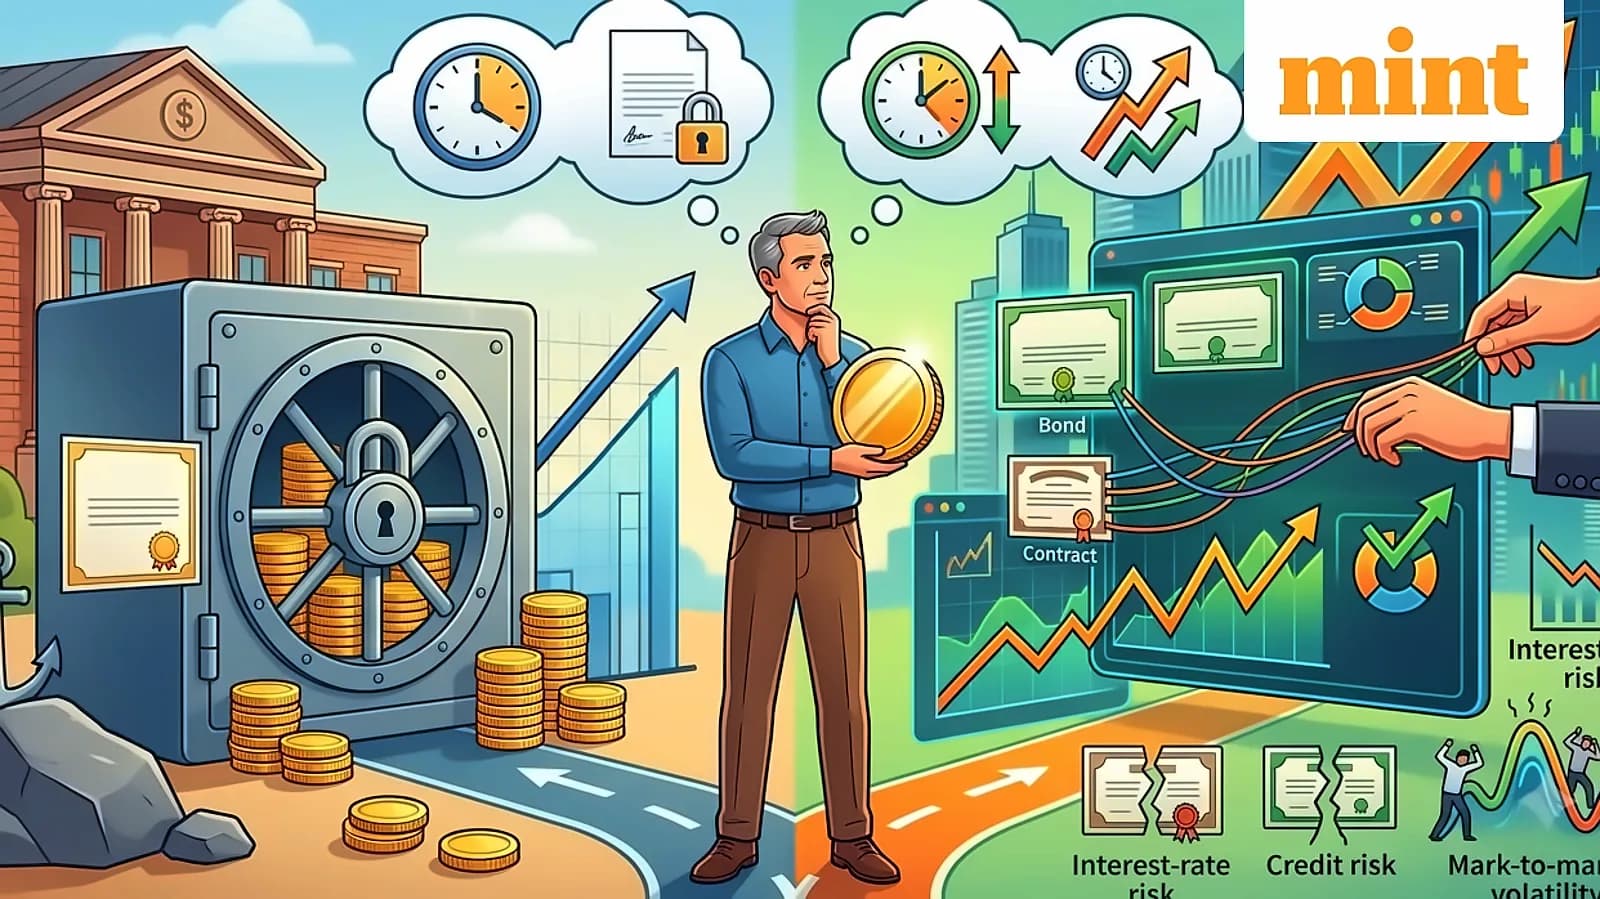
Debt funds can have a role in an emergency corpus, but investors should be selective, according to Garg's recommendations. According to the report, liquid or overnight funds may be considered rather than credit-risk or longer-duration debt funds. Many liquid funds also offer an instant-redemption facility, which can allow eligible investors to access up to ₹50,000 in their bank account within minutes. However, Garg noted that this does not mean liquid funds should completely replace savings accounts, as amounts beyond the instant-redemption limit can take longer to reach the investor, and there is still a small amount of price risk.
The allocation between FDs and debt funds should depend primarily on when the money may be needed and how much fluctuation the investor can tolerate, as outlined by Garg. According to the report, if the timing of the requirement is unpredictable, investors should give greater weight to instruments that provide fast and friction-free access. Breaking an FD before maturity can involve a penalty, whereas a liquid fund can generally be redeemed without the same premature-closure process, subject to the scheme's terms. Investors who cannot tolerate even a temporary fall in the value of their money should give greater weight to FDs, while the practical question for investors deciding between the two is whether they value contractual certainty or market-linked flexibility.