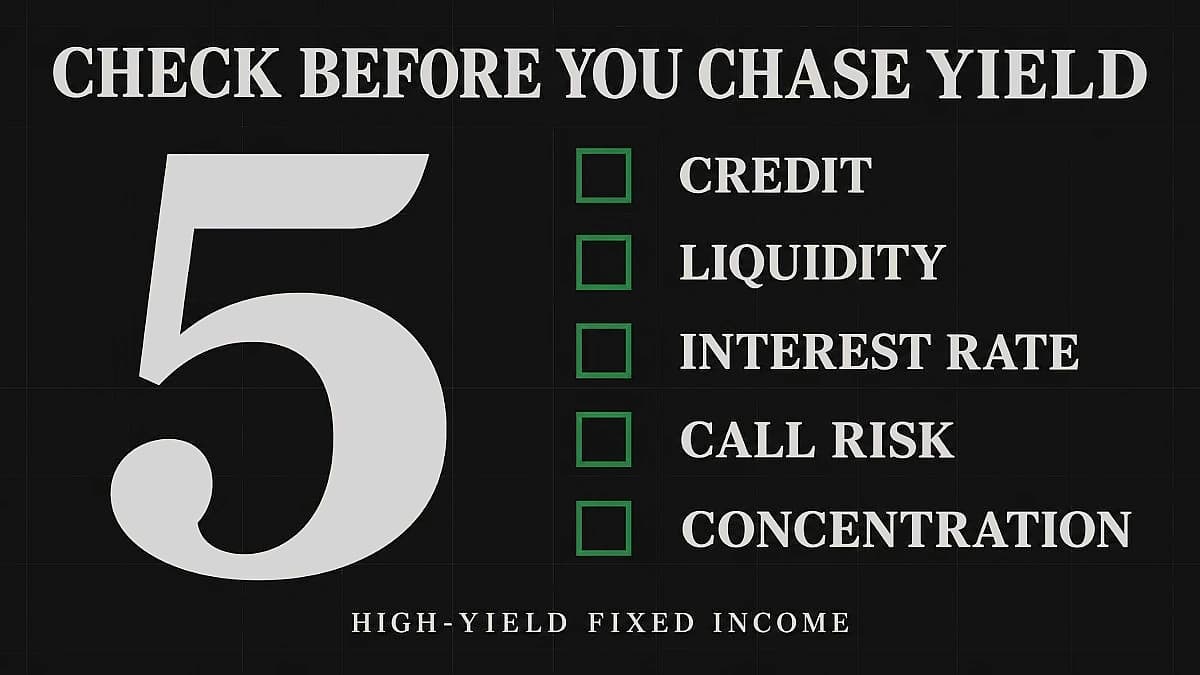
Investors considering high-yield fixed income investments in India face multiple risk factors that require careful evaluation before making investment decisions. According to recent market analysis, these risks span across credit, liquidity, rate, concentration, and tax categories, making thorough due diligence essential for any potential investment in high-yield NCDs. Recent market developments show that heavy government borrowing and the AI buildout are intensifying competition for capital, creating additional challenges for fixed income investors.
Credit risk represents one of the primary concerns for high-yield fixed income investments. As reported by market analysts, this risk stems from the potential for borrowers to default on their obligations, which could result in significant losses for investors. The creditworthiness of the issuing entities becomes crucial in assessing the overall risk profile of these investment opportunities. Recent market analysis suggests that selectivity is key in credit investments, with preference for attractive coupons away from the two extremes: the weakest borrowers and companies issuing large amounts of debt. This approach helps investors navigate the current environment where heavy government borrowing and the AI buildout are intensifying competition for capital.
Liquidity risk presents another significant challenge for high-yield fixed income investments. According to market reports, this risk relates to the difficulty in selling or exchanging securities quickly or at a favorable price when needed. The rate risk factor involves the possibility that interest rates may change during the investment period, potentially affecting the return on investment. Recent market developments show that the 10-year U.S. Treasury yield climbed back to 5%, reversing declines seen following the Fed's first rate hike in three years. Market analysts suggest that who investors lend to matters more than the absolute yield levels, emphasizing the importance of credit selection over rate chasing.
Concentration risk emerges when investors have too much exposure to a single issuer or sector, creating potential for significant losses if that entity or sector experiences difficulties. Additionally, tax considerations play a crucial role in the overall risk assessment of high-yield fixed income investments, as reported by market analysts. These tax implications can significantly impact the net returns for investors over the investment period. Recent market analysis suggests that companies with strong earnings and balance sheets have more room to absorb higher financing costs, while leveraged borrowers face greater pressure in the current environment.
When comparing investment options, investors seeking steady monthly income can consider Post Office Monthly Income Scheme (POMIS) versus bonds. For the July–September 2026 quarter, POMIS offers a fixed 7.4% interest rate with monthly payments, while bonds provide varying yields and payment frequencies. The maximum POMIS deposit is ₹9 lakh single and ₹15 lakh joint, with monthly income ranging from approximately ₹617 for ₹1 lakh to ₹9,250 for ₹15 lakh joint investment. Bonds offer different risk profiles, with government bonds providing low credit risk but varying yields, while corporate bonds may offer higher yields but higher credit risk. Investors should consider their cash-flow needs, investment horizon, and risk tolerance before allocating funds between these options, as neither product serves as a universal winner - the right choice depends on individual circumstances and preferences.