Debt funds have now adopted the same tax structure as fixed deposits (FDs), with both investment products being taxed at the investor's applicable slab rate. According to Value Research, this alignment represents a significant change in how debt funds are treated for tax purposes. However, as reported by Value Research, there remains a crucial distinction in how these taxes are applied.
The key difference lies in the timing of tax liability between debt funds and FDs. As explained by Value Research, with FDs, interest is added to the investor's income and taxed annually, even when the funds remain locked in. In contrast, debt funds are taxed at slab rate only when the investor sells the units. This deferral mechanism provides a significant advantage for debt fund investors, as the tax that would have been paid annually remains invested and continues to earn returns.
The deferral advantage of debt funds over FDs becomes particularly significant when considering compounding effects. According to Value Research, the tax that would have been paid annually on FDs stays invested in debt funds and continues to earn returns. This means that the tax liability is effectively deferred and compounded over time, potentially resulting in higher net returns for debt fund investors compared to FDs.
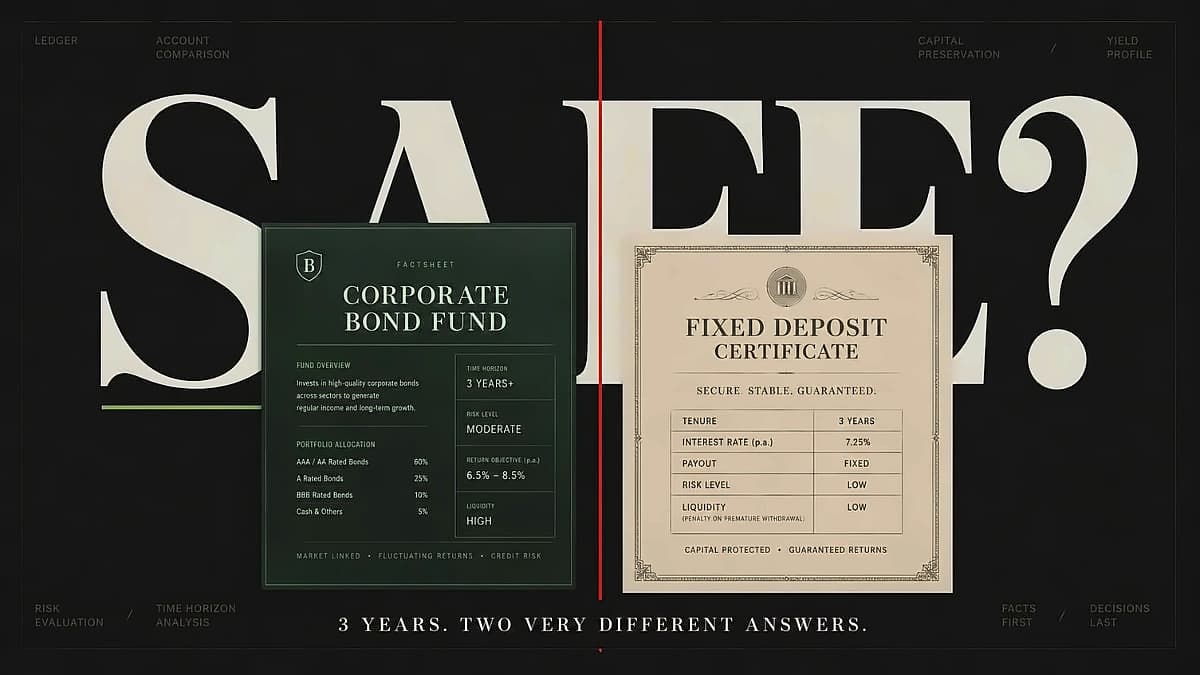
Despite the tax alignment, the actual interest rates offered by debt funds and FDs remain different. As reported by Value Research, debt funds and FDs now have similar tax structures but different rate offerings. The rate differential between the two investment products continues to exist, with investors needing to evaluate both the tax implications and actual returns when making investment decisions between debt funds and FDs.