The tax landscape for debt mutual funds has undergone significant changes since April 2023, fundamentally altering the traditional advantage debt funds held over fixed deposits. For new investments in debt-oriented mutual funds covered by Section 50AA, gains are now treated as short-term capital gains irrespective of holding period, as reported by The Economic Times. This marks a departure from the previous long-term capital gains treatment that provided indexation benefits. Specified mutual funds, investing more than 65% in debt and money-market instruments, now face taxation at applicable slab rates, eliminating the old tax advantage that debt funds enjoyed over fixed deposits. The tax treatment remains different for FDs, where interest is added to taxable income and taxed according to applicable income-tax slab, with the tax applying even in cumulative FD cases where interest isn't withdrawn annually.
Bank fixed deposits continue to offer 6.25% to 6.75% interest rates at larger banks, as reported by mutual fund expert Vishwajeet Parashar. However, recent developments show significant rate variations across different banks and tenures. Small finance banks are currently offering fixed deposit interest rates of 9% and higher, with most small financing banks being DICGC insured, meaning government protection for deposits up to ₹5 lakh. The RBI's repo rate increases of 2.5% over 10 months from May 2022 to February 2023 have contributed to these enhanced rates. For a ₹10 lakh investment over three years, a 7% FD with quarterly compounding could grow to approximately ₹12.31 lakh, generating total interest of around ₹2.31 lakh. However, after tax deduction for a 30% tax bracket investor, the net amount would be ₹11.62 lakh. A debt fund delivering 8% annualized returns would grow to ₹12.60 lakh, generating gains of ₹2.60 lakh, but after ₹78,000 tax deduction, the net amount would be ₹11.82 lakh, leaving approximately ₹20,000 more than the FD option.
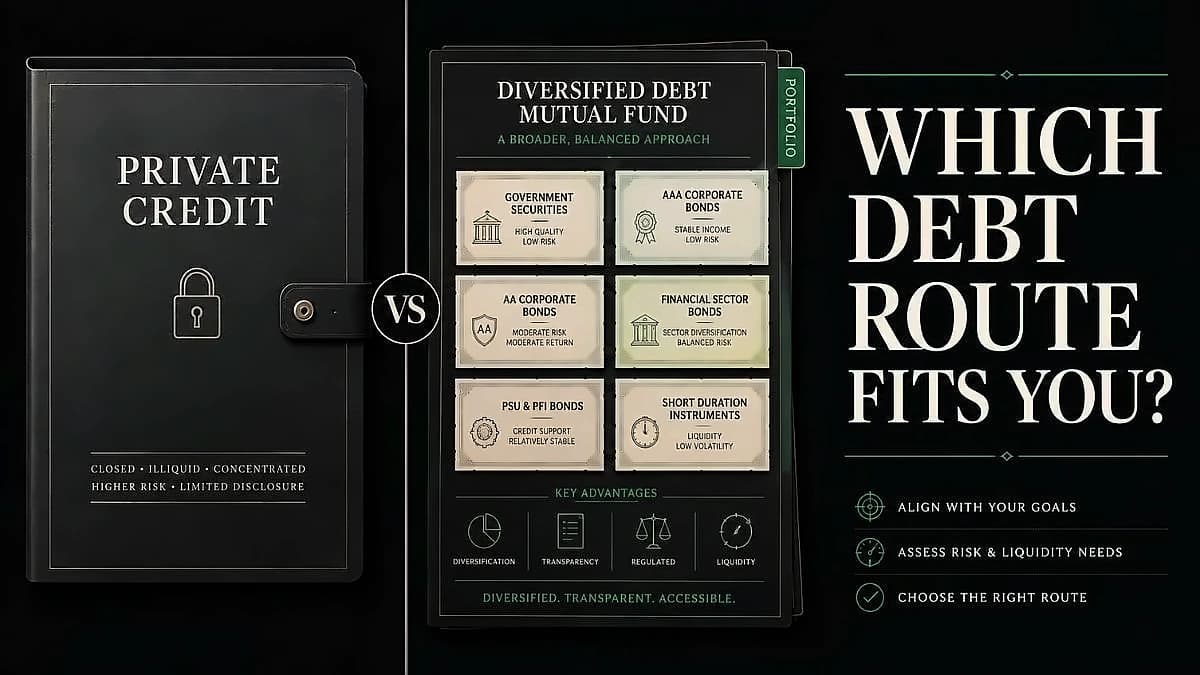
For investors with one to two-year investment horizons, experts recommend prioritizing capital preservation over chasing higher returns, as noted by Hemant Rustagi, CEO of Wiseinvest. The analysis identifies several suitable debt mutual fund categories including money market funds investing in short-term instruments with maturity profiles up to one year, ultra-short-duration funds with maturities of 6 to 12 months, and corporate bond funds investing at least 80% in AA+ rated bonds. Additionally, banking and PSU funds offer relatively low credit risk compared to other debt fund options, though their market-linked nature means they are not entirely risk-free. A one-year or two-year FMP enables strategic allocation to debt, but will have to be reinvested at market rates if the investor seeks a longer holding period. Liquid funds can be considered for investment horizons up to 90 days, offering returns of 6% to 7% with no exit load after seven days.
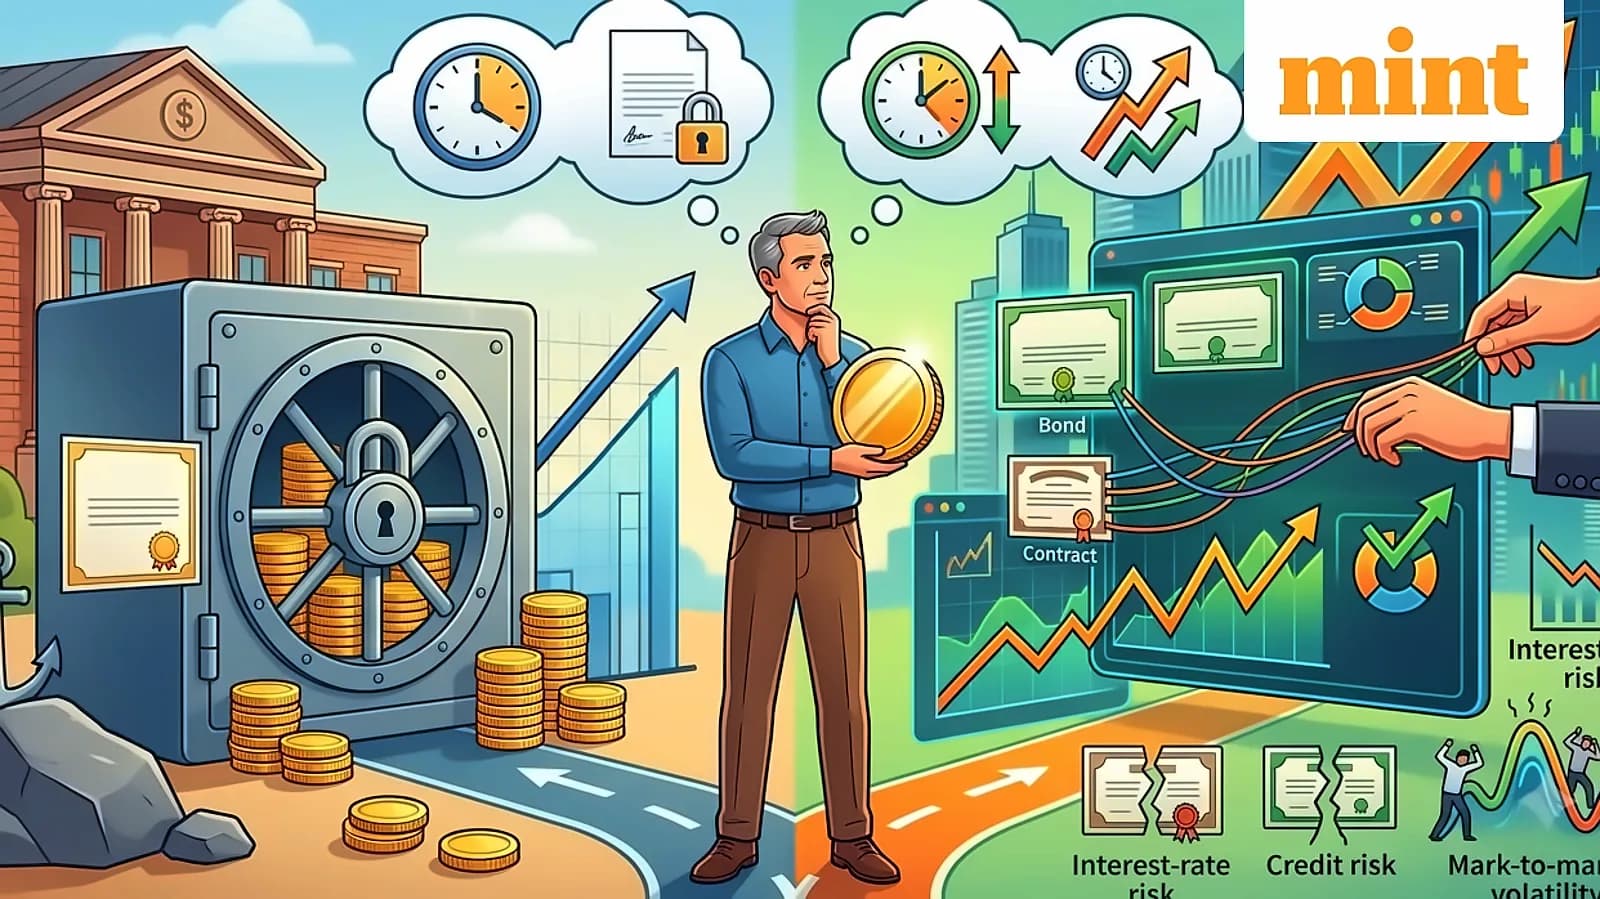
The primary difference between FDs and debt mutual funds lies in predictability of returns and nature of risks involved. Bank FDs offer contracted interest rates subject to deposit terms, while debt mutual funds face market movements and potential negative returns. Interest-rate risk can affect debt securities, and credit risk arises when issuers fail to meet repayment obligations. The tax treatment varies significantly - FD interest is taxable as earned, while debt mutual fund gains are generally taxed at redemption. Recent market data shows that in the US, only 14% Indians want to invest in FDs as against 20% in the UK, indicating varying preferences across international markets. Debt funds offer practical advantages including easier partial withdrawals and potential for better returns, but there is no guarantee of returns. The final value is not fixed, as interest-rate movements can affect bond prices and credit risk matters depending on securities held by the scheme.
Experts emphasize that neither option is universally better for one to two-year investment horizons, with the decision depending on individual risk tolerance, liquidity needs, and return expectations. For investors with very short horizons, liquid or ultra-short-term funds are recommended, while money market, ultra-short-duration, short-duration, corporate bond, and banking and PSU funds are suitable for one to two-year goals. The analysis concludes that investors should align fund maturity duration with investment period and focus on credit quality rather than chasing higher returns, with the final decision based on tolerance for market uncertainty and when funds may be needed. Taxation alone should no longer be the primary reason for choosing debt funds over FDs, as the new tax rules have eliminated the traditional advantage. The key takeaway is to compare expected return, risk, liquidity, investment period and tax slab before deciding between the two options.