Sign in to fuzzto save your conversations, follow your research and come back anytime.

Vodafone Idea Limited is the third largest wireless operator in India, with a 18.7% revenue market share as of December 2022. It offers voice, data, and enterprise services across 2G, 3G, and 4G platforms. The company has a subscriber base of 236.8 million as of March 2023, with a 20.7% market share. Vodafone Idea holds 8,005.2 MHz spectrum across 22 service areas, including 7,975.2 MHz of liberalized spectrum. The company provides various services including broadband, content, digital offerings, and business solutions for corporations and government bodies. In 2022, Vodafone Idea launched integrated IoT solutions for enterprises and a consumer analytics platform. The company acquired 5G spectrum in 2023 and has 443,537 broadband sites as of March 31, 2023. The Indian government holds a 33.1% stake in the company, while the Vodafone Group and Aditya Birla Group collectively own 50.4%.
In the news
Vodafone Idea launches free international roaming, CLSA flags spectrum debt
Nifty Crashes Below 22,500: Iran-US Tensions Drive Market Rout
Vodafone Idea's Strategic Gambit: Free Roaming, ₹35,000 Cr Fundraise, and the Path to 5G
Vodafone Idea Stock Rises 2% on Free Roaming Across 170+ Countries
Vodafone Idea shares rise 1% snapping 2-day losing streak
Vodafone Idea Shares Rise 2% as SBI Set to Issue $3.5B Funding Sanction
Vodafone Idea's High-Stakes Turnaround: Can It Deliver?

Vodafone Idea stock rises 28.8% on Jefferies 'buy' call, targets ₹36
Vodafone Idea's GST Victory: Legal Precedent Sets New Rules for Post-Merger Tax Liability

Supreme Court dismisses Vodafone Idea's ₹363 cr GST plea
Market Experts Share Buy, Hold, Sell Recommendations for 21 Stocks

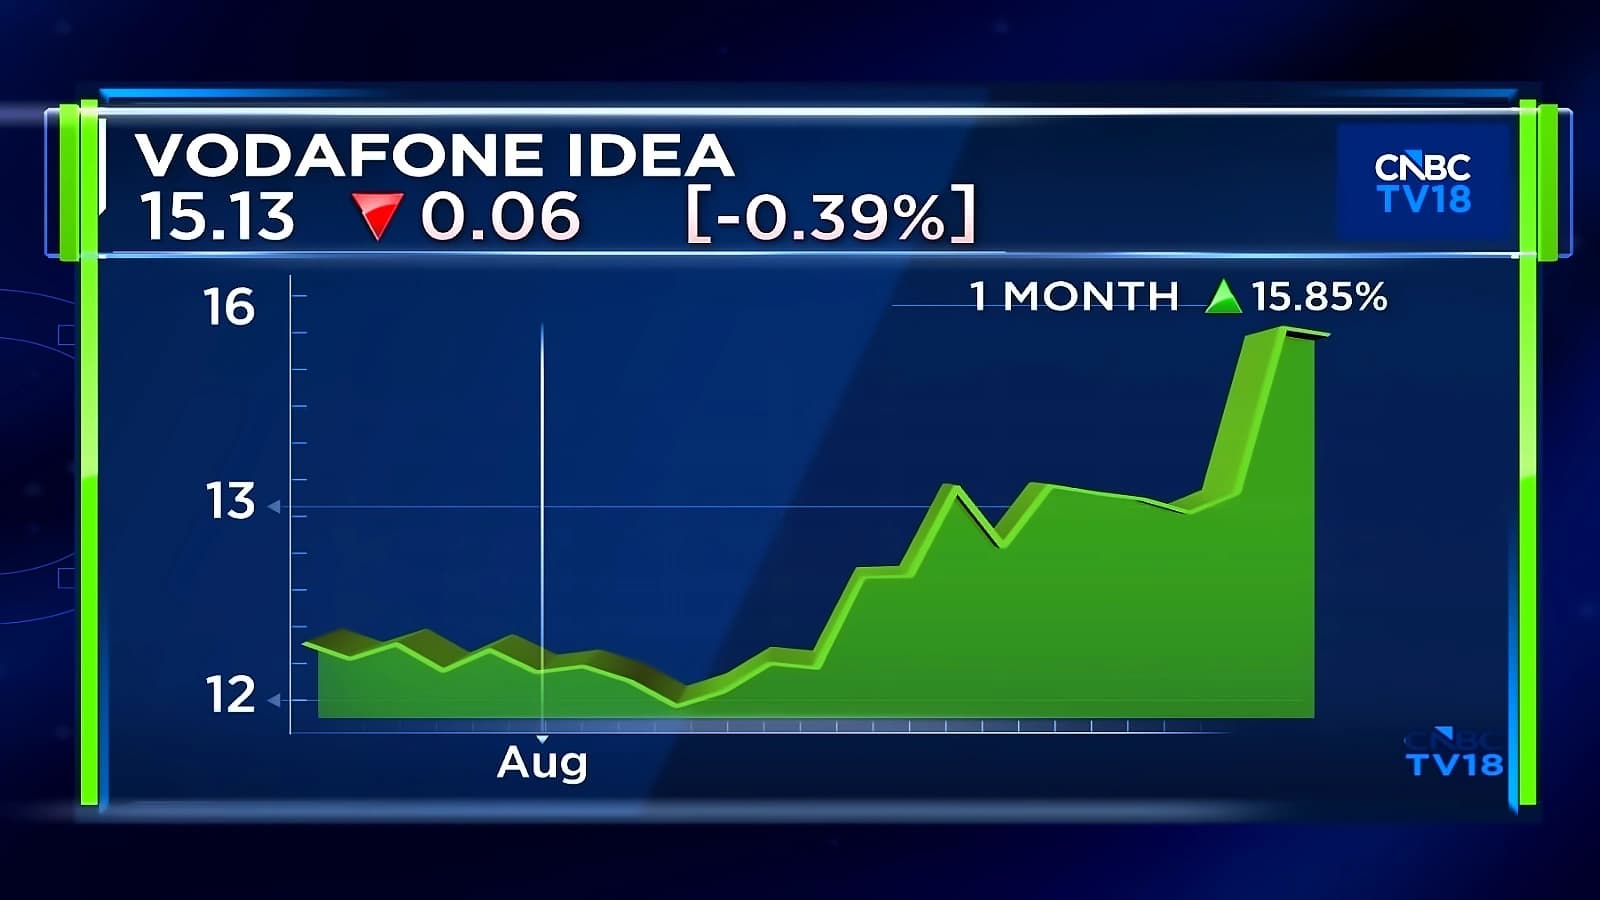
Vi hits 25-month high at ₹15.65 on Khan brand ambassador announcement
Vodafone Idea's FY27 Turnaround: AGR Relief, Tariff Hikes, and the 5G Balancing Act
Vodafone Idea, BSNL expand network sharing as India drops biometric database
Telecom tariffs may rise 12% in 4-6 months; Centrum lists top picks
Vodafone Idea stock surges 8% on ₹53 cr tax refund order

Vodafone Idea turns customer tide after AGR relief, adds 240K subscribers
Vodafone Idea's Q1 FY27: Loss Halves as Turnaround Gains Momentum
Vodafone Idea's Tariff Hike Imperative: The Rs 45,000 Crore Capex Challenge
Vodafone Idea's Rs 26.83 Crore Penalty: Compliance, Cash Flow, and Strategic Choices
The Quarter story
The two most recent quarterly results, compared side-by-side.
Vodafone Idea drives strong revenue and ARPU growth with optimized capex, while total subscriber base and select regional market shares face mild pressure.
Revenue grows from ₹110.2 Cr in Q1 FY26 to ₹11,689 Cr in Q1 FY27, confirming strong top-line expansion.
Total subscribers decline from 197.7 Mn in Q1 FY26 to 193.1 Mn in Q1 FY27, signaling base stabilization with ongoing churn.
Customer ARPU rises from ₹177 in Q1 FY26 to ₹195 in Q1 FY27, demonstrating successful pricing power.
Market share in Gujarat slips from 28% in Q1 FY26 to 27% in Q1 FY27, indicating slight competitive erosion.
4G/5G subscribers increase from 127.4 Mn in Q1 FY26 to 130.1 Mn in Q1 FY27, signaling steady network adoption.
Market share in Mumbai drops from 34% in Q1 FY26 to 33% in Q1 FY27, reflecting minor urban pressure.
Net adds improve from -0.5 Mn in Q1 FY26 to 0.3 Mn in Q1 FY27, confirming a shift to subscriber growth.
Market share in Tamil Nadu falls from 15% in Q1 FY26 to 14% in Q1 FY27, showing slight regional weakness.
Capex falls from ₹2,252 Cr in Q3 FY26 to ₹1,930 Cr in Q1 FY27, reflecting optimized network spending.
Broadband sites fall sharply from 516,200 in Q2 FY26 to 205 in Q1 FY27, indicating infrastructure rationalization.
Company insights, generated from the most recent coverage.
Management's preference for debt over equity funding avoids dilution but leaves Vi dependent on lender terms; any slippage transmits directly to Indus Towers sentiment.
Q1 FY27 revenue of ₹11,689 Cr (+6.0% YoY) against a ₹45,000 Cr three-year capex plan means Vi must fund spend far beyond internal accruals — the gap is what caps Indus Towers' tenancy upside.
Q1 FY27 profit is flattered by a ₹1,816 Cr one-time exceptional item against ₹3,701 Cr of net finance costs — strip the exceptional and the core business is still nowhere near covering its interest bill.