Sign in to fuzzto save your conversations, follow your research and come back anytime.

In the news
Kotak Backs Chinese Investment Partnerships Amid US Trade Tensions
Nifty Targets 26,500 by March 2027: MNCL CEO Sees Global Recovery
Stocks in Focus: Trent Surges 13% on Q2 Results; Kotak Bank Gains 4%
Bank stocks mixed as RBI hikes rates; Nifty Bank hits 54,636
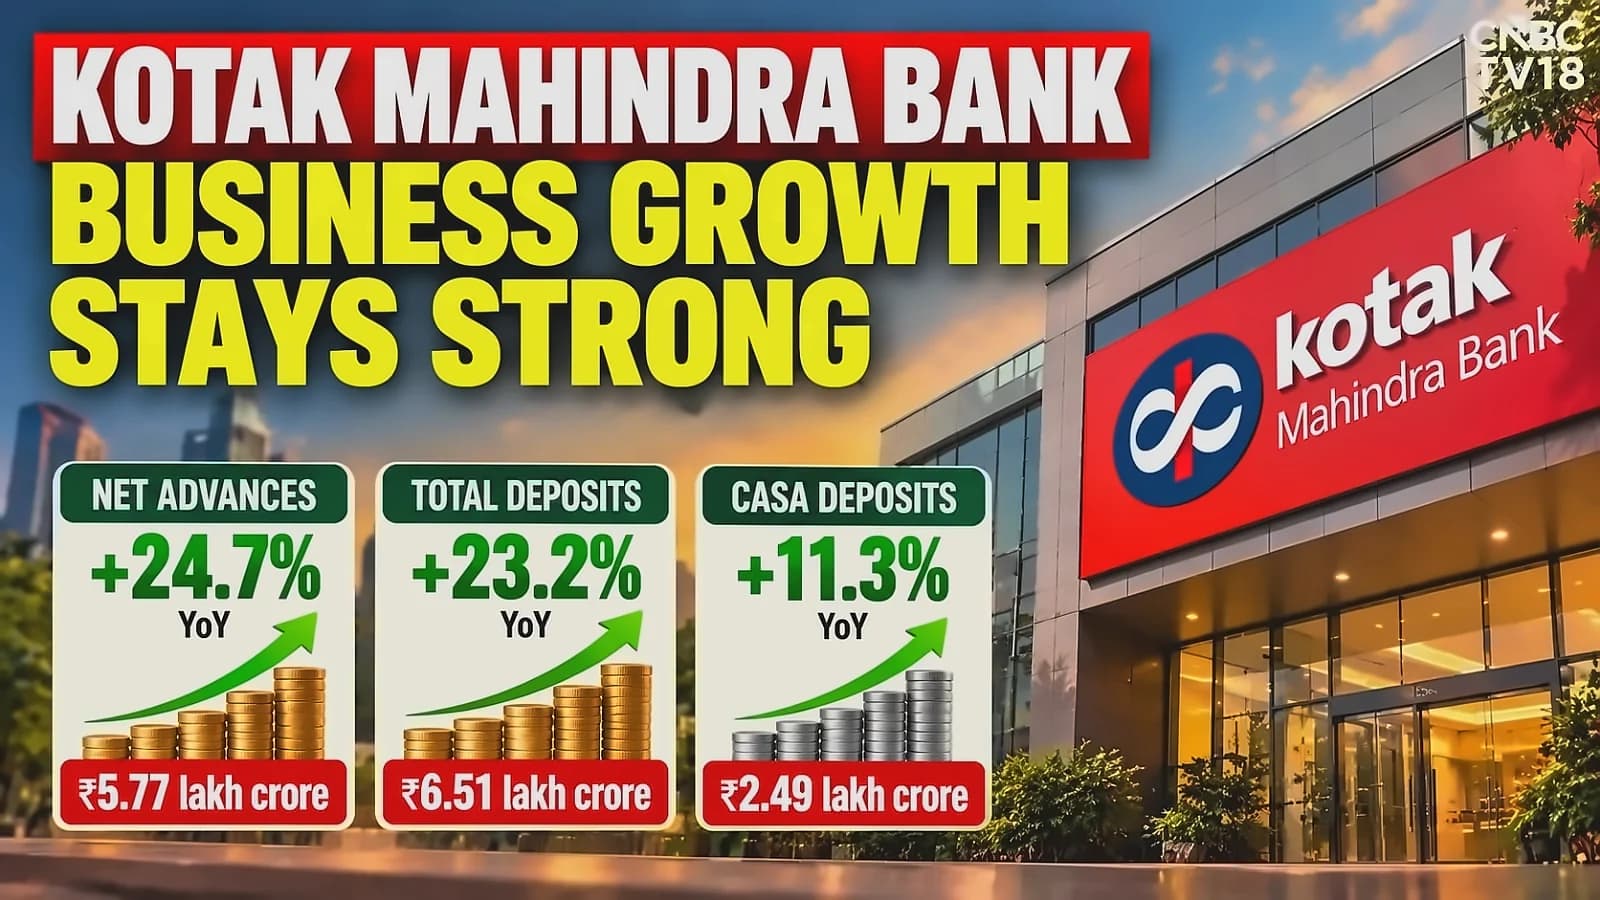
Kotak Mahindra Bank Q2: Net advances jump 25%, shares rise 2%
HDFC Bank Q2 updates: RBI clears Anup Bagchi as new CEO; shares fall 2%
Kotak's Strategic Gamble: The Anup Kumar Saha Story
Kotak Bank shares surge 0.95% on Saha's retail strategy; brokerages forecast up to 28% upside
Macquarie upgrades 11 financial stocks with 22% upside potential
Gen Z home loan borrowers surge 86% as India's home-buying age drops
Kotak Bank Benefits from RBI's ₹1.1 Lakh Crore FCNR-B Inflows
HDFC Bank CEO search: RBI weighs Anup Bagchi amid regulatory concerns
Kotak Bank's Manish Kothari resigns after 31 years, plans entrepreneurial venture
India Inc earnings recovery gains momentum as banking sector shows improvement
Kotak Bank CEO Succession: Saha vs Kashyap
Kotak Mahindra Bank recommends two internal CEO candidates
Kotak Mahindra Investments CFO Siddarth Gandotra Resigns, Vora Takes Over
Private Banks: Why Strong Profits Couldn't Stop the Rs 1.5 Lakh Crore Selloff
ICICI Bank vs HDFC Bank Q1FY26: Why the Divergence?
Kotak Mahindra Bank: Leadership Shift, Strategic Moves, and Q1FY27 Performance
The Quarter story
The two most recent quarterly results, compared side-by-side.
Kotak Mahindra Bank posts strong profit growth and improving asset quality, while managing AUM volatility and microcredit headwinds.
Consolidated PAT grows from ₹272 Cr in Q1 FY26 to ₹4,123 Cr in Q1 FY27, driven by higher fee income and stable margins.
Customer AUM falls from ₹750,143 Cr in Q1 FY26 to ₹103,156 Cr in Q4 FY26, signaling significant asset outflows.
Net NPA ratio falls from 0.34% in Q1 FY26 to 0.27% in Q1 FY27, reflecting consistent credit cleanup.
BSS Sonata Microcredit PAT deteriorates from -₹22 Cr in Q2 FY26 to -₹73 Cr in Q4 FY26, indicating widening operational losses.
Net advances expand from ₹444,823 Cr in Q1 FY26 to ₹512,249 Cr in Q1 FY27, showing steady loan book growth.
CASA ratio dips from 43.3% in Q4 FY26 to 40.3% in Q1 FY27, reflecting a shift toward higher-cost term deposits.
Fee and services income rises from ₹2,249 Cr in Q1 FY26 to ₹9,981 Cr in Q4 FY26, highlighting strong cross-selling momentum.
IPO and QIP distribution value drops from $8.03B in Q3 FY26 to $0.96B in Q4 FY26, showing volatile deal flow.
Gross written premium surges from ₹2,861 Cr in Q1 FY26 to ₹9,207 Cr in Q4 FY26, demonstrating robust policy sales.
Protection segment ROE declines from 20.4% in Q1 FY26 to 9.6% in Q4 FY26, pointing to margin compression.
Company insights, generated from the most recent coverage.
Kotak's own Q1 FY27 commentary contradicts its capex optimism — construction equipment demand is soft and hinges on raw material availability and government spending, so steel/cement-led capex is a thesis, not yet a booked reality.
Kotak cautions global uncertainty caps the rupee benefit: risk-off sentiment, a stronger dollar or higher global yields pull FPIs from EMs regardless of local hedging rules, so domestic regulation cannot offset a global flow reversal.
Kotak's 'sub-95' USD/INR call is an immediate-reaction view, not a medium-term forecast — once speculative positions unwind, BoP fundamentals take over, so the relief is a one-time re-pricing rather than a trend reversal.