Sign in to fuzzto save your conversations, follow your research and come back anytime.

In the news
Tata Chemicals rebounds 14% from low, up 15% on listing hopes despite earnings pressure
Afcons Infrastructure jumps 4.4% on ₹335.50 crore arbitral award
Afcons Infrastructure faces execution challenges despite record orders
Afcons wins ₹1,918 cr Mumbai water tunnel project from BMC
Afcons Infrastructure sets July 23 record date for ₹2 dividend
Afcons shares surge 10% on ₹5,301 cr Vadhvan Port breakwater project

Afcons Infrastructure Rallies 8% on ₹5,301 Cr Vadhvan Port Order
Afcons Infrastructure wins ₹5,301 cr Vadhvan Port breakwater order
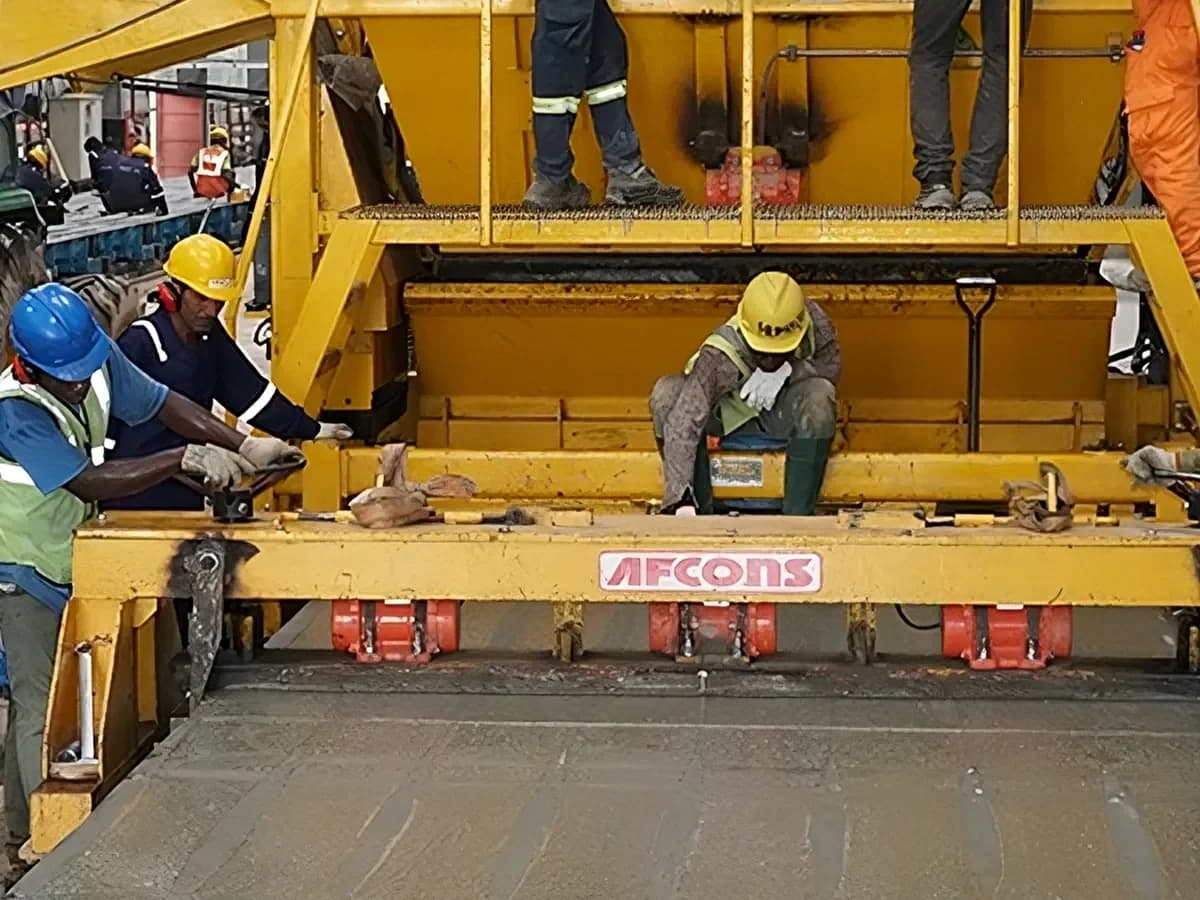
Afcons wins ₹5,301 cr Vadhvan Port breakwater contract
Market Movers: Fuel Hikes, Adani Relief, and Corporate Earnings Shape May 2026 Landscape
Afcons Infrastructure posts ₹89 cr Q4 loss vs ₹111 cr profit last year

Afcons Infrastructure Q4 loss of ₹88 cr, shares crash 4%
Afcons Infra posts ₹88-cr Q4 loss, declares ₹2 dividend

Afcons Infra shares focus on Q4 results amid Croatia contract cancellations
Afcons Infrastructure shares dip 3.92% despite €677M Croatia railway win

Afcons Infrastructure wins ₹7,544 crore Croatia railway project
Afcons Infrastructure secures ₹373 cr orders in April
Afcons shares hit 52-week low after €113mn Gabon contract termination

Afcons Infrastructure Q3 profit drops 34.77% to ₹97 crore
Afcons Infra Q3 Results: Margin up 240bps despite revenue decline
The Quarter story
The two most recent quarterly results, compared side-by-side.
Order book surges and costs tighten, but revenue slowdown and margin compression weigh on profitability.
Order book surged from ₹31,543 Cr in Q3 FY26 to ₹43,290 Cr in Q1 FY27, securing future project visibility.
PAT margin contracted from 4.0% in Q1 FY26 to 1.1% in Q1 FY27, highlighting bottom-line compression.
Material costs declined from ₹680 Cr in Q1 FY26 to ₹577 Cr in Q1 FY27, reflecting efficient procurement.
Revenue from operations slipped from ₹3,370 Cr in Q1 FY26 to ₹2,671 Cr in Q1 FY27, reflecting project execution slowdowns.
Employee expenses fell from ₹378 Cr in Q1 FY26 to ₹303 Cr in Q1 FY27, demonstrating tighter payroll control.
Hydro & Underground order share fell from 25% in Q1 FY26 to 16% in Q1 FY27, indicating pipeline dilution in core segments.
Surface Transport order share grew from 5% in Q1 FY26 to 24% in Q1 FY27, highlighting major highway wins.
EBITDA margin dropped from 14.0% in Q3 FY26 to 9.6% in Q1 FY27, showing cost absorption challenges.
Marine & Industrial order share expanded from 13% in Q1 FY26 to 22% in Q1 FY27, signaling strong segment momentum.
Urban Infrastructure order share declined from 54% in Q1 FY26 to 37% in Q1 FY27, marking a portfolio rebalancing away from city projects.
Company insights, generated from the most recent coverage.
SP Group's ₹25,000 Cr stake sale to Tata Sons eliminates pressure to extract cash from Afcons for debt servicing, preserving working capital for project execution.
Parent group deleveraging reduces cross-guarantee requirements and refinancing risk, improving Afcons' credit profile and bidding capacity for large infrastructure projects.
Resolution of SP Group's liquidity crisis via Tata Sons stake monetization reduces cross-guarantee pressures on Afcons, allowing management to focus on executing its ₹45,000 Cr order book rather than debt servicing.