The Mumbai bench of the Income Tax Appellate Tribunal (ITAT) has deleted a ₹55.2 lakh tax addition made to a taxpayer's income after finding that the property was jointly purchased by multiple family members. According to The Times of India, the case involved a man who bought a residential property jointly with his wife and father during the 2015-16 financial year, but did not file an income tax return for the relevant year. The Income Tax Department reopened his assessment for the 2016-17 assessment year after receiving information through its Risk Management Strategy, treating the entire purchase as unexplained investment under Section 69 read with Section 115BBE.
The Mumbai bench of the Income Tax Appellate Tribunal (ITAT) has ruled that ₹82 lakh received by a flat owner as hardship compensation under a redevelopment agreement was not taxable as income. In a ruling dated 25 March 2026, the tribunal held that the compensation was not consideration for the sale or transfer of a right in immovable property. The case involved Ranjana Hemant Pendharkar v. Income Tax Officer, ITA No. 7825/Mum/2025, for assessment year 2016-17. The tribunal examined the redevelopment agreement and noted that the lump-sum amount was intended to compensate members for hardship, shifting and resettlement, as well as for allowing their old flats to be demolished.
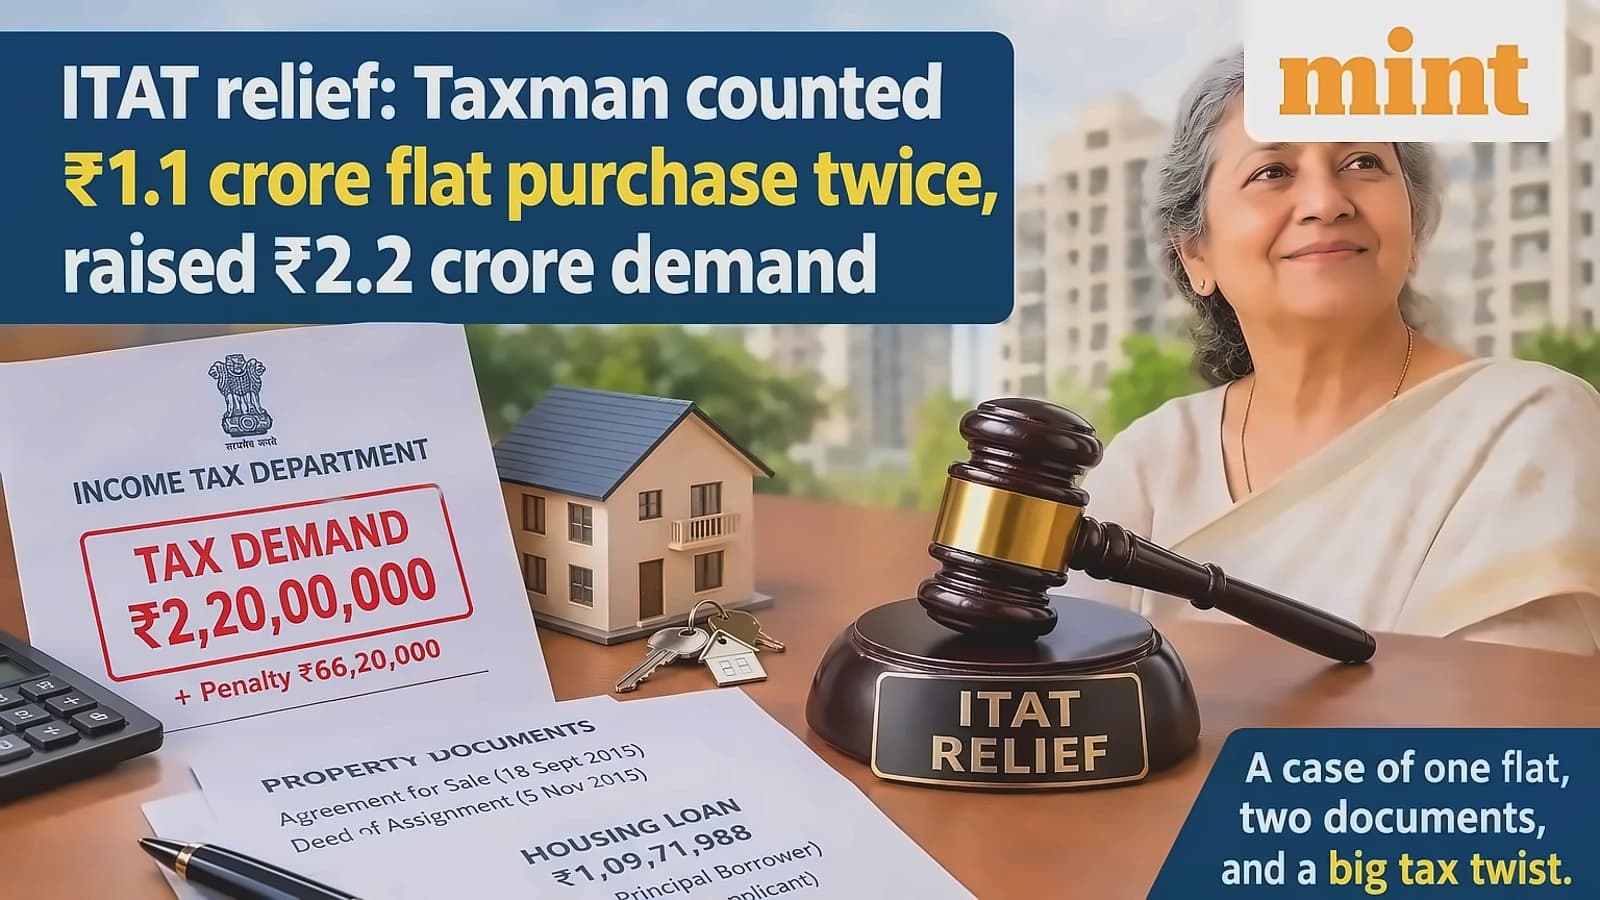
A senior citizen in Navi Mumbai faced a ₹2.20 crore tax addition after the Income Tax Department treated two documents for the same flat as separate purchases. According to reports from Mint, Jaishri Pande, a senior citizen with no independent source of income, had not filed an income tax return for the relevant assessment year. The tax authorities initiated scrutiny after the Risk Management System flagged two entries relating to property transactions, each valued at ₹1.10 crore. The entries were dated 18 September and 5 November 2015, with the assessing officer treating them as two separate purchases and reopening her assessment. A notice under Section 148 of the Income Tax Act, 1961, was issued on 26 March 2023, followed by the AO completing the reassessment on 29 February 2024.
The Mumbai bench of the Income Tax Appellate Tribunal (ITAT), in an order dated 23 September 2026, granted relief to the taxpayer after finding that the property was jointly owned and funded through multiple sources. As reported by The Times of India, the taxpayer explained that the property had been funded through several sources, including a ₹32 lakh housing loan from a bank and contributions from himself and his family members. The assessing officer accepted the housing loan but considered that the remaining investment was insufficiently explained. The National Faceless Appeal Centre had upheld the addition, finding that the evidence submitted at that stage did not adequately establish the sources of contributions attributed to the taxpayer's father and wife. However, the ITAT accepted the taxpayer's explanation after he submitted additional documents, including bank statements, employment records, and material relating to his father's pension and funds.
The tribunal found that the higher figure adopted by the assessing officer was not substantiated by the documents on record, as reported by The Times of India. The agreed consideration recorded for the property was ₹80 lakh, but the assessing officer had used ₹87.2 lakh to calculate the unexplained investment. The taxpayer contended that actual payments, including VAT, were ₹84 lakh. The tribunal held that the investment could not be treated as unexplained in the manner adopted by the assessing officer, deleting the ₹55.2 lakh addition under Section 69 read with Section 115BBE. According to Raghav Bajaj, Partner at Khaitan & Co, the ruling restates an important principle: Section 69 is not a tool for presumptive attribution, and before an investment can be taxed as unexplained, it must first be established that the taxpayer has made an investment.
The tribunal's decision emphasizes that pooling salaries, pensions, savings and inherited funds to buy a home is a familiar reality for Indian families, as noted by Raghav Bajaj from Khaitan & Co. The ruling recognizes each contributor's role in joint property purchases, with the tribunal finding that the payments towards the property could be identified and were supported by documentary material. Taxpayers should maintain clear, person-wise records of contributions from the day of purchase, particularly in cases where title is shared among co-owners. Bajaj adds that analytics-led reassessments are legitimate ways to identify high-value transactions, but data flags should be the beginning of an inquiry, not its conclusion, with each co-owner's sources examined on their own merits.