The Kolkata bench of the Income Tax Appellate Tribunal (ITAT) has ruled in favor of a homebuyer who faced a tax notice despite paying a substantial upfront amount. According to reports from The Times of India, the taxpayer and her husband entered into a registered agreement in January 2021 to purchase an immovable property for ₹1.23 crore, but by the time registration occurred in September 2023, the circle value had increased to ₹1.46 crore. The Assessing Officer (AO) considered this difference as a taxable benefit under Section 56(2)(x), adding approximately ₹11.35 lakh to the taxpayer's income.
As reported by The Times of India, the AO compared the revised stamp duty valuation with the actual consideration of ₹1.23 crore and considered the resulting difference a benefit received by the homebuyers. Under Section 56(2)(x), there is applicable taxation of such differences if the stamp duty value exceeds the purchase consideration by more than the greater of ₹50,000 or 10% of the consideration. The difference of approximately ₹22.71 lakh exceeded 10% of the agreed purchase price, leading to the addition of ₹11.35 lakh to the taxpayer's taxable income under 'Income from Other Sources'.
According to reports from The Times of India, the taxpayer contested the assessment before the CIT(A), arguing that the AO had relied on an incorrect date for determining the property's value. The CIT(A) rejected her plea and sustained the addition through an order dated March 31, 2026. In her appeal before the Tribunal, the taxpayer invoked specific relief provisions under Section 56(2)(x) that address transactions where the agreement date differs from the registration date. The Tribunal considered both the registered purchase agreement and the conveyance deed executed later, finding that the AO's application of the higher stamp duty valuation on September 18, 2023 was incorrect.
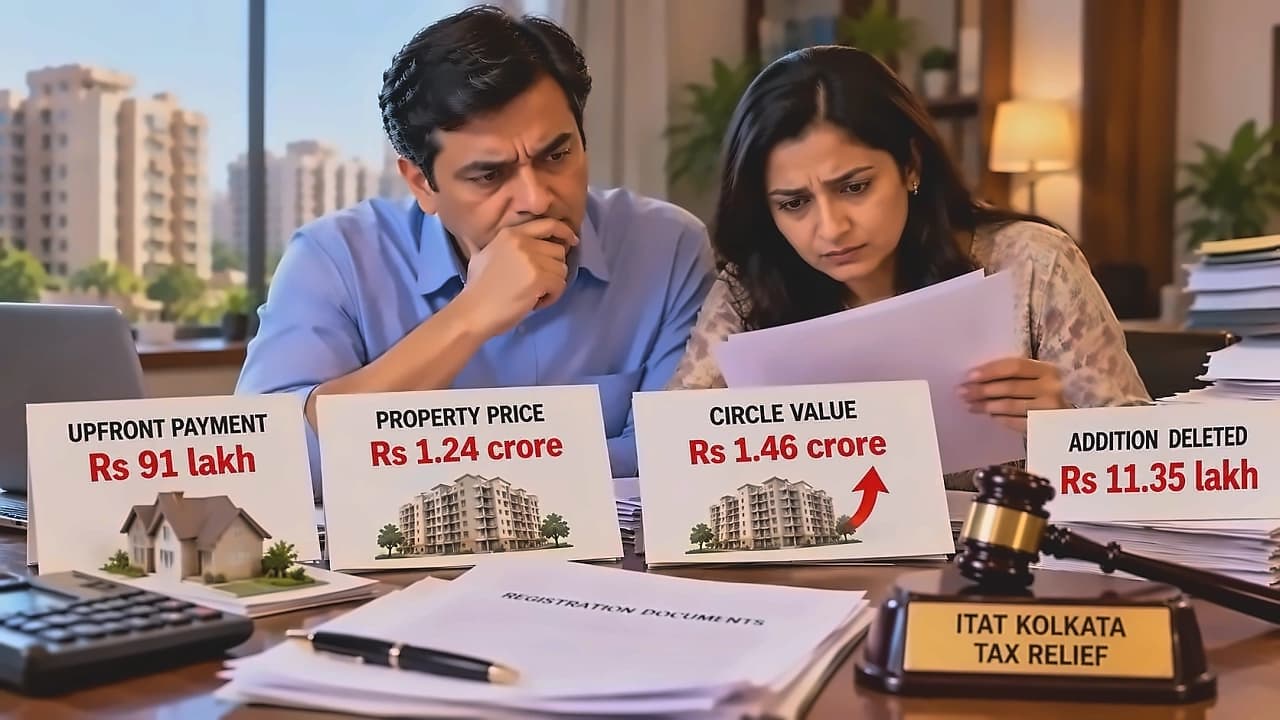
As reported by The Times of India, to qualify for relief under the provisos to Section 56(2)(x), the buyer must have paid at least a portion of the consideration through prescribed banking or electronic payment methods on or before the date of the agreement. CA Suresh Surana explains that if the buyer demonstrates a genuine agreement was entered into earlier and payment was made through prescribed channels, the law allows the stamp duty value as on the agreement date to be considered. The Tribunal found that the taxpayer had paid ₹91 lakh through banking channels on or before the agreement date, and the conveyance deed's execution in September 2023 was not a valid reason to replace the circle rate applicable when the parties originally agreed on the purchase price.