The Income Tax Appellate Tribunal (ITAT), Delhi Bench, has deleted tax additions worth ₹4.14 crore made against a taxpayer in a land conversion dispute. According to The Times of India, the taxpayer had filed his income tax return for assessment year 2021-22 declaring total income of ₹1,05,59,170, but faced scrutiny that resulted in significant additions totaling ₹4,14,77,278. The assessing officer made two major additions: ₹1,93,78,293 as long-term capital gains on land conversion and ₹2,20,98,985 as business income from alleged stock-in-trade sale.
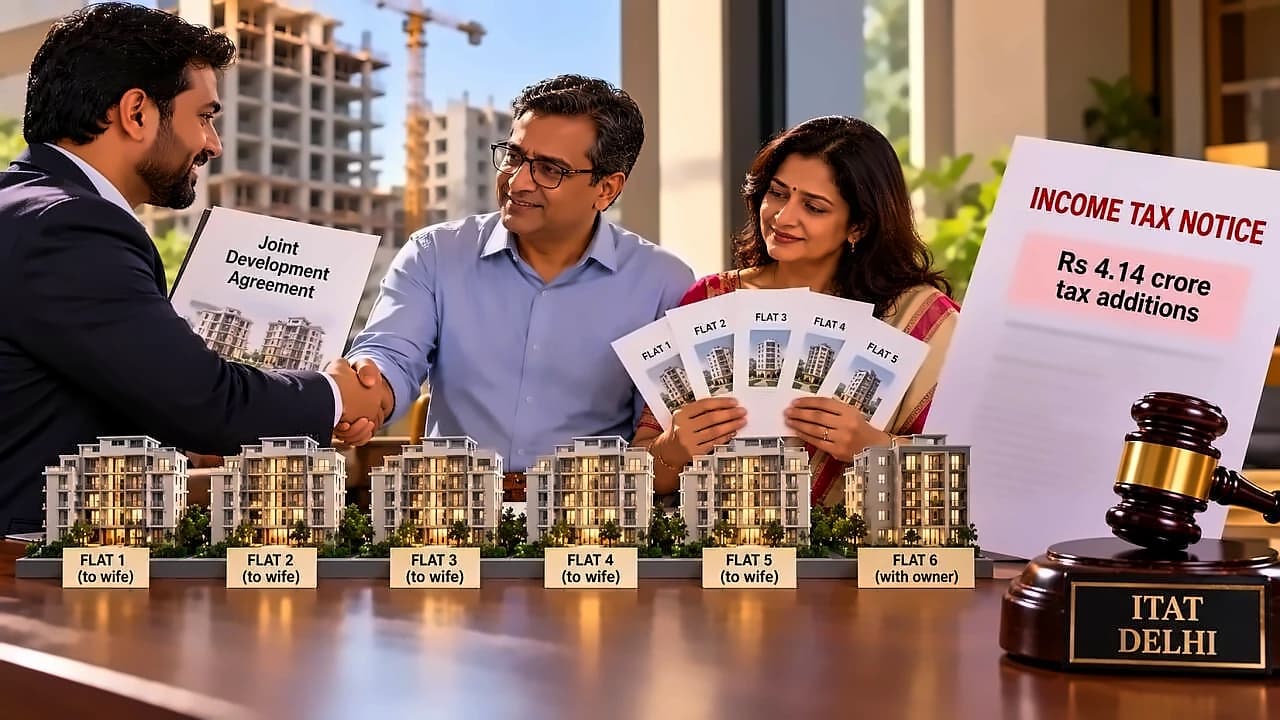
The dispute arose from a joint development agreement from 2016 where the taxpayer contributed his land while the developer constructed a multi-storeyed building at its own cost. As reported by The Times of India, the taxpayer received six flats in return for his contribution. The tax department's position was that this arrangement resulted in the land being converted into stock-in-trade, but the taxpayer argued he was an individual not carrying on real estate business and had no business infrastructure or accounting records showing inventory conversion.
The second addition arose after the taxpayer transferred five of the six flats to his wife through sale deeds in 2020. According to The Times of India, the assessing officer treated this as a sale, resulting in the ₹2,20,98,985 business income addition. The taxpayer produced his wife's affidavit stating no consideration was paid and submitted her bank statement to support his claim that no money changed hands. He explained the transfer was made to safeguard property interests and enable mortgage with banks.
The case has progressed through multiple levels of appeal, with the latest development showing the CIT(A) dismissed the appeal on grounds that the taxpayer failed to adduce supporting evidence for his claims. As per the latest court filings, the taxpayer has sought to set aside the order under section 250 of the Income Tax Act, 1961, dated 27.01.2026, and requested refund of ₹8,01,500 deposited on 28.02.2019 along with interest. The appeal specifically challenges the computation of ₹68,98,500 long-term capital gains for assessment year 2011-12, arising from a land development agreement dated 11.02.2011 with M/s Om Sai Builders & Developers.
The ITAT Delhi bench ruled in favor of the taxpayer, finding that no stock-in-trade conversion was proved beyond doubt. As reported by The Times of India, the tribunal referenced earlier decisions where taxpayers not engaged in real estate business could not be said to have converted land into stock-in-trade merely through joint development agreements. The tribunal observed that the taxpayer was 'not in the business related to real estate' and held that the joint development agreement's nature did not automatically change the asset's character. It also concluded that the transfer could not be treated as a genuine sale without actual payment evidence. According to Sarthak Prashar, Director at Grant Thornton Bharat, the ruling reinforces that property transaction character must be determined from substance and evidence, not just agreement language.