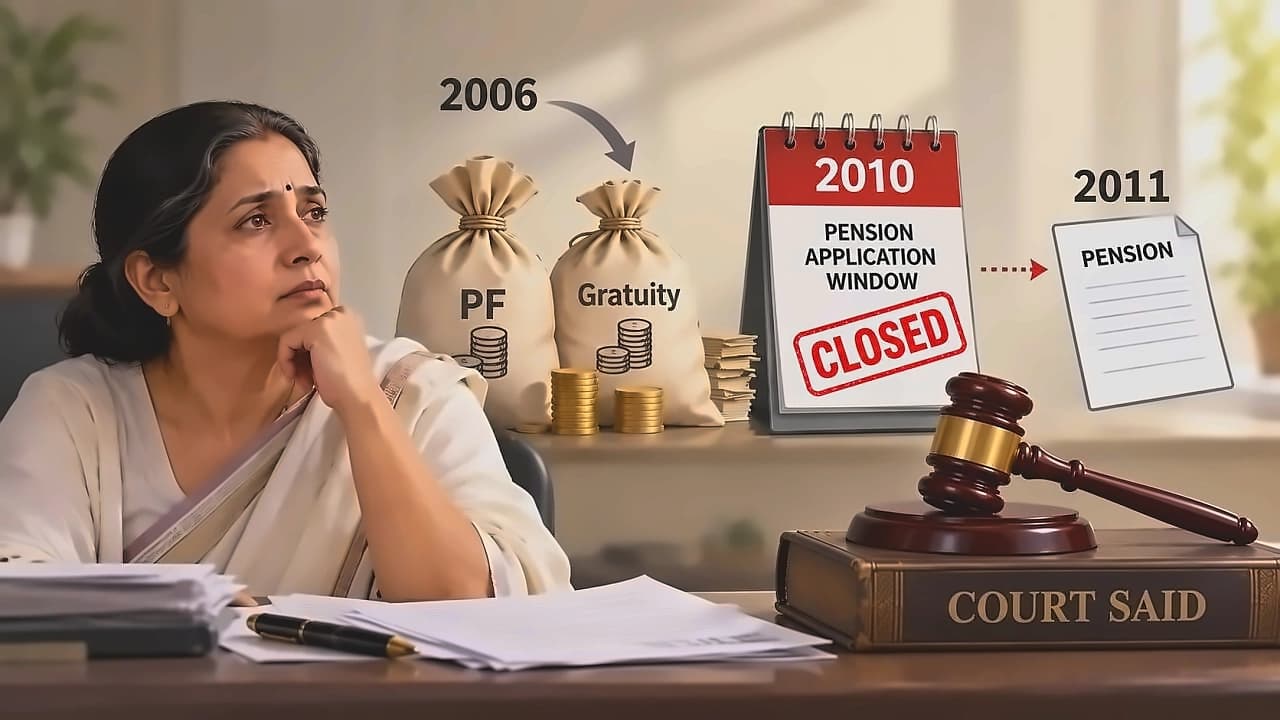
A Delhi High Court has dismissed a pension claim by a widow who received her husband's provident fund and gratuity benefits but missed the deadline to opt for family pension under a one-time scheme. According to reports from Mint, the court ruled in Savitri Devi v. Bank of Maharashtra & Anr on July 7, 2026, that the widow failed to exercise the pension option within the prescribed deadline and could not establish proof of timely submission. The case involved Savitri Devi, widow of late Ramesh Chand who died in service on February 12, 2006, while covered by the contributory provident fund regime. As reported by The Times of India, the court emphasized that timely submission is constitutive of the right itself, and equitable relief cannot be granted to rewrite the scheme or bypass mandatory eligibility conditions.
The August 18, 2010 circular covered families of employees who joined the bank before September 29, 1995 and died in service after that date. As reported by The Times of India, the scheme required eligible families to submit the prescribed Annexure III option form by October 18, 2010, with the branch required to acknowledge receipt and retain copies. The circular specifically stated that families whose forms were not received within the stipulated period would not be eligible for pension or family pension. Devi relied on an option form dated March 2, 2011, several months after the deadline, but lacked branch acknowledgment or contemporaneous records. According to The Times of India, the circular mentioned that an acknowledged copy should be kept by the family member, but no such acknowledged copy bearing the branch receipt or date-stamp was produced before the high court.
According to The Times of India, Devi also relied on internal correspondence between the bank's branch and head office in January 2014, where the branch forwarded her option form seeking guidance. However, the High Court found this correspondence did not amount to the bank accepting her pension option or condoning the delay. The court observed that the January 18, 2014 communication cannot be read as an unequivocal acknowledgment by the bank that a valid option had been submitted and acted upon in March 2011. As reported by The Times of India, while forwarding a copy of the option form to the Head Office, the branch had recorded that despite a search of its records, it could not trace any document proving its earlier transmission to the Head Office. The court acknowledged the bank's handling showed administrative laxity and indecision, but held that such shortcomings could not create pension entitlement unavailable under the scheme.
Devi's case took an unusual turn when she filed an RTI application, revealing significant internal communication failures within the bank. According to The Times of India, the RTI revealed that the branch manager had asked the head office what to do in Devi's case, but due to reasons best known to the bank, Devi's form was not forwarded to Bank of Maharashtra's head office. The RTI also showed that the Bank of Maharashtra head office had asked the branch to obtain the requisite documents from Devi and re-submit the complete set of papers for consideration on merits. However, after that nothing happened and nobody knew why. As reported by The Times of India, Devi claimed that this showed the bank was aware of her family pension claim and couldn't just reject it now for missing documents or not submitting them. However, the High Court dismissed this argument, stating that the internal correspondence cannot be elevated into a definitive determination conferring a substantive right to family pension.
The case highlights that when pension or benefit schemes provide one-time options, keeping eligibility letters is insufficient. The prescribed form must be submitted within the deadline, and applicants should retain dated acknowledgments or other proof of submission. As reported by The Times of India, the court dismissed the writ petition, holding that Devi had failed to establish an enforceable legal right to the pension or family pension scheme. The ruling emphasizes that a claim to family pension must derive its legitimacy from the applicable scheme itself and not from procedural omissions in its implementation. The court stated that the beneficial character of a scheme does not mean the court can disregard its express terms, when the scheme clearly states the manner of exercise of the option, prescribes a cut-off date, and imposes attendant financial conditions. The ruling also emphasizes that family pension is a beneficial scheme but court cannot disregard the scheme's express terms and conditions.