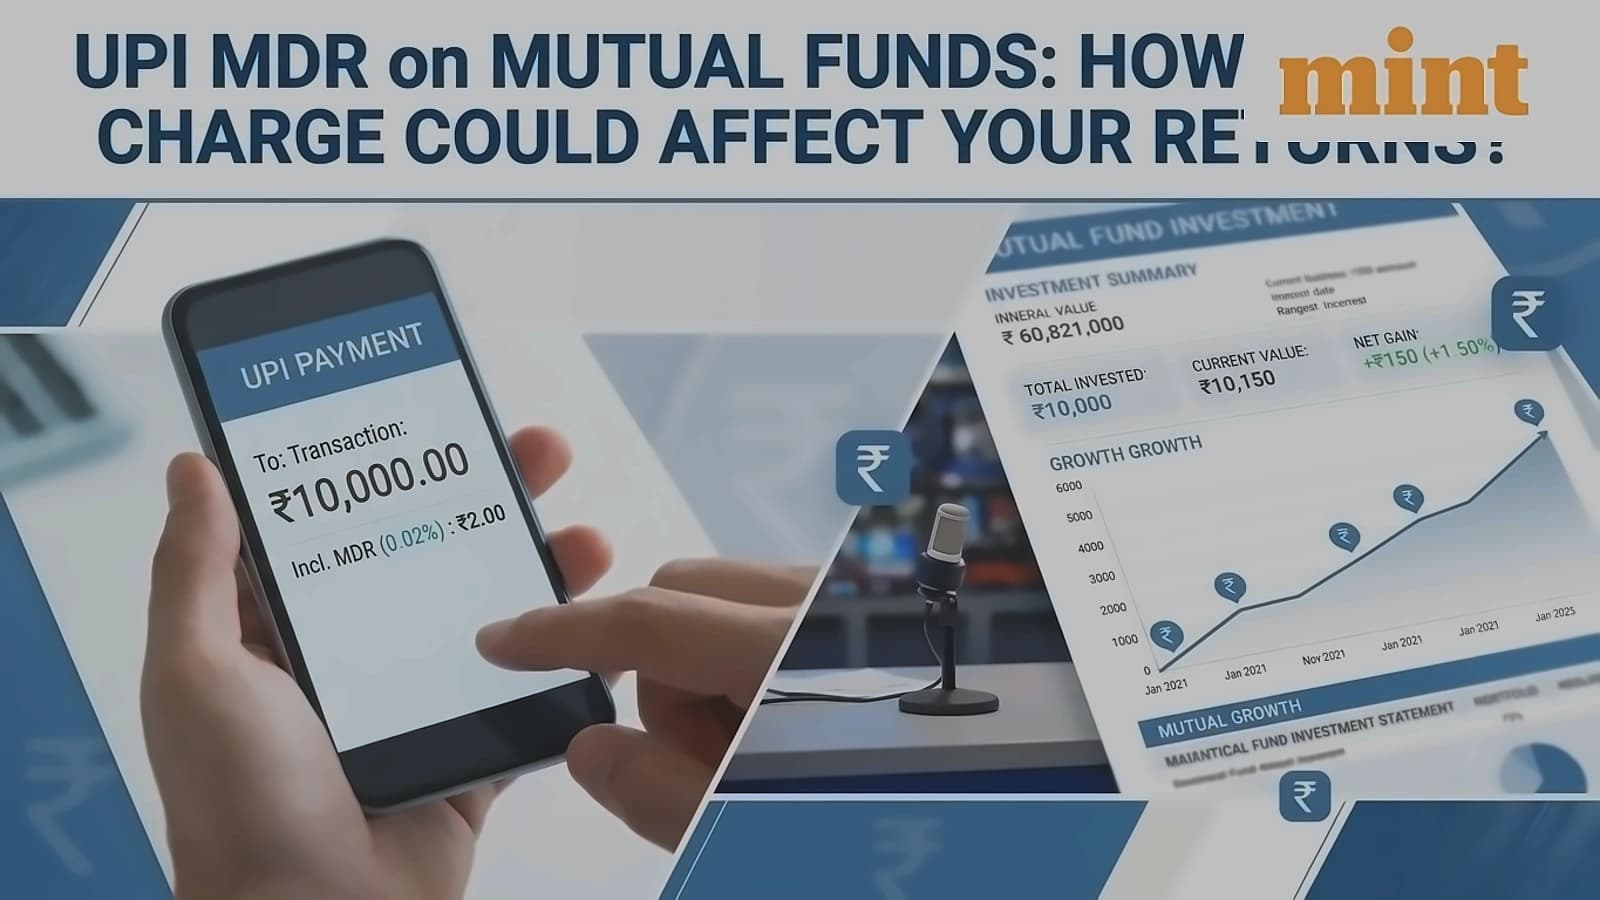
A 0.02% Merchant Discount Rate (MDR) will apply to capital-market transactions, including payments towards mutual funds, subject to a maximum charge of ₹300 per transaction. According to reports from Mint and The Economic Times, the charge is intended to be borne by the merchant and not the investor. However, experts explain that if the charge is passed on to investors, it could affect the amount invested and the final value of their investment. The new framework prioritizes RuPay credit cards for UPI transactions and aims to foster domestic competition while creating a sustainable revenue model.
For a ₹1 lakh one-time investment, the MDR could reduce the amount available for investment by ₹20, bringing the effective investment to ₹99,800. As reported by Mint, Debasish Mohanty from The Wealth Company Mutual Fund explained that over a 5-year period with 10% annual returns, the difference in returns would be minimal - ₹6,104 in Scenario 1 versus ₹6,105 in Scenario 2. For larger investments of ₹1 lakh, the difference would be slightly higher with estimated returns of ₹61,039 versus ₹61,051 respectively. The government emphasizes that most UPI payments will still be without charge for users, with transactions under ₹2,000 remaining free for small traders.
The treatment of MDR for SIP investments will depend on how the first instalment is processed. According to Mohanty's analysis reported by Mint, a one-time UPI payment made before the AutoPay mandate becomes operational may attract MDR, while subsequent instalments through UPI AutoPay would be exempt. However, if the first instalment itself is collected through the UPI AutoPay mandate, it should be exempt from MDR. The Economic Times reports that one-time investments in mutual funds and broker wallet replenishments will be subject to this fee, while recurring mutual fund SIPs via UPI AutoPay will remain exempt. The mutual fund industry is also expected to absorb much of the additional cost rather than pass it directly to investors, with fund houses potentially encouraging investors to use other payment methods like net banking or bank transfers for frequent one-time transactions.
The brokerage industry faces unique challenges as the MDR applies even when customers transfer funds without making trades. As reported by Firstpost, Tejas Khoday, co-founder and CEO of FYERS, explained that "When a customer adds funds into a trading account, it's not a purchase. It's simply a transfer of funds between 'their own' accounts." The concern is that unused funds may be returned to customers under SEBI's compulsory settlement rules, creating potential for repeated MDR charges on the same customer capital. Brokers argue that a payment into a trading account is different from a normal merchant payment, as the money remains the customer's and may never be used for trading. According to Kotak Securities MD & CEO Shripal Shah, brokers would even incur charges when traders or investors top up their broking wallet using UPI, without actually trading with the balance. The industry has sought a much lower transaction-level cap of ₹2 to ₹5 and a separate higher threshold before MDR becomes applicable to capital-market payments.
The MDR will not have any impact on the expense ratio of the fund as the cost will not be borne at the fund level, affecting other investors investing through non-UPI routes. As reported by Mint, Eshaan Lazarus from 021 Trade explained that the expense ratio covers recurring scheme expenses and is reflected in the NAV, and charging it to scheme assets would require a permissible basis under SEBI's expense rules. Harsh Vardhan Dawar from Wealth Cafe noted that AMFI is expected to roll out how the MDR charges will be accounted for.