A recent case study highlights the critical importance of understanding travel insurance policy exclusions. According to reports from Mint, a traveler's comprehensive insurance policy proved worthless when faced with real-world travel disruptions. The policyholder's daughter experienced a four-hour flight delay that caused her to miss her connecting flight, resulting in 12 hours of total delay and a twisted ankle injury during terminal transfers. Despite having a top-end travel insurance policy with extensive coverage, no claims were successful due to specific policy exclusions.
The case revealed several critical coverage gaps that could affect most travelers. As reported by Mint, the missed connection benefit was limited to six-hour layovers while the actual layover was only two hours. The policy excluded medical treatment in India despite covering European treatment, and baggage delays on return legs to India were specifically excluded. The insurance also capped two-wheeler injury costs and excluded valuable items in checked luggage unless receipts were available, creating significant coverage gaps for common travel scenarios.
Industry data reveals concerning claim settlement patterns in the travel insurance sector. According to Mint's analysis of 10 popular individual travel plans, average claim rejection rates reached approximately 45%. Individual insurer rejection rates ranged from 20% to 75%, with some insurers rejecting more claims than they paid. This high rejection rate is attributed to the lack of standardization in travel insurance contracts compared to health insurance, creating significant variation in policy interpretations and claim outcomes.
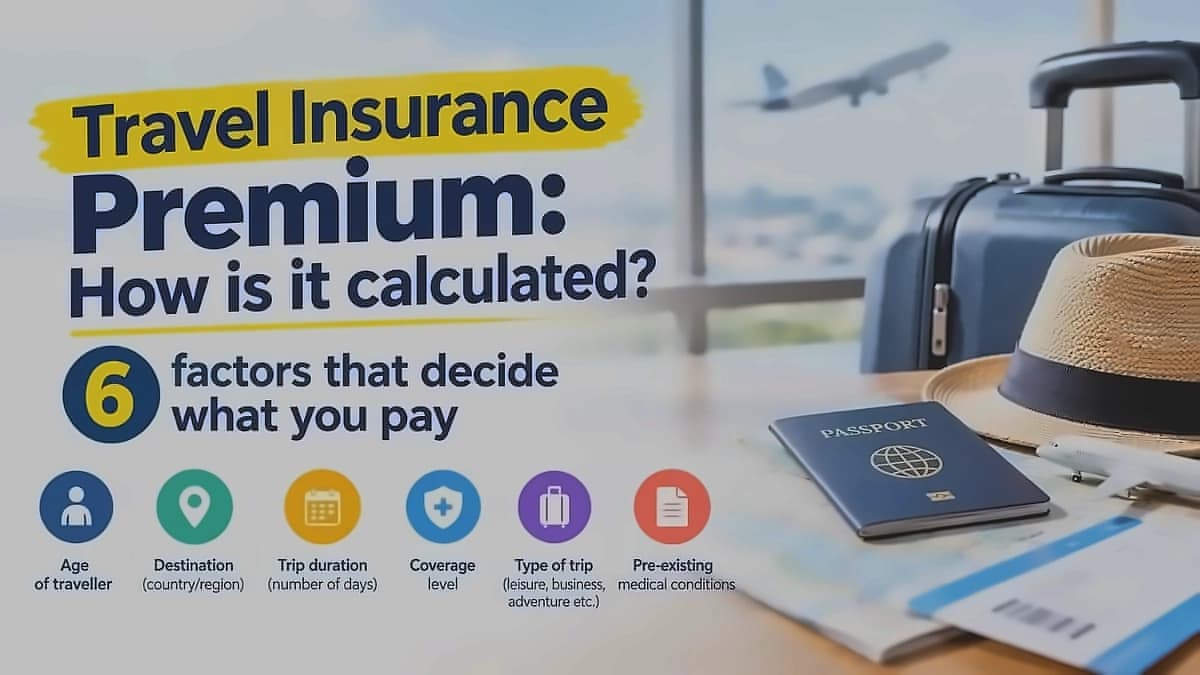
Industry experts recommend five key considerations when selecting travel insurance. As reported by Mint, travelers should first identify their specific travel plans, including layover durations and destination requirements. Pre-existing health conditions should be prioritized, as many policies exclude this coverage despite being critical for some travelers. Policy duration should extend beyond return dates to ensure coverage for delayed trips, and NL-47 public disclosures should be reviewed for claim settlement rates and grievance handling. Most importantly, policy wording should be thoroughly reviewed to understand specific exclusions and coverage limitations before purchase.