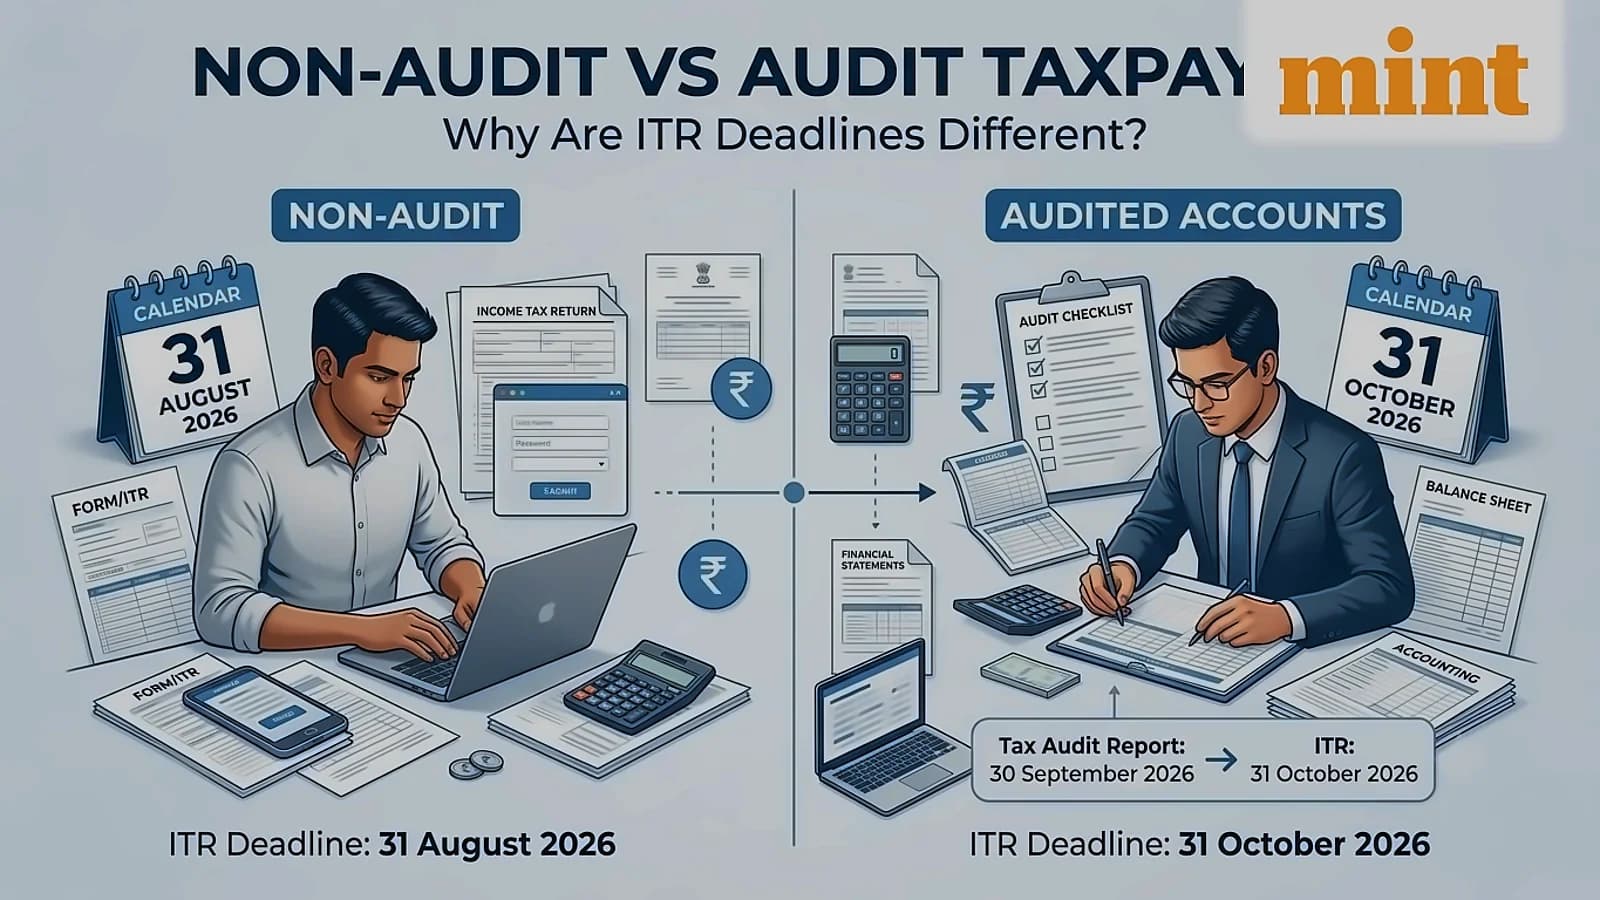
Taxpayers with business or professional incomes face different income tax return (ITR) deadlines depending on whether their accounts are subject to tax audit. According to reports from Mint, taxpayers not requiring an audit had to file their return by August 31, 2026, while those whose accounts need to be audited get additional time to complete the process. The tax audit report is due by September 30, 2026, with the ITR filing deadline for such taxpayers set for October 31, 2026. However, the Chartered Accountants Association, Jalandhar has submitted a representation to the Finance Minister seeking extension of these due dates, citing compressed timelines and increased compliance burden. As per Mint, ITR-3 applies to individuals and HUFs with business or professional income, while ITR-4 applies to eligible presumptive taxation taxpayers. For taxpayers subject to transfer-pricing reporting under Section 92E, the ITR filing deadline is November 30, 2026, with the audit report deadline remaining October 31, 2026.
The requirement for filing a tax audit report is based on the nature of the activity and turnover or gross receipts. As reported by Mint, for businesses, a tax audit is generally required if profits exceed ₹1 crore in a relevant financial year. However, this limit is raised to ₹10 crore where the cash receipts and cash payments levels are less than 5% of total receipts and payments, respectively. For professionals, the general threshold for requiring a tax audit is ₹50 lakh in gross receipts. This provision also applies to taxpayers opting out of presumptive taxation schemes such as Sections 44AD, 44ADA, 44AE, 44BB, and 44BBB. According to TaxBuddy, the ₹10 crore enhanced threshold applies only when both cash receipts and payments do not exceed 5% of aggregate receipts and payments during the tax year, and both conditions must be satisfied independently.
The audit process requires taxpayers to provide comprehensive documentation to their Chartered Accountants for review and verification. As explained by Mint, taxpayers should close and reconcile their accounts and share complete records with their CA, who will review the books, check tax disclosures, and prepare the audit report and Form 3CD. The required documentation includes final trial balance, P&L account, balance sheet, ledgers, bank statements, sales and purchase records, GST returns and reconciliations, TDS/TCS details, fixed assets and depreciation, loans and interest, investments, related-party transactions, expenses with special tax relevance, and other details required for claims. According to Mint, the audit report must be uploaded to the income tax portal by September 30, after which taxpayers prepare and reconcile their ITR with audited figures, pay any dues, and file and verify the return. Taxpayers should give their CAs sufficient time to review records and avoid a last-minute rush, as recommended by Mint.
Once the audit report is filed, taxpayers must complete their ITR filing within the applicable deadline. As reported by Mint, taxpayers should compare the ITR with the final audited financial statements and audit report, verifying turnover/revenue, business income, expenses, depreciation, tax deductions, carried-forward losses, TDS/TCS, advance tax and self-assessment tax. Relevant figures should be reconciled with AIS, Form 26AS and GST data. According to Mint, even if the audit deadline is met, ITR compliance is not yet complete - the return still needs to be filed within the due date applicable to the taxpayer. If taxpayers identify errors after filing the audit report, they should immediately notify their CA, who should submit a revised report through prescribed channels after which the ITR should be finalised with the audit report.
Failure to submit the tax audit report may attract significant penalties under the Income Tax Act. As reported by NDTV Profit, failure to submit the tax audit may attract a penalty under Section 271B of the Income Tax Act, with the fine equal to 0.5% of total sales, turnover or gross receipts, capped at a maximum of ₹1,50,000. However, no penalty is applicable if the taxpayer has established a reasonable cause for the failure under Section 273B. This penalty structure applies specifically to taxpayers whose accounts require audit under Section 44AB, making compliance essential for avoiding financial penalties.