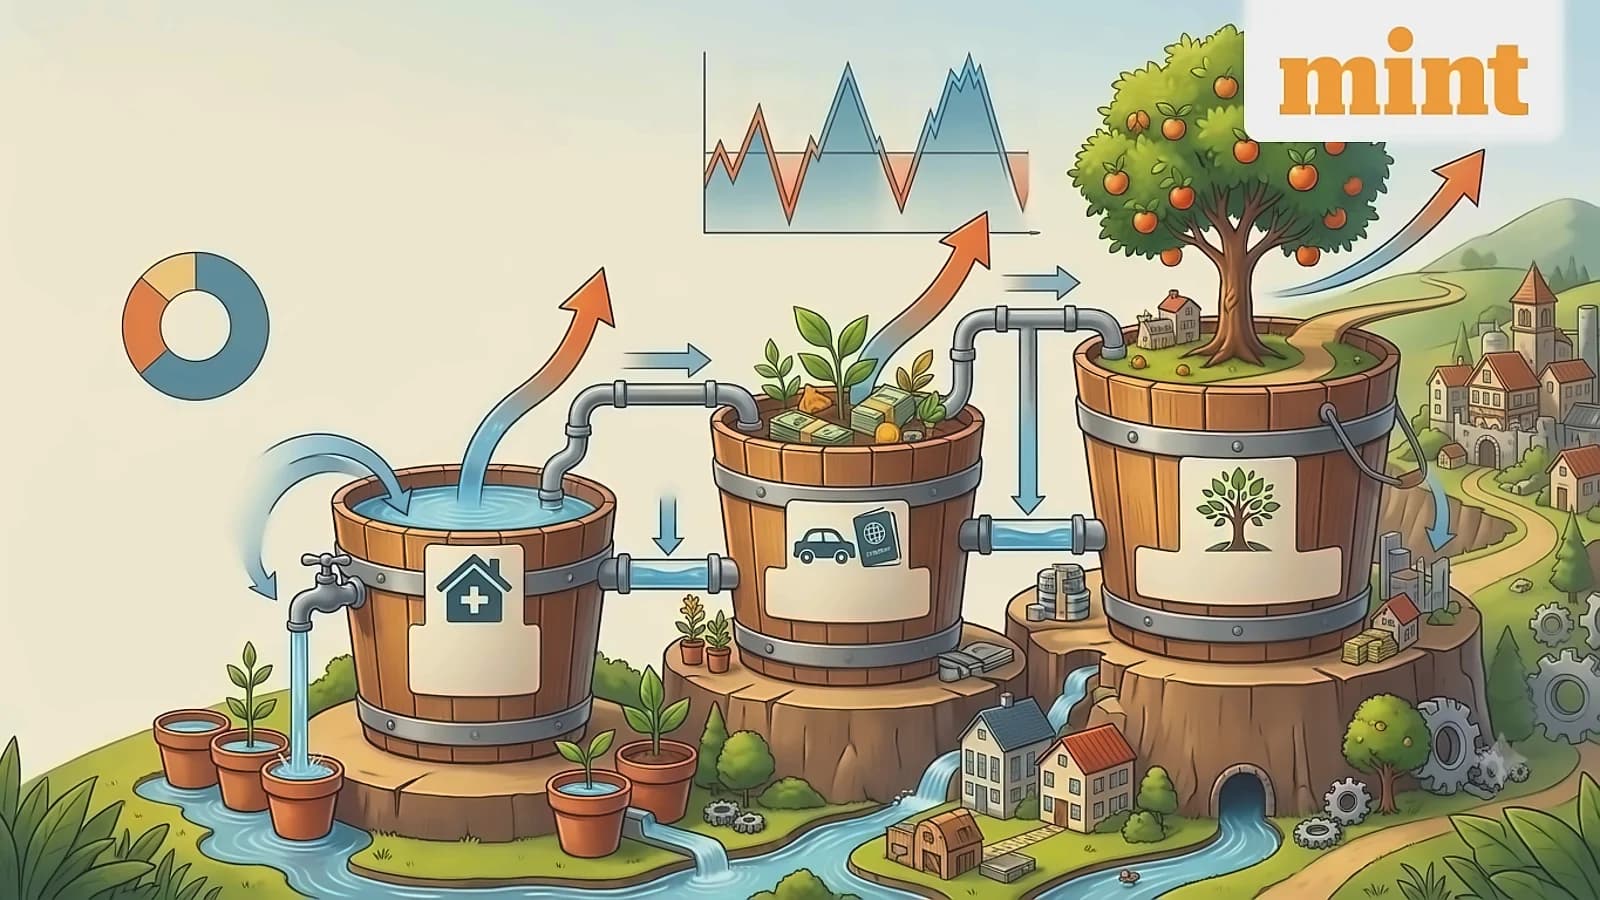
A retirement bucket strategy divides retirement investments into three broad buckets based on time horizon and purpose. According to Mint reports, the first bucket addresses immediate and essential expenses such as household costs, healthcare, and medical expenses where liquidity is critical. The second bucket handles medium-term lifestyle goals including travel, vehicle purchases, and home renovation. The third bucket focuses on long-term aspirational objectives such as building larger retirement corpus or creating generational wealth. As reported by Mint, this approach ensures near-term expenses are not dependent on long-term investment performance. According to Rajan Sarkar, Director & Unit Head, Anand Rathi Wealth Limited, the objective is to align the investment strategy with the investor's time horizon, liquidity requirements and risk appetite, ensuring that money required in the near term remains accessible while money meant for the distant future gets enough time to grow.
The appropriate allocation depends on factors including retirement income, corpus size, and risk profile. According to Mint reports, a retiree with regular pension covering most expenses may require smaller first bucket compared to someone relying primarily on investment withdrawals. For the near-term bucket, Mint suggests 60:40 equity to debt allocation with sufficient liquidity for immediate withdrawals. The medium-term bucket could have 70:30 equity to debt allocation, while the long-term bucket may target 80:20 allocation. Within equity components, diversified equity mutual funds are recommended, with debt including debt mutual funds, fixed deposits, and stable instruments. According to Sarkar, the strategy does not mean every retiree should maintain the same amount or investment mix in all three buckets, with appropriate allocation varying based on retirement income, corpus size, financial goals and risk profile.
Investors should factor inflation differently across buckets due to varying expense categories. As reported by Mint, healthcare costs have risen around 9-10% annually, requiring larger buffers for medical expenses. For medium-term goals like travel, investors can apply 7-8% inflation assumption. According to Sarkar, investors should not necessarily apply one inflation rate to the entire retirement corpus because different expenses can rise at different rates. The long-term bucket should focus on generating returns that beat inflation over extended periods rather than preserving current corpus value. According to Mint, retirees should calculate future expense costs rather than setting aside today's prices, with healthcare expenses requiring particular attention to inflation impact. Sarkar emphasizes that since retirement can last for two or three decades, inflation consideration is crucial for maintaining purchasing power.
The bucket strategy addresses sequence-of-returns risk by separating near-term withdrawals from long-term investments. According to Mint reports, retirees can shift one year of expected expenses from equity to debt before each year begins, with monthly expenses withdrawn through systematic withdrawal plans from debt portions. This approach reduces pressure to sell equity during market declines. Sarkar suggests that the regular-expense bucket could have a 60:40 allocation between equity and debt, with one year of expected expenses shifted from the equity portion into debt before the beginning of each year. If equity markets decline sharply, the retiree can continue meeting immediate expenses from the debt allocation instead of being forced to liquidate long-term growth assets at depressed prices. The long-term bucket remains invested in growth-oriented assets, allowing time for recovery when markets improve. As noted by Bulman Wealth Group, market downturns become more difficult when they coincide with large unexpected expenses, particularly healthcare costs that can increase later in retirement.
The strategy requires matching each retirement corpus portion with specific purpose and time horizon. According to Mint reports, investors should periodically review buckets as expenses, market conditions, income sources, and financial goals change. For higher tax bracket investors, Mint suggests considering arbitrage funds over debt mutual funds for tax efficiency, as these are taxed under equity capital gains rules and can offer debt-like liquidity and stability. The key objective ensures money required in near term remains accessible while distant future funds get sufficient growth time, making retirement withdrawals more structured and reducing need for rushed investment decisions during market downturns. As noted by Bulman Wealth Group, effective wealth management involves building a sequence-proof distribution plan that funds lifestyle without forcing portfolio sales during unfavorable market conditions. Sarkar emphasizes that the bucket strategy is not about following a fixed formula but about matching each portion of the retirement corpus with a specific purpose and time horizon, with regular review essential for adapting to changing circumstances.