Employees facing job loss can now withdraw up to 75% of their Provident Fund balance immediately after losing employment, while the remaining 25% can be withdrawn after 12 months of unemployment. According to reports from The Economic Times, these revised EPFO withdrawal rules provide flexibility for those who need immediate financial relief while maintaining long-term savings for future needs. The latest data shows that after 30 days out of work, EPFO rules permit an unemployed member to claim up to 75% non-refundable advance from their Employees' Provident Fund, with the remaining 25% available after 60 days of continuous unemployment.
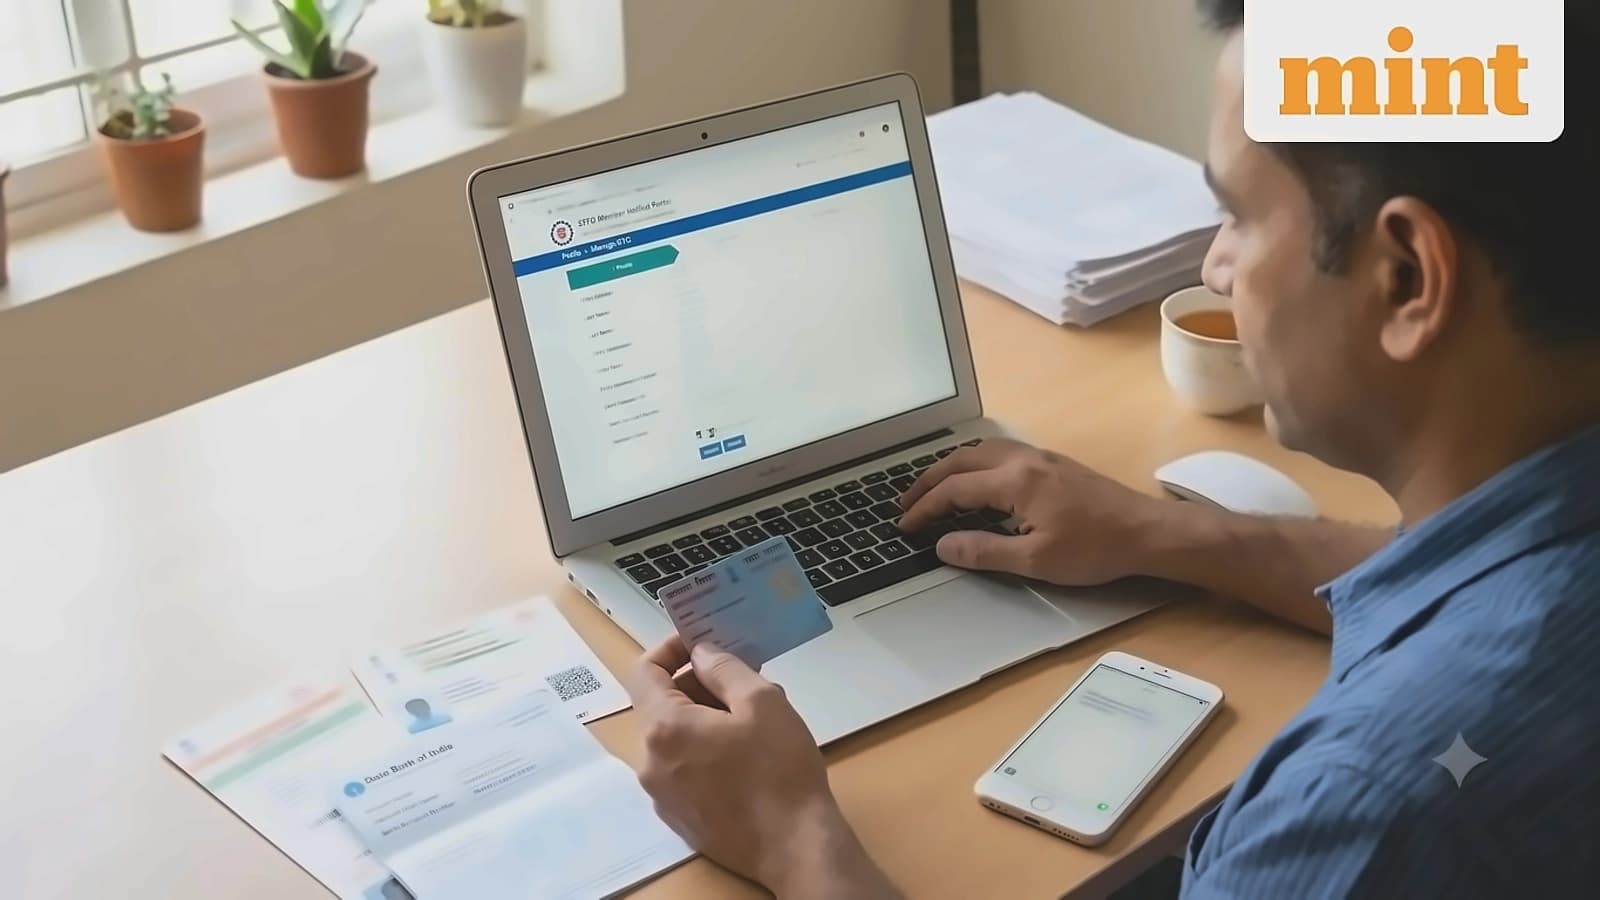
Before making any withdrawal, employees must ensure their UAN (Universal Account Number) is active and that Aadhaar, PAN and bank details are linked and verified. As reported by The Economic Times, these verified details can help avoid complications when filing withdrawal claims and streamline the approval process. The withdrawal claim can be submitted online through the EPFO portal once all account and KYC details are properly maintained. During unemployment, employees should collect essential documents from HR including official layoff/retrenchment notice, last 6 months' salary slips, latest Form 16 (Part A and Part B), Full and Final computation sheet, and group health insurance portability details to protect their financial position.
Employees can check their EPF balance through the EPFO Member Portal or the UMANG app to determine the amount available for withdrawal. According to reports from The Economic Times, maintaining active account status and verifying personal details becomes crucial for smooth withdrawal processing and avoiding potential tax implications. The online portal system allows for efficient claim submission once all prerequisites are met. However, employees must be aware that if their Corporate Salary Account and personal loan are held at the same bank, the lender's core banking software places a shadow Hold Balance or automated right-of-set-off flag on savings ledger, potentially sweeping all overdue EMIs when HR wires F&F severance into the account.
Withdrawing PF funds without understanding the rules could result in losing part of the savings to tax. As reported by The Economic Times, the Provident Fund is designed to support employees in the long run, making it important to consider the tax implications before accessing these funds. The structured withdrawal approach under the revised rules provides a balance between immediate financial needs and long-term retirement planning. However, employees should understand that the single largest lump sum they receive is the Full & Final (F&F) credit, which frequently totals ₹2,50,000 to ₹8,00,000 for mid-level managers, but this corpus must be managed carefully as it serves as both family's 6-month rent and medical lifeline while also being future settlement ammunition.