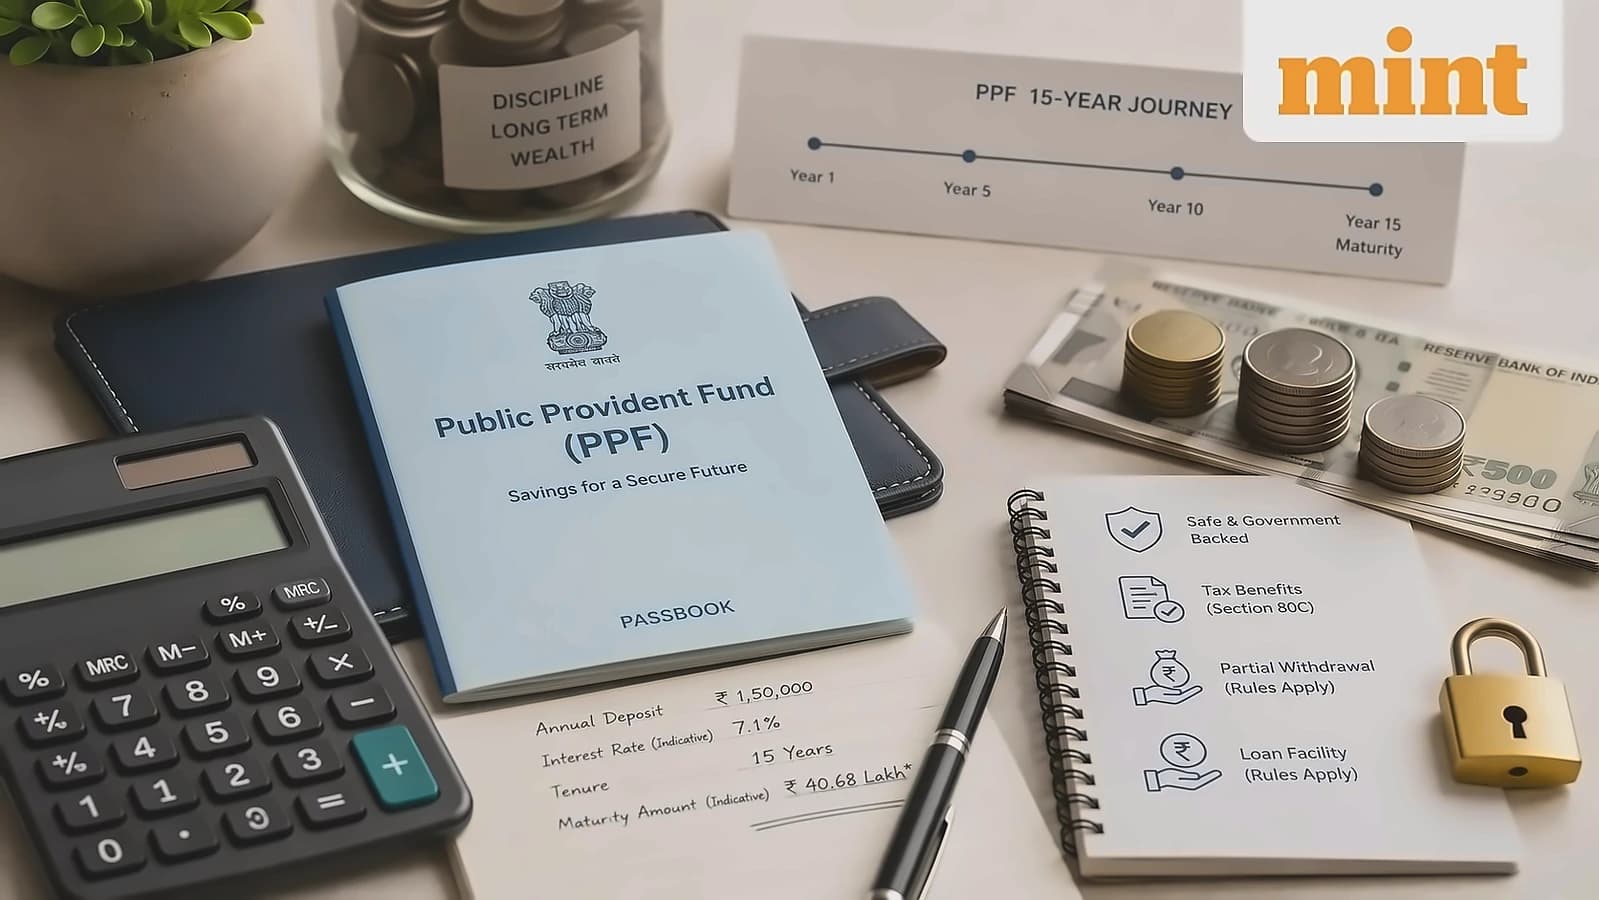
A Public Provident Fund (PPF) account has a 15-year maturity period that begins counting from the end of the financial year in which the account was opened, rather than the exact opening date. According to financial reports, if an account is opened on 10th October 2025, the relevant financial year ends on 31st March 2026, and the 15-year period is counted from that year-end, making the account mature on 1st April 2041. After maturity, investors can either withdraw their savings or continue using the account in blocks of five years through fresh contributions between ₹500 and ₹1.5 lakh per financial year. The completion of 15 years marks an important decision point for PPF savers, as investors reassess whether to withdraw the accumulated corpus, extend the account, or continue using it as part of their long-term retirement strategy.
To continue a PPF account after maturity, account holders must submit Form 4 to their bank or post office within one year from the date of maturity. As reported by financial experts, if no extension option is given within this one-year period, fresh deposits cannot be made into the account. Any deposit made after this period is treated as an irregular deposit and will be refunded by the bank without interest. The existing balance continues to earn interest at the applicable PPF rate until the account is closed, currently set at 7.1% per annum. If Form 4 is not submitted within the deadline, the account will continue in blocks of five years by default, but fresh contributions are not allowed. Investors choosing to continue the account may also consider whether they want to keep making contributions or maintain the account without fresh contributions, depending on their liquidity requirements and retirement timelines.
If a PPF maturity date falls on a weekend, bank holiday, or public holiday, the account continues to earn applicable interest for that day. According to financial guidance, the withdrawal or extension process can be completed on the next working day. Even if no action is taken immediately, investors have until one year from the date of maturity to extend their account with fresh contributions using Form 4. If the extension is missed, the account will be blocked for another five years, continuing to earn interest but preventing fresh contributions. Form 4 can be downloaded from bank websites or obtained physically at the branch or post office where the PPF account is maintained. The decision after 15 years is not limited to whether to withdraw the corpus, as investors are also considering whether continuing the account can fit into their broader financial objectives.
PPF is classified as an EEE (Exempt-Exempt-Exempt) investment, offering tax benefits at three stages. As reported by financial experts, contributions to PPF are eligible for tax deductions under applicable rules, and the interest earned on the account is tax-free. The maturity amount, including both principal and accumulated interest, is also exempt from tax, making PPF a tax-efficient long-term savings option for building assured returns with government backing. Once the 15-year period ends, investors have three main options: withdraw the entire amount, close the account, or extend it for another five years. The decision should depend on immediate financial needs, with extending the account advisable for long-term returns, as PPF decisions are being evaluated alongside broader retirement-planning and small-savings considerations. The choice becomes particularly relevant for investors who value the PPF's sovereign-backed return profile and tax-free status while planning for retirement.