Transferring capital from an Non-Resident Ordinary (NRO) account to a Non-Resident External (NRE) account is fully permitted for Non-Resident Indians (NRIs), though it remains strictly regulated by tax and foreign exchange rules. According to reports from Mint, NRIs are allowed to shift funds from an NRO account into an NRE account, as well as transfer money seamlessly between separate NRE accounts. However, funds cannot be moved directly into an NRE account from a standard Indian resident savings account, creating clear operational distinctions between the two account types. The process involves logging into the Income Tax India website using PAN credentials, selecting 'E-file – Prepare and Submit Online Form (Other than ITR)', choosing Form 145 from available forms, and completing four sections (Part A, Part B, Part C and Part D) applicable to the transaction.
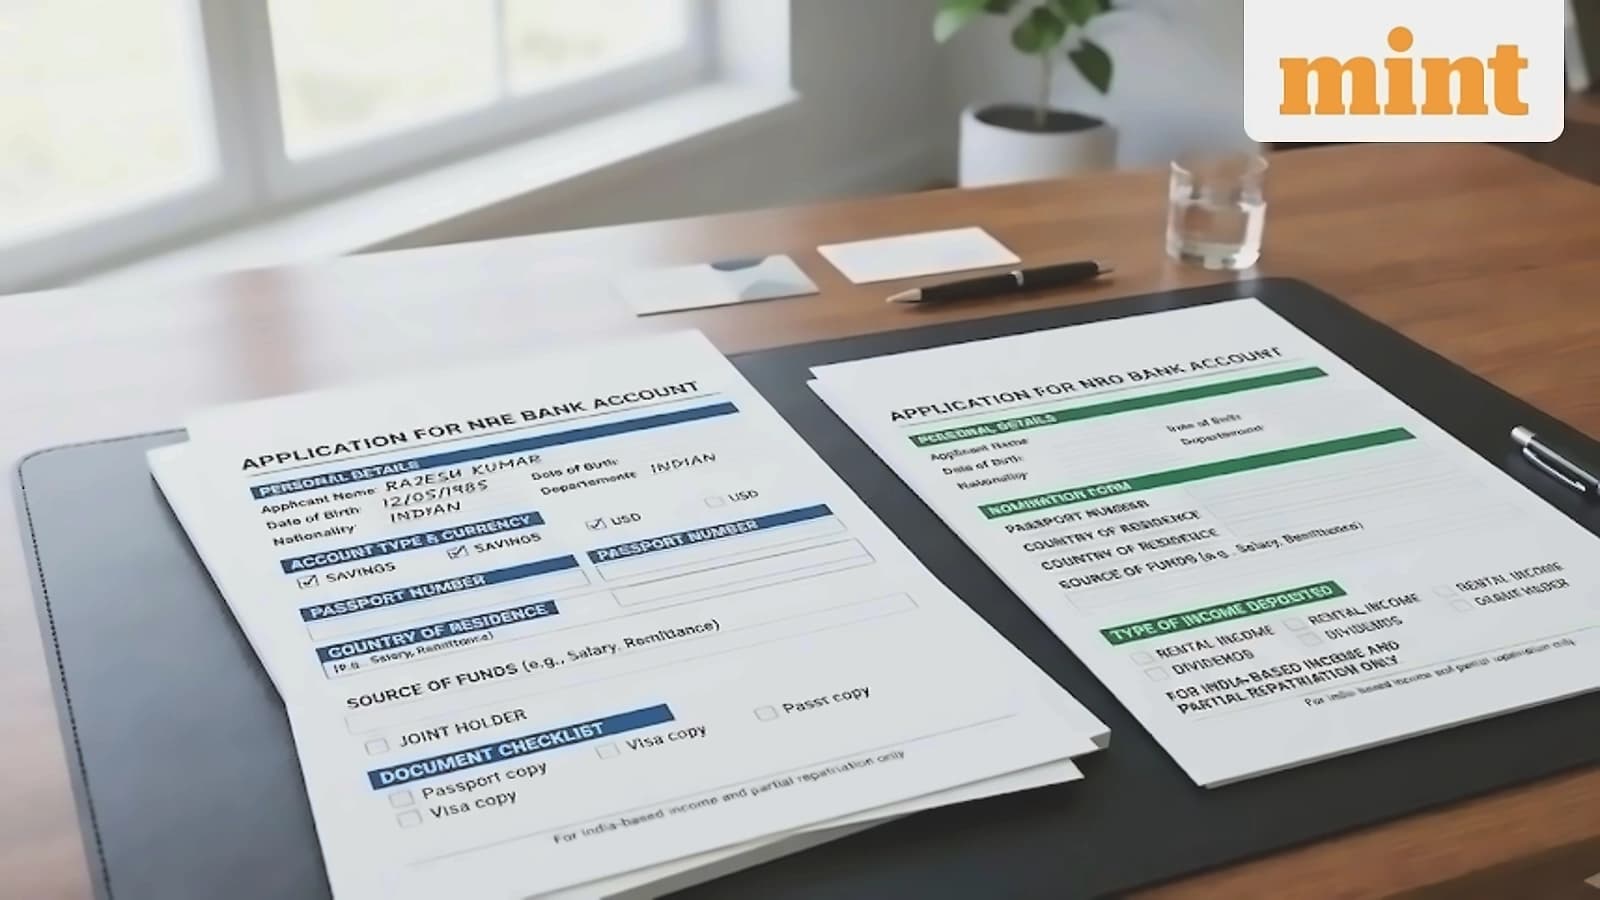
The primary distinction between NRO and NRE accounts lies in their tax treatment of interest earnings. As reported by Mint, interest earned on NRO deposits is subject to tax deduction at source (TDS) in India, while interest earned on NRE deposits is exempt from income tax in India for account holders who qualify as NRIs under FEMA rules. This tax advantage makes NRE accounts particularly attractive for NRIs seeking to optimize their tax liability on foreign earnings. Additionally, funds maintained in an NRE account can generally be fully repatriated outside India, while NRO balances are subject to a repatriation limit of up to $1 million per financial year. The tax advantage extends to overseas earnings deposited in NRE accounts, which can be transferred abroad without any upper limit after paying applicable taxes.
According to the latest RBI framework, NRIs can transfer eligible funds from an NRO account to an NRE account up to the overall $1 million limit per financial year (April-March). The Reserve Bank of India permits this transfer within the USD 1 million annual limit, applicable taxes and documentation requirements. Capital income, which can include proceeds from the sale of property, investments or accumulated savings, is subject to the $1 million annual repatriation limit across all NRO accounts held by the NRI during a financial year. Foreign earnings can be deposited into an NRE account, while an NRO account can receive both income earned in India and certain overseas funds. Any transfer from an NRO account to an NRE account also counts towards this USD 1 million annual limit, requiring careful planning for NRIs with substantial overseas investments or property sales.
NRIs transferring funds from an NRO account to an NRE account gain several significant advantages beyond tax benefits. As reported by Mint, interest earned on NRE deposits is fully exempt from tax in India as long as the account holder qualifies as an NRI under FEMA rules. Additionally, NRE accounts offer attractive interest rates with up to 4% per annum for end-of-day balances of ₹50 lakh or more, and 3.5% per annum for balances below ₹50 lakh, according to HDFC Bank. The most compelling benefit is full repatriability without any annual limit or special government permission requirements, unlike NRO balances which are subject to the $1 million per financial year restriction. Money remitted to an NRE account is converted into Indian rupees, allowing NRIs to hold and use their overseas earnings in India for permitted investments and expenses.
NRIs transferring funds from an NRO account must maintain proper documentation to establish fund source and demonstrate tax compliance. As reported by Mint, Form 145 is an online declaration submitted to the Income Tax Department confirming that applicable taxes have been deducted or paid. Under the new framework, Form 145 has different sections depending on whether the remittance is taxable and the threshold involved. If a taxable remittance exceeds ₹5 lakh and the applicable conditions are met, a Chartered Accountant's certificate in Form 146 may also be required. Other required documents include proof establishing the source of funds and a declaration confirming compliance with the Foreign Exchange Management Act (FEMA) provisions. The compliance process involves logging into the Income Tax India website at www.incometaxindiaefiling.gov.in, completing the online form in four parts (Part A, Part B, Part C and Part D), and submitting the form in duplicate to the bank along with supporting documents.