According to government regulations, full withdrawal of the corpus is permitted when the corpus is ₹5 lakh or less for normal exits. This covers exits at 60 or beyond, or retirement under applicable service rules. The guidelines list this threshold for both government and non-government subscribers. For corpus exceeding ₹5 lakh, at least 40% must be purchased under an annuity with the remaining 60% available as lump sum. For example, someone making a normal exit with ₹10 lakh corpus must purchase at least ₹4 lakh for annuity, allowing up to ₹6 lakh upfront withdrawal. The PFRDA amended these rules in June 2025, raising the threshold from ₹5 lakh to ₹8 lakh for full withdrawal after 15 years or at age 60. For corpus between ₹8-12 lakh, subscribers must purchase ₹6 lakh annuity with the balance received tax-free, while corpus exceeding ₹12 lakh requires mandatory annuity purchase of 20% of the corpus.
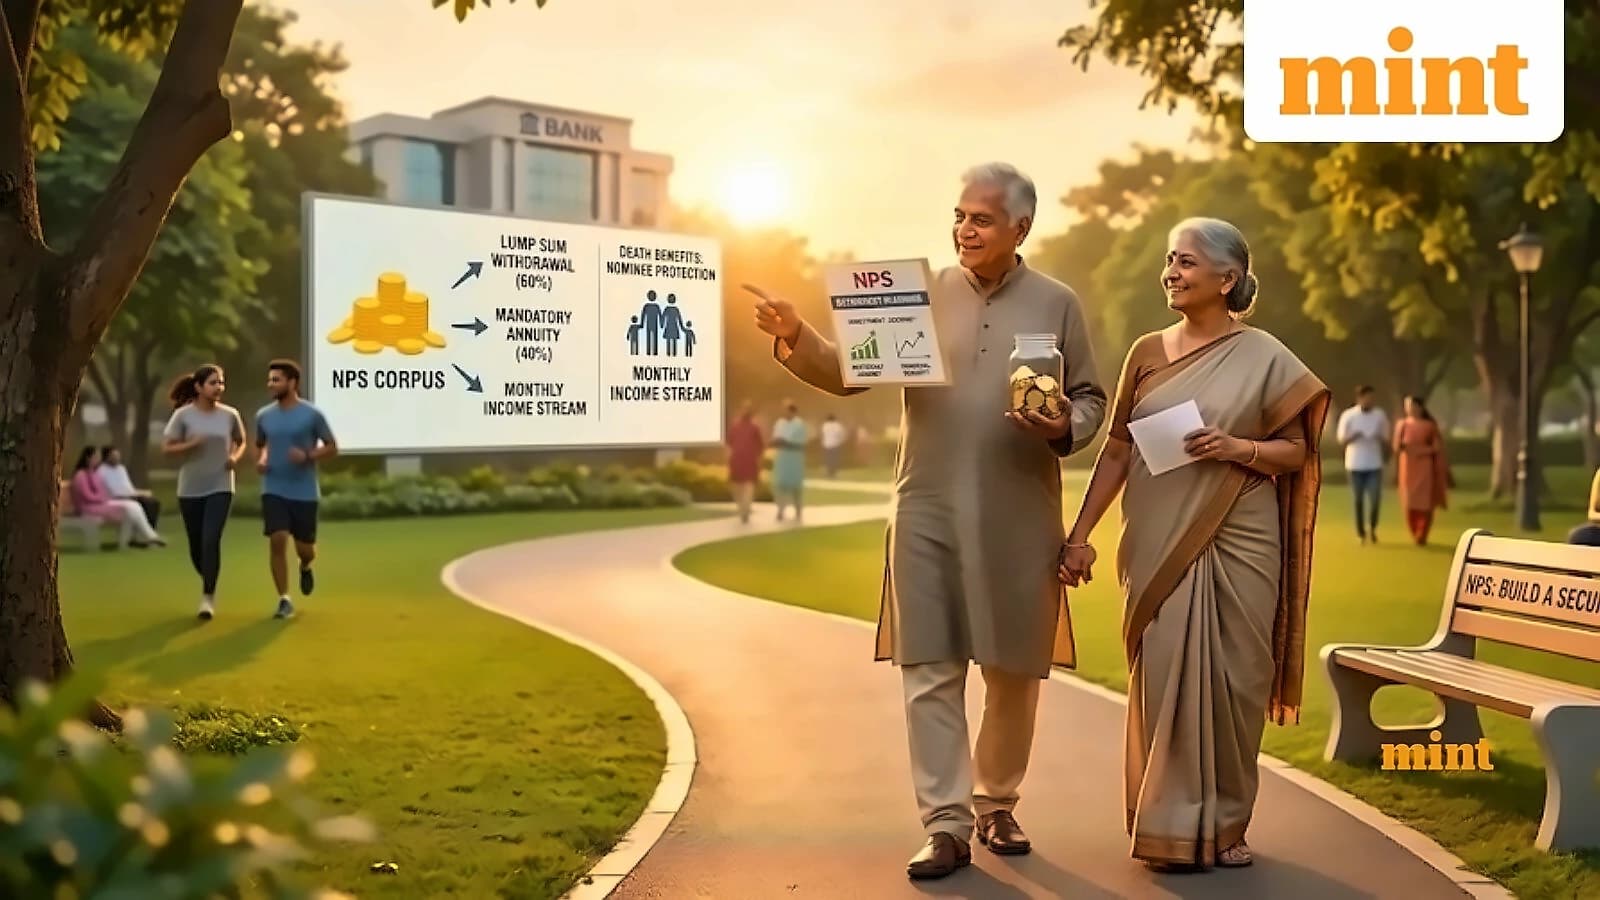
Premature exits before 60 or normal retirement have stricter withdrawal limits. Full withdrawal is allowed up to ₹2.5 lakh before this threshold, above which at least 80% must purchase an annuity with only the remaining 20% as lump sum. For instance, an early exit with ₹5 lakh corpus requires ₹4 lakh towards annuity, limiting maximum upfront withdrawal to ₹1 lakh. Government guidelines specify a mandatory 5-year membership for All Citizens subscribers seeking premature exit.
Death benefits differ significantly between government and non-government subscribers. For non-government subscribers, the entire corpus goes to nominees or legal heirs after death, regardless of age at death. Nominees may choose an annuity instead. For government subscribers who die before normal exit, full withdrawal is allowed up to ₹5 lakh. Above ₹5 lakh, at least 80% generally funds the prescribed annuity for dependents with the remaining 20% to nominees or legal heirs. An exception applies when no dependent spouse, mother or father survives, where the 80% portion goes to surviving children or legal heirs.
Despite PFRDA rule changes allowing up to 80% withdrawal in certain cases, tax exemption remains limited to only 60% of the corpus under Income Tax Act provisions. As per Section 10(12A) of the Income Tax Act, 1961 and Item no. 6 of Schedule III read with Section 11 of the Income Tax Act, 2025, which came into effect from April 1, 2026, subscribers receive tax-free treatment on 60% of the accumulated corpus. This exemption applies regardless of whether the withdrawal is full or partial, depending on the balance in the Tier I account at exit. Subscribers whose corpus exceeds ₹8 lakh but does not reach ₹12 lakh can still withdraw up to 80%, but tax applies to the remaining 40% despite the PFRDA rule allowing full withdrawal.