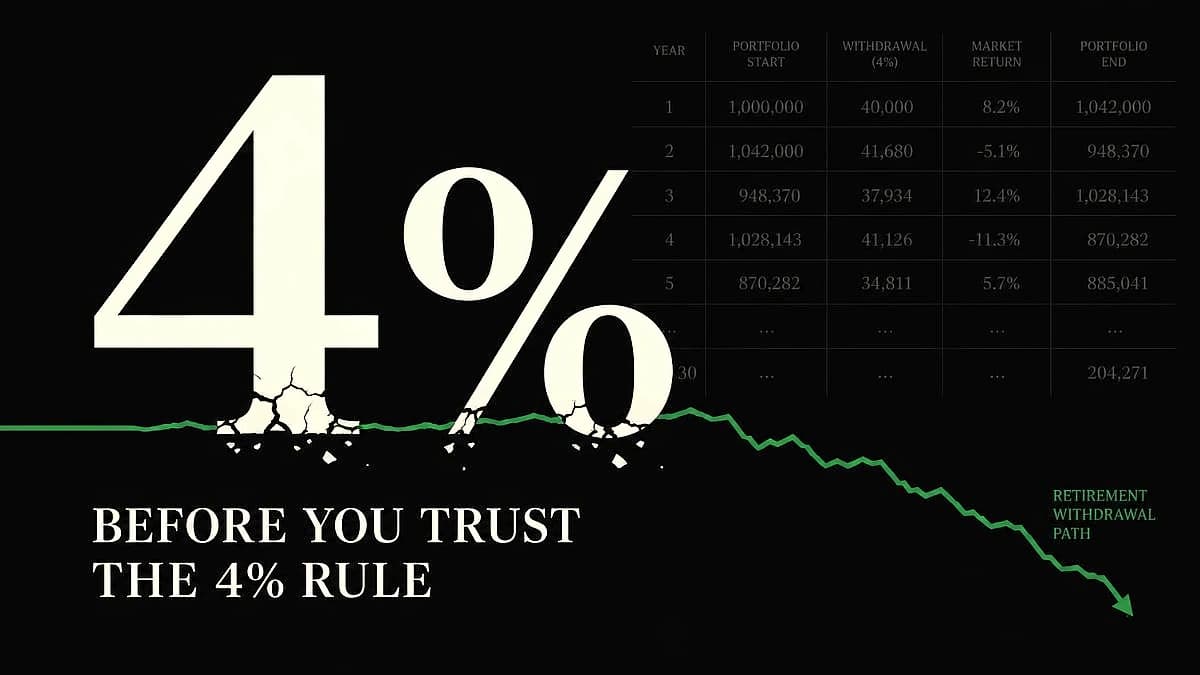
Financial planning calculations reveal that ₹4.62 crore may be required to generate ₹15 lakh annually at a 3.25% withdrawal rate, according to financial planner Niraj Dugar. This figure represents a significant increase from the traditional ₹1 crore benchmark and is nearly ₹90 lakh higher than the ₹3.75 crore corpus needed if a retiree assumes a 4% annual withdrawal rate. The updated requirements highlight why retirement planning must account for India-specific conditions and inflation adjustments, as the traditional ₹1 crore milestone that once symbolized financial security for middle-class Indians is no longer sufficient for modern retirement needs.
The analysis reveals substantial differences in corpus longevity based on withdrawal levels. ₹75,000 monthly withdrawals would require ₹9 lakh annually, reducing the corpus lifespan to approximately 11 years. At this rate, someone starting at age 60 could exhaust the corpus around age 71. Most significantly, ₹1 lakh monthly withdrawals would consume the entire corpus in 8 years and 4 months, meaning a retiree starting at 60 could deplete the fund before reaching age 69. Dugar's framework shows that at a 3% withdrawal rate, the required corpus rises further to ₹5 crore, demonstrating how sensitive retirement planning is to assumed withdrawal rates. With people potentially spending 25 to 35 years in retirement due to longer lifespans, these withdrawal rates can significantly impact corpus longevity.
As reported by financial experts, these calculations represent simplified scenarios without considering investment returns, taxes, or unexpected expenses. Real-world retirement money is typically diversified across fixed deposits, government-backed schemes, debt investments, and mutual funds, which can extend corpus longevity. However, expenses also increase over time due to inflation, with household spending today potentially requiring much more after 10 years. Healthcare costs can be particularly concerning, as one large hospital bill or medical expenses can significantly impact retirement planning. The changing landscape of retirement planning means that ₹1 crore may no longer be the ultimate financial milestone it once was, with inflation pushing up everyday expenses and requiring larger corpus amounts for sustained retirement income.
Financial advisors emphasize that ₹4.62 crore is not universally sufficient for retirement, as the same amount can last more than 16 years for one family and less than nine years for another. The updated calculations suggest retirees should calculate basic household expenses, medical needs, and regular commitments before determining monthly withdrawal amounts. Maintaining a separate emergency fund instead of depleting the main retirement corpus for unexpected expenses can help preserve long-term financial security, particularly given the higher withdrawal rates that are becoming more common in retirement planning frameworks. A disciplined monthly SIP strategy can still help build the required corpus, though the maths clearly show that ₹1 crore is no longer the finish line for modern retirement planning in India.