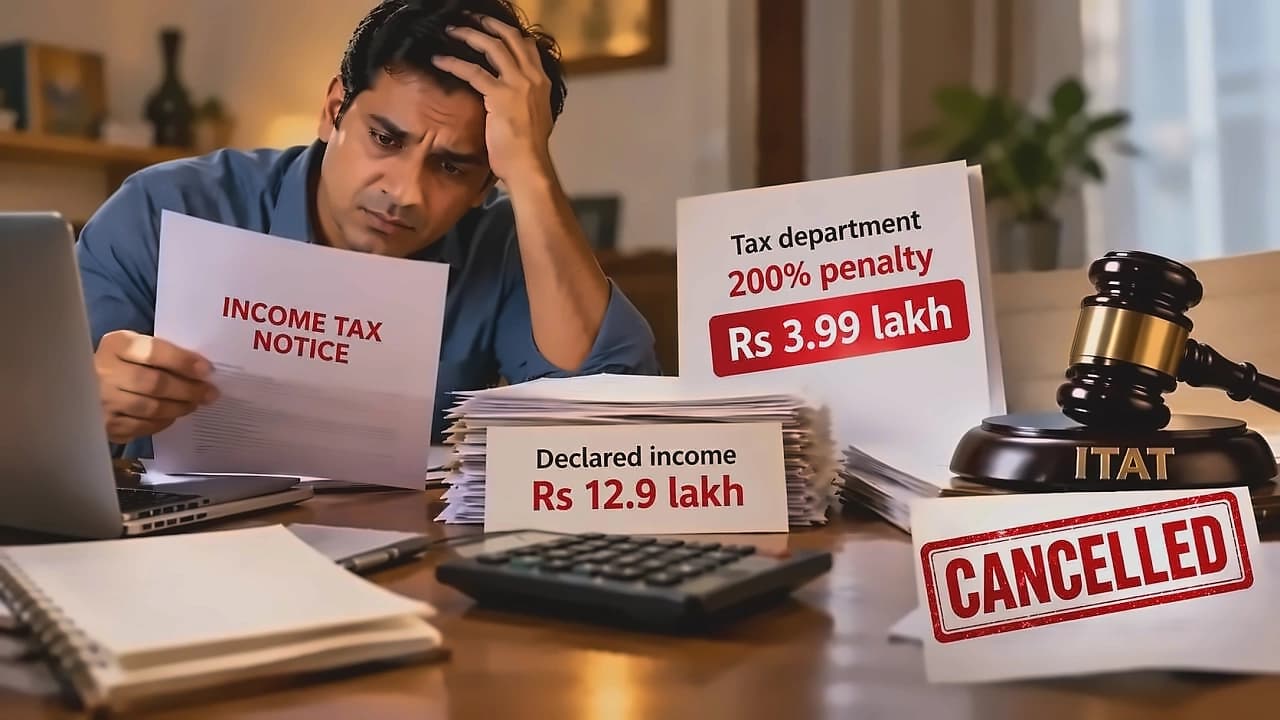
A Jaipur resident faced a significant penalty challenge after failing to file his income tax return (ITR) for assessment year 2018-19. According to reports from The Times of India, the taxpayer subsequently filed an ITR reporting ₹12.9 lakh income only after receiving a notice from the Income Tax Department. The Income Tax Assessing Officer (AO) took the view that this income would have remained outside the tax net had the department not issued the notice, leading to penalty proceedings under Section 270A of the Income Tax Act.
The penalty proceedings resulted in the full 200% penalty of ₹3.99 lakh being imposed on the taxable amount of approximately ₹1.99 lakh. As reported by The Times of India, this penalty applies under Section 270A of the Income Tax Act, which allows up to 200% of tax payable in cases involving misreporting of income. The Commissioner of Appeals (CIT(A)) also upheld the penalty, prompting the taxpayer to approach the Income Tax Appellate Tribunal (ITAT) in Jaipur.
On September 23, 2026, the ITAT Jaipur ruled in favor of the taxpayer and set aside the penalty. According to The Times of India, the key issue was the AO's decision to impose the higher 200% penalty for misreporting without specifying which particular clause of Section 270A(9) the taxpayer had allegedly violated. The tribunal found that neither the assessment order nor the penalty notice contained the necessary satisfaction identifying the alleged offence, leaving the taxpayer without knowledge of the precise charge to contest. The penalty was consequently quashed, providing full relief to the taxpayer.
The ITAT referred to the Rajasthan High Court's ruling in G.R. Infraprojects Limited vs. ACIT, decided on January 2, 2024, to support its conclusion. As reported by The Times of India, the tribunal emphasized that if a taxpayer is not told which specific legal provision forms the basis of the proposed penalty, the subsequent penalty proceedings are vitiated. The judgment noted that the man's declared income was accepted in the assessment without any addition or variation, with no revenue loss accruing to the department.
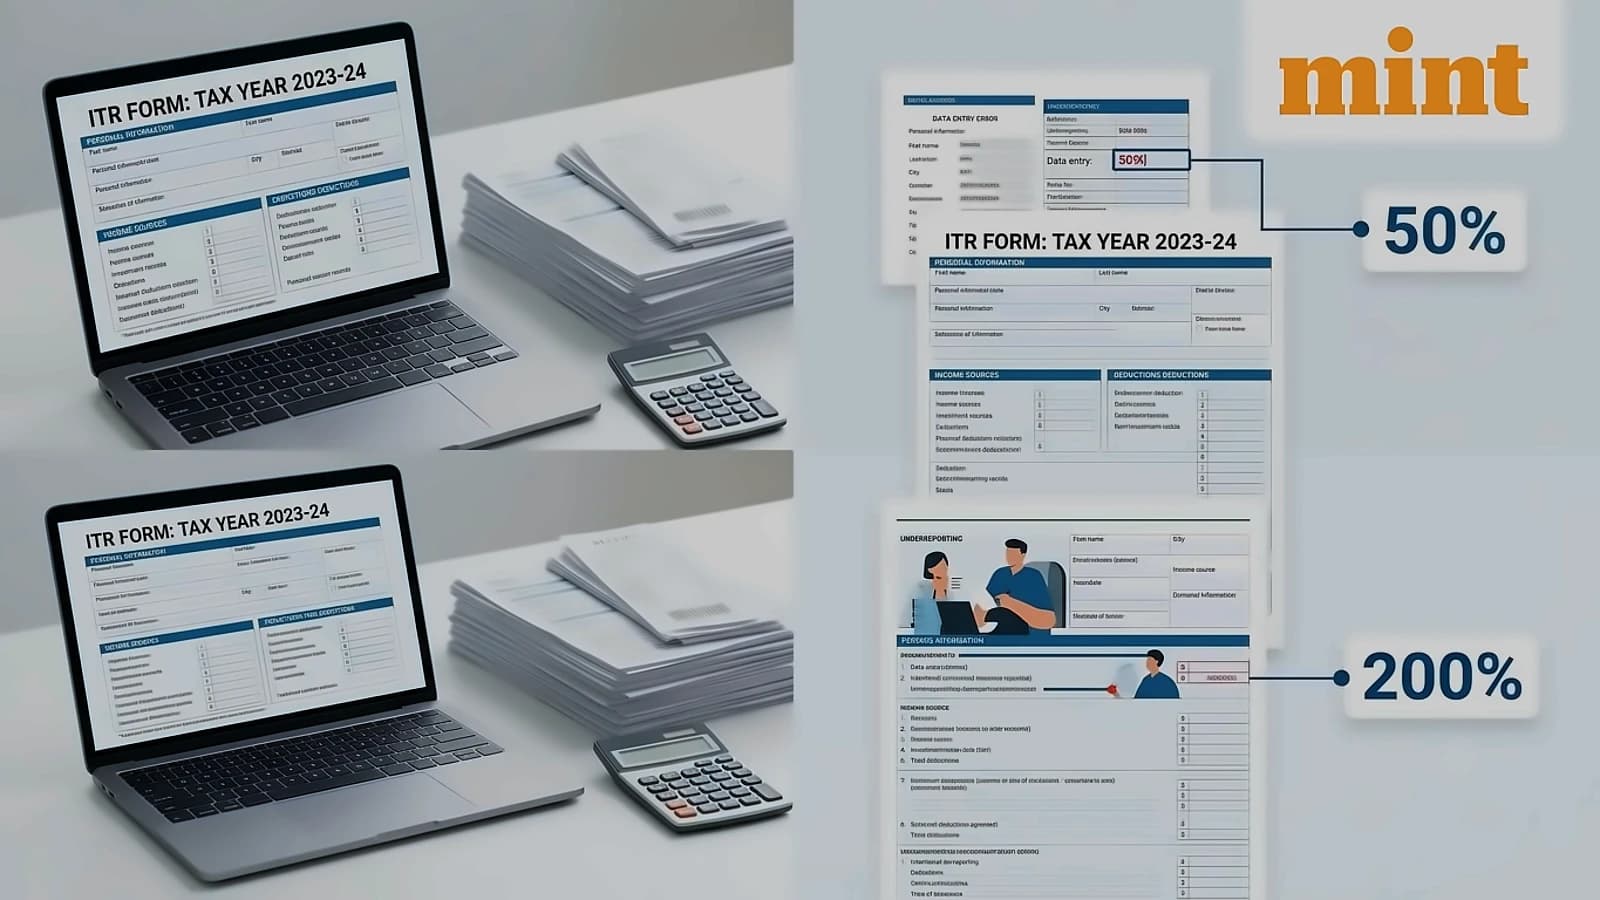
According to Pranshu G, Partner at Ashok Pranshu & Co, cited in The Times of India, the distinction between under-reporting and misreporting is crucial under Section 270A. While ordinary cases of under-reported income attract a 50% penalty, the higher 200% penalty applies only when under-reporting arises from specific forms of misreporting listed under Section 270A(9). These include suppressing facts, failing to record investments, making false entries, and not reporting specified transactions. The tribunal held that the AO's failure to record necessary satisfaction and specify the relevant Section 270A(9) provision undermined the validity of the entire penalty proceedings.