A landmark ruling by Mumbai's Income Tax Appellate Tribunal (ITAT) in 2025 has provided crucial relief for taxpayers facing penalties for refund interest reporting errors. According to the tribunal, when taxpayers have honestly disclosed refund interest income across both assessment years but incorrectly reported the year, this constitutes a classification error rather than deliberate concealment. This distinction is crucial, as Section 271(1)(c) penalties for concealment can range from 100% to 300% of the tax evaded, potentially reaching ₹3 lakh for honest mistakes. However, the tribunal emphasized that this protection applies only to cases where income was disclosed in both years and the taxpayer made corrections independently, with no evidence of deliberate tax evasion intent.
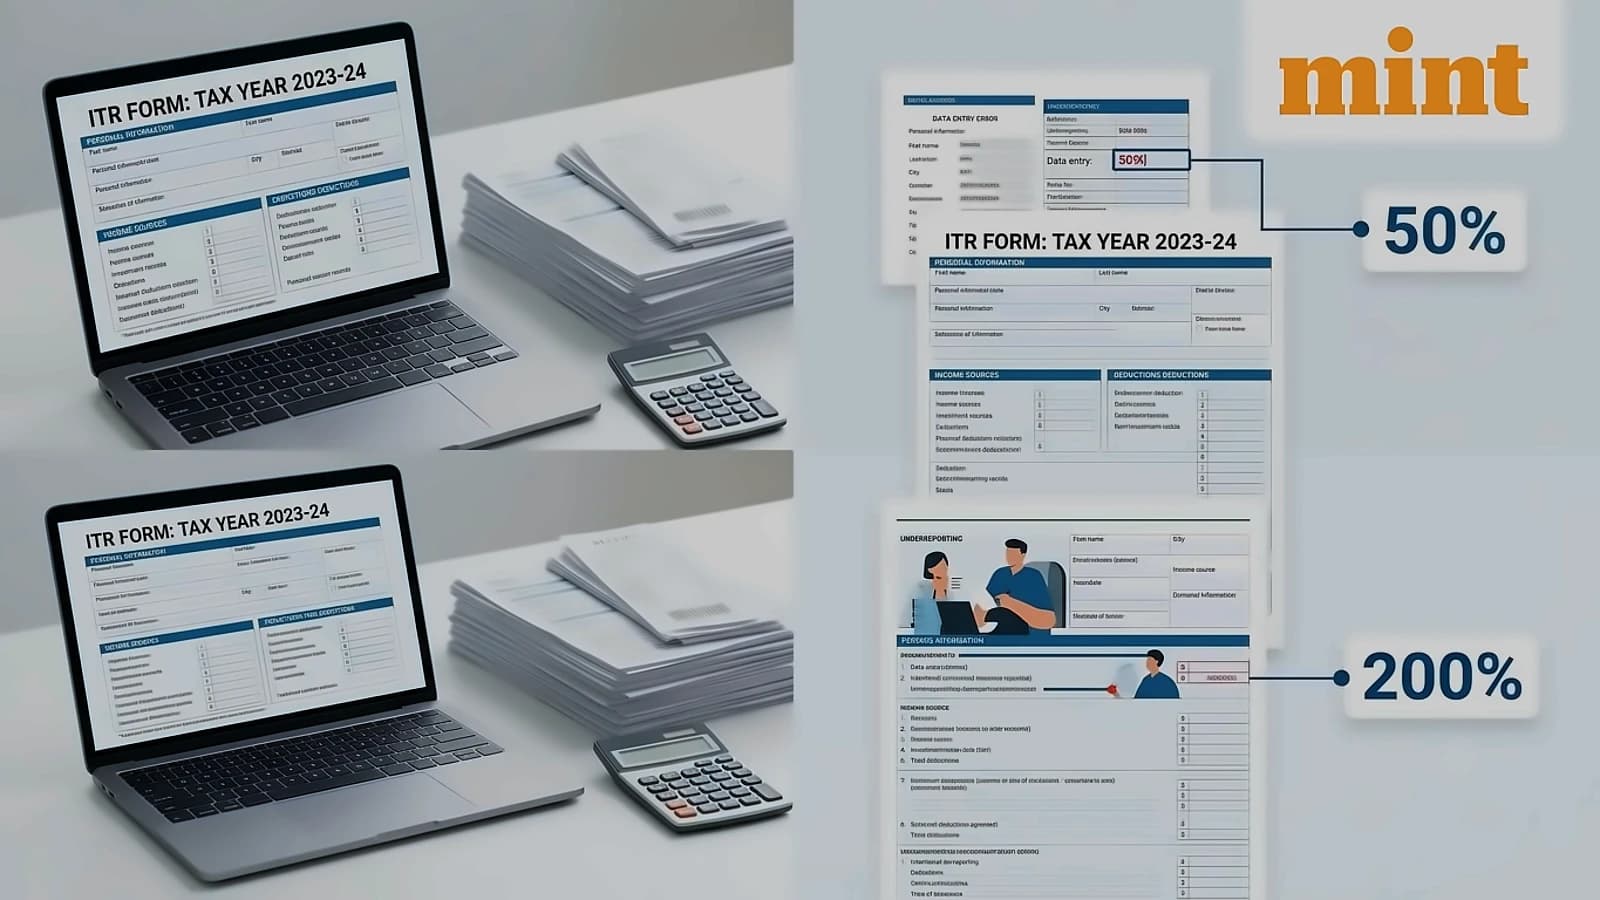
Under the Income-tax Act, 2025, which came into force on 1 April 2026, income tax return errors do not automatically attract a 200% penalty. According to reports from Mint, the penalty structure depends on the nature of the discrepancy and circumstances of the case. Under-reporting of income attracts a penalty of 50% of the tax payable on the under-reported income, while misreporting can result in a penalty of 200% of that tax. The tribunal's ruling specifically addresses the distinction between concealment (deliberate evasion) and classification errors (honest mistakes), with the latter receiving more lenient treatment.
As reported by Mint, under-reporting occurs when the income assessed is higher than the income reported in the return or previously assessed, or when an assessment reduces a reported loss or converts it into income. However, certain cases are excluded, such as when a taxpayer provides a genuine explanation and discloses all relevant facts to support it. Misreporting refers to specified cases of inaccurate or incomplete income reporting, including misrepresenting or suppressing facts, failing to record investments or income receipts in account books, claiming expenses without supporting evidence, and making false entries in the books of account. The tribunal's ruling clarifies that misreporting the year of refund interest constitutes a classification error rather than deliberate concealment.
To avoid potential penalties, taxpayers should follow a comprehensive compliance checklist before filing returns. As per the tribunal's guidance, AIS download from income.tax.gov.in is mandatory to verify refund interest details, while Form 26AS cross-check is essential for TDS deductions on interest. Taxpayers should calculate the exact refund interest amount, bank account details, and credit dates before filing returns. Additionally, Section 139(8A) provides an updated return option within 2 years that can help avoid penalties through self-disclosure, though this option carries additional tax liability of 25% to 50%. The tribunal's ruling emphasizes that honest disclosure matters - taxpayers who have never declared refund interest remain at risk for full penalties plus prosecution, making timely correction crucial for avoiding costly legal battles.