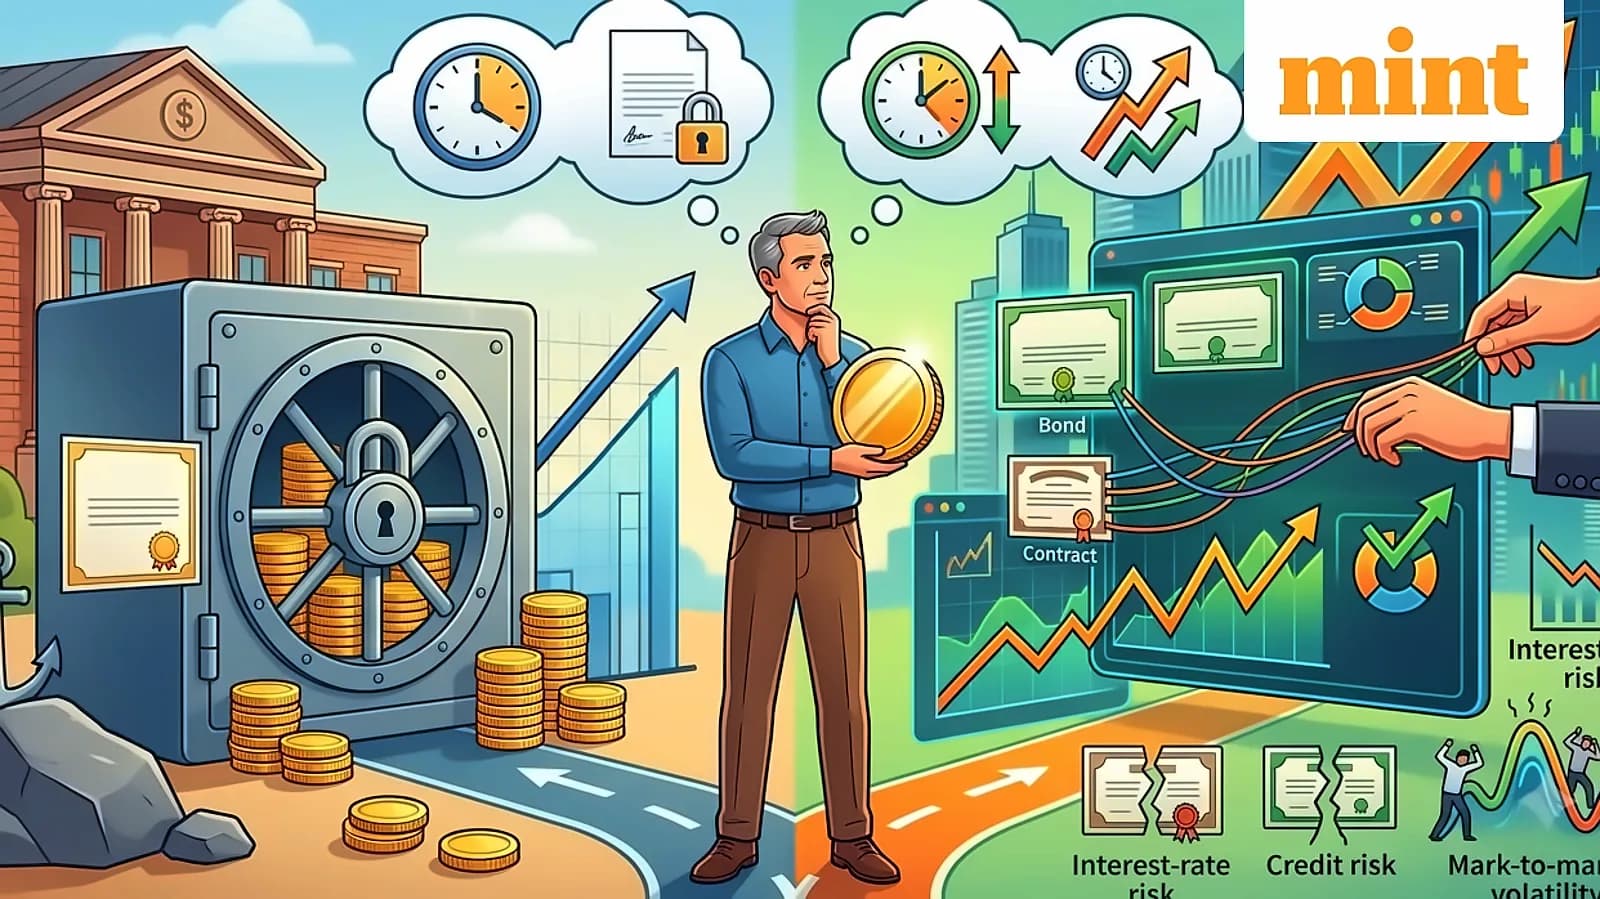
Financial experts emphasize that liquidity should be the primary consideration when planning emergency funds. According to Sarika Grover, co-founder of LoansJagat, an emergency fund is designed to provide peace of mind during unexpected challenges like medical emergencies, job loss, or urgent home repairs. The ideal approach involves keeping a portion in a savings account for instant access while parking some amount in short-term or sweep-in FDs to earn slightly better returns. As reported by Mint, this balanced strategy ensures money remains both available and productive during uncertain times.
For managing final payouts, high-interest savings accounts offer the perfect balance between safety, liquidity, and returns. The IDFC FIRST Bank Savings Account exemplifies this approach with competitive interest rates up to 6.50% p.a., credited monthly rather than quarterly to maximize compounding benefits. Unlike traditional FDs, these accounts provide 24x7 access without penalties for early withdrawals, making them ideal for uncertain income timelines. A good rule of thumb suggests keeping 30-40% of employee stock ownership plan proceeds in high-yield savings accounts for the first few months to cover tax liabilities and emergency expenses while finalizing long-term investment plans.
For individuals in highest tax brackets, FDs can result in significant tax liability of up to 30%. Aswini Bajaj, CEO of Leveraged Growth, suggests that arbitrage funds may be more suitable as they offer FD-like returns while long-term capital gains are taxed at 12.5% after one year. However, he notes that arbitrage funds may take a couple of days to liquidate, but with available credit cards, health insurance, gold, and bank credit facilities, this access timeline remains manageable. For lower tax brackets or families with senior citizens, traditional FDs may still make sense to reduce taxable FD returns.
Experts recommend prioritizing liquidity first by maintaining a portion in savings accounts for instant access during unforeseen events. According to Mint reports, short-term FDs or FD-linked options can be used for surplus funds to earn better returns without locking all money away. The strategy involves matching allocation to individual tax brackets - individuals in lower tax brackets may benefit more from traditional FDs than complex alternatives. Additionally, experts emphasize the importance of ensuring multi-layer financial backup through credit cards, insurance, and other lines of credit to meet liquidity requirements when emergency funds remain insufficient or locked due to investment terms.
Proper emergency fund planning serves as a fundamental component of long-term economic stability, acting as a financial safety net during uncertain times. As reported by Mint, choosing the right mix of savings and investment instruments can ensure both peace of mind and efficiency. Given the complexity of options and tax ramifications, certified financial advisor guidance is prudent before deciding to park emergency funds in any particular financial instrument. The strategy prevents individuals from falling into forced personal loans or debt traps during financial emergencies, making careful management of final payouts crucial for successful career transitions.