The US 10-year Treasury yield briefly crossed 5% on 14 September, marking the first time since October 2023. According to multiple reports, higher energy prices, renewed inflation concerns, expectations for tighter Federal Reserve policy and concerns around US government borrowing have all contributed to this rise. At yields around 5%, high-quality bonds may be able to contribute a larger share of the return some investors require, making a more balanced allocation worth considering, particularly for investors whose portfolios have become equity-heavy or who are moving closer to a financial goal. However, yields around 5% are not a ceiling - they could move higher if inflation remains persistent, oil prices stay elevated, growth remains resilient, or the Federal Reserve tightens further. Equally, weaker economic growth or more convincing moderation in inflation could eventually pull yields lower.
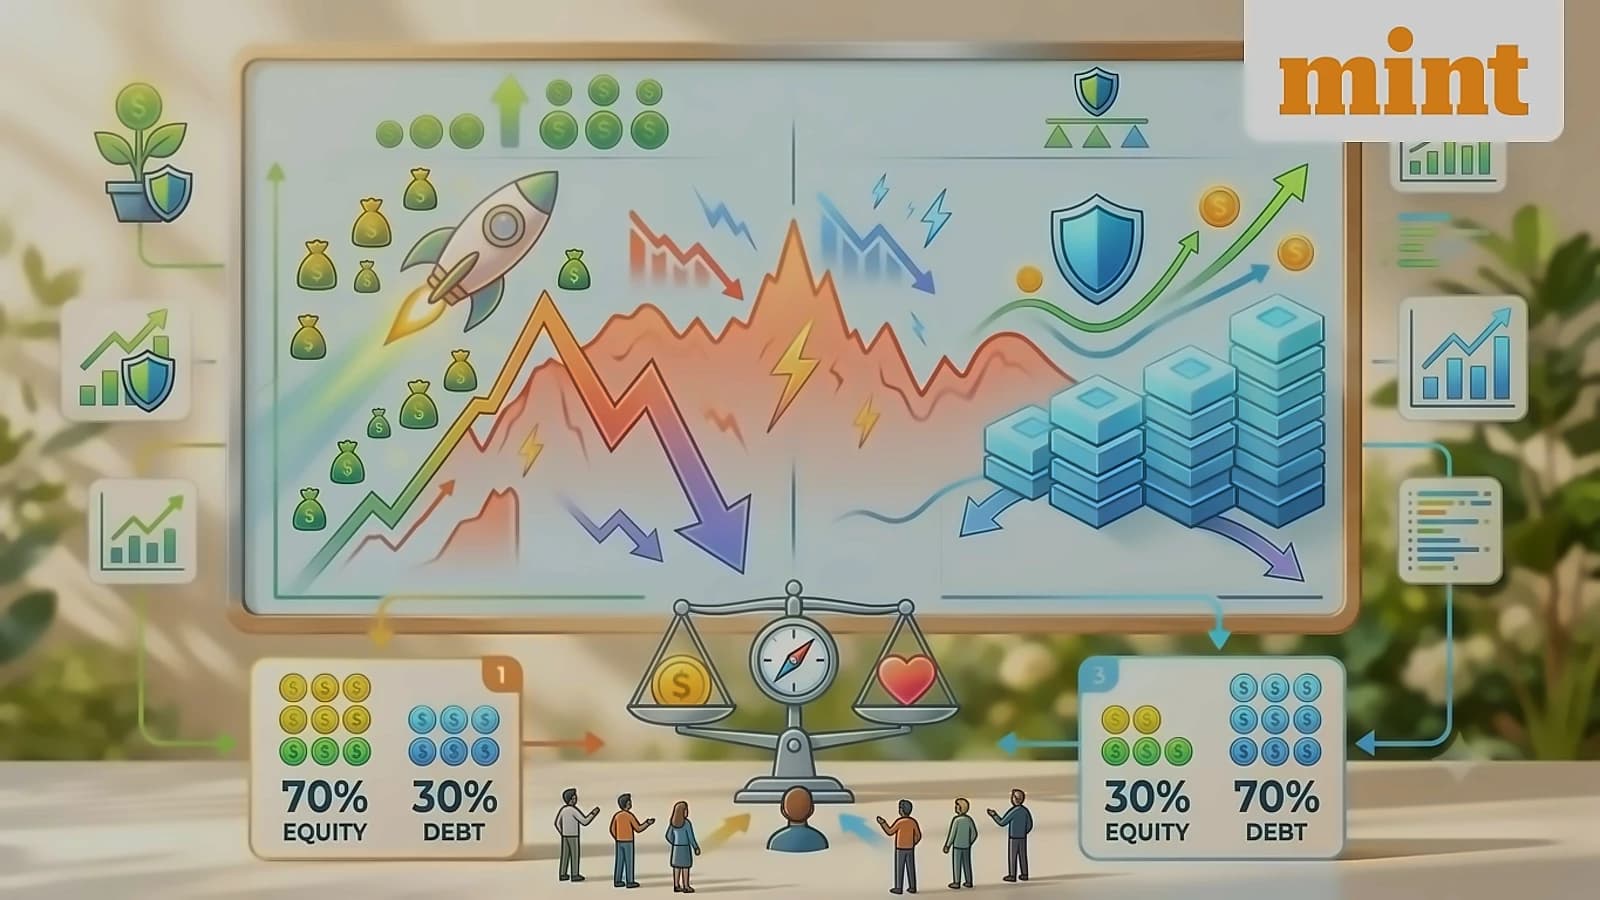
According to FundsIndia Research analysis, higher debt allocations have historically helped reduce the impact of market falls, though they come with lower return potential. The research compared portfolios with different combinations of equity, debt and gold, using Nifty 50 TRI for Indian equity, S&P 500 total returns for US equity, gold returns and a basket of low-duration and corporate bond funds for debt. Portfolios were rebalanced annually when allocation moved beyond a 5% band. As reported by FundsIndia, the analysis shows that more debt can reduce how much your portfolio falls, but the protection comes at a cost of lower long-term returns. The relevant trade-off now becomes cash and very short-term bonds generally have relatively low price sensitivity and provide flexibility, but their income is only secured for a short period. Longer-duration bonds provide greater visibility over yields for a longer period, but their market prices are more sensitive to changes in interest rates.
The research revealed clear patterns in portfolio performance based on debt allocation. According to FundsIndia, the 70% equity + 30% debt portfolio delivered an average 7-year return of 13.8% with a maximum drawdown of 40%. When debt allocation increased to 50%, the average return fell to 12.5% while the maximum drawdown reduced to 27%. With 70% debt and 30% equity allocation, the average return dropped further to 10.7% but the maximum drawdown was only 14%. As noted by FundsIndia, investors choosing more equity historically got greater return potential but had to prepare for bigger falls, while increasing debt reduced those falls but also reduced return potential. At current yield levels, high-quality bonds may be able to contribute a larger share of the return some investors require, making a more balanced allocation worth considering.
The analysis also tested portfolios combining equity, debt and gold. According to FundsIndia, a 70:15:15 portfolio (70% equity, 15% debt, 15% gold) delivered an average 7-year return of 15.0% with 92% of periods producing returns above 10%. The 50:25:25 portfolio achieved 14.2% average return with 81% of periods above 10%, while the 30:35:35 portfolio returned 13.2% with 72% of periods above 10%. The historical data shows that portfolios with more debt and gold had smaller maximum drawdowns, with the 30:35:35 portfolio experiencing a maximum drawdown of 17% compared to 27% for the 50:25:25 portfolio and 40% for the 70:15:15 portfolio. At current yield levels, portfolios with more debt and gold had smaller maximum drawdowns, making them potentially more attractive for investors seeking downside protection.
As reported by FundsIndia, the data does not point to one ideal debt allocation for all investors, instead showing the trade-off investors must consider. For investors who cannot tolerate 30% or 40% declines in portfolio value, choosing allocations with less equity may help maintain investment discipline during market corrections. Conversely, investors with longer horizons and higher volatility tolerance may be willing to hold more equity. According to FundsIndia, the best allocation is not necessarily the one with the highest historical return but the one whose risk level an investor can withstand without abandoning the investment strategy when markets fall. At current yield levels, portfolio allocation comes back to three factors: the return required, the time available to achieve it and the amount of volatility an investor can tolerate along the way. Higher bond yields do not automatically make equities unattractive, but they can create clearer winners and pressure points, making it essential to reassess the trade-offs between fixed income, equities and other assets.