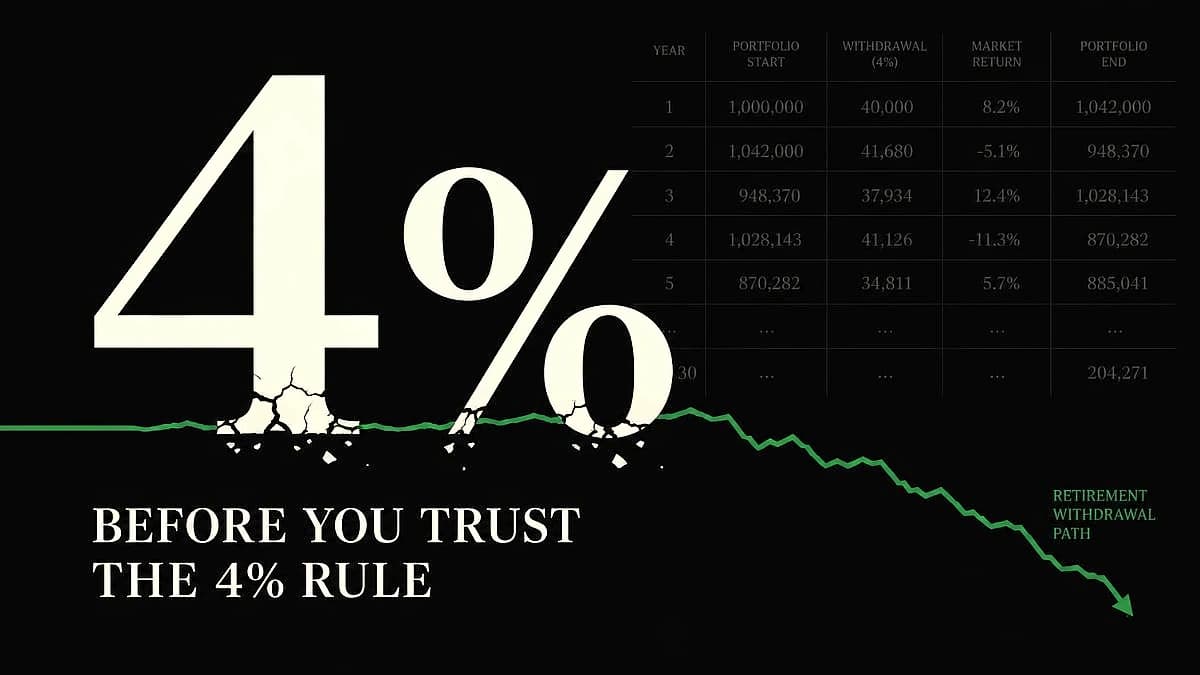
According to latest reports from Mint, early retirement presents unique challenges that require different withdrawal strategies. Retiring at 45 can mean funding expenses for 40 years or more, making the withdrawal strategy as important as building the corpus. The popular 4% withdrawal rule, developed by William Bengen in 1994 using US market data and calibrated to a 30-year retirement period, may not suit early retirees in India. Recent Indian retirement analysis suggests that the widely cited 4% rule, developed from US market experience, may be too aggressive for India and that 3% to 3.5% can be more appropriate because of differences in inflation, market volatility and available retirement products. Sanjiv Bajaj from BajajCapital suggests a more conservative starting withdrawal rate of around 3-3.5% for early retirees, while Sandeep Jethwani from Dezerv recommends a fixed-income runway covering 5-7 years of essential expenses rather than the conventional 2-3 years. The rule's original testing against historical data from 1926 to 1976 showed no cases where a 4% annual withdrawal rate exhausted a retirement portfolio in fewer than 33 years, but early retirees face significantly longer withdrawal periods requiring more conservative approaches.
As reported by Mint, a ₹2 crore corpus provides different withdrawal options with varying sustainability periods. At a 3% withdrawal rate, the corpus would provide approximately ₹6 lakh annually or ₹50,000 monthly initially. At 4%, the first-year withdrawal rises to roughly ₹8 lakh or ₹66,667 monthly. 5% withdrawal would mean around ₹83,333 monthly, while 6% would provide ₹1 lakh. However, higher withdrawal rates create greater pressure on the corpus during extended retirement periods. Considering a ₹2 crore corpus invested to earn an average 5% annually with constant withdrawals, at 8% withdrawal rate (₹1.33 lakh monthly), the corpus could be exhausted in roughly 18 years. At 6% (₹1 lakh monthly), it could last around 32 years under the same assumptions. These calculations are illustrative and not guaranteed outcomes, as actual returns fluctuate and withdrawals during market downturns can significantly impact results.
As reported by Mint, one of the biggest risks after early retirement is having to sell equity mutual funds during a market correction to meet regular expenses. Sequence-of-returns risk becomes particularly important when the retirement period is long, as poor market returns early in a 40-year retirement can cause lasting damage to the corpus. Rahul Jain from Nuvama Wealth and Rahul Jain from BajajCapital both recommend maintaining a contingency buffer equivalent to 2-3 years of living expenses in debt or liquid instruments. Jethwani takes a more conservative view, suggesting a fixed-income runway covering 5-7 years of essential expenses for early retirees. The strategy involves topping up the fixed-income runway during good market years while leaving the equity portfolio untouched during poor years. This creates a buffer between market volatility and day-to-day expenses, allowing early retirees to avoid selling equity investments during market downturns. Mint analysis emphasizes that investment strategy matters just as much - keeping the entire corpus in low-return assets may reduce market volatility but can make it harder for the corpus to outpace inflation over a long retirement.
As reported by Investing.com India, the 8% yield strategy provides several advantages over traditional withdrawal methods. The consistent monthly income of $6,667 eliminates the need to sell shares during market declines, reducing portfolio stress and preserving capital. During down years like 2022, this approach consumes 36% less of the portfolio compared to selling shares monthly to meet the same income requirement. The strategy also offers diversification across multiple income sources including safe municipal bonds, energy toll collectors, and covered-call funds, reducing dependence on any single asset class. The recommended income strategy involves diversification across six independent buckets including safe municipal bonds paying 7-8% (federal tax-free), energy toll collectors, covered-call funds paying 9-11%, and bond funds offering up to 17%. This approach reduces concentration risk compared to the S&P 500, which relies on just seven stocks representing one-third of the index. Mint analysis suggests a practical approach can be to keep a portion of the corpus in relatively stable and liquid investments for near-term expenses, while investing another portion for long-term growth, with the exact allocation reflecting age, risk tolerance, and other income sources.
According to Mint analysis, early retirement portfolios must account for expenses that can rise significantly over several decades. Bajaj cautioned that healthcare costs can be particularly damaging because a major medical event could force an investor to liquidate long-term investments at an unfavorable time. Jethwani recommends separating essential and lifestyle expenses, with essentials such as groceries, utilities, insurance premiums and basic healthcare funded from fixed income, while lifestyle expenses can be supported through withdrawals from equity and hybrid investments. The same principle applies to unexpected expenses more broadly - a retiree who keeps all wealth invested for long-term growth but has no liquid reserve may be forced to disturb the portfolio at the wrong time. For someone retiring in their 40s, this matters even more because the portfolio may need to survive multiple market cycles. Mint emphasizes that inflation is the part retirees often underestimate - if household needs ₹70,000 monthly today, that amount will not buy the same basket of goods 15 or 20 years from now. Healthcare costs can also become more significant with age, making it crucial to withdraw a fixed amount without periodically reviewing expenses and investments to maintain purchasing power.