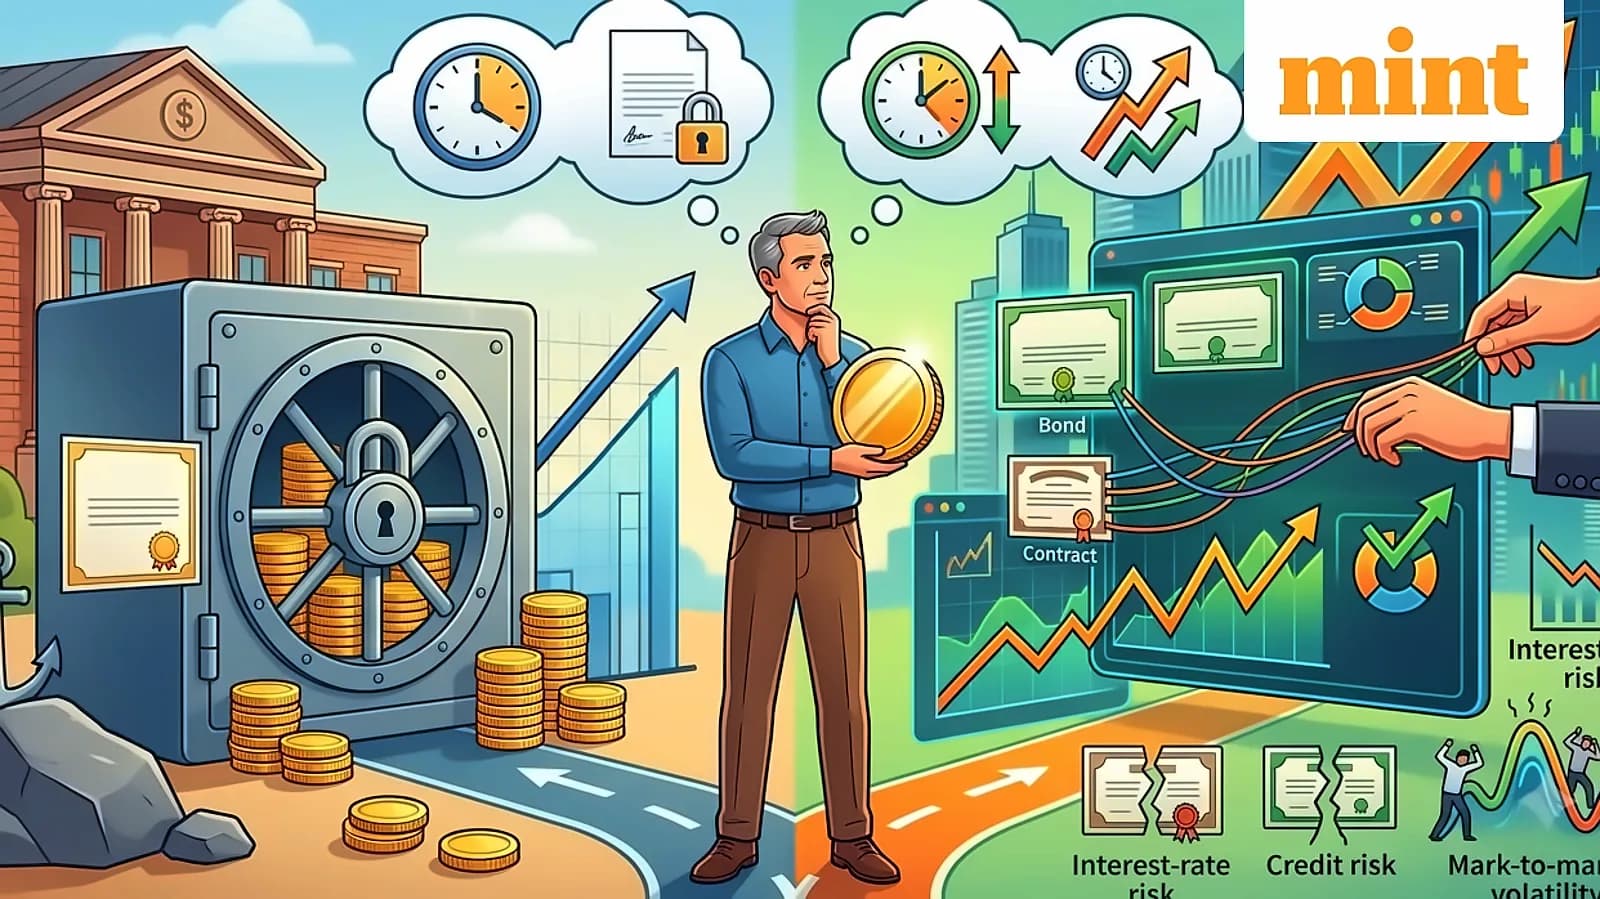
While both corporate FDs and corporate bond funds offer higher returns than traditional bank deposits, they function through different mechanisms and carry distinct risk profiles. Corporate FDs are direct investments in fixed deposits offered by private companies, providing investors with enhanced interest rates of 1-2 percentage points above traditional bank FDs. In contrast, corporate bond funds are mutual funds that pool money from multiple investors to purchase high-quality corporate bonds, offering investors exposure to a diversified portfolio of top-rated securities. The risk-return trade-off is fundamental to both investment options, with corporate FDs offering higher direct returns but carrying specific company-level risks including potential defaults and limited deposit insurance coverage, while corporate bond funds provide diversified exposure with lower concentration risk through professional fund management.
Private companies are now offering fixed deposits with interest rates that are 1-2 percentage points higher than traditional bank FDs, according to reports from Business Standard. These corporate FDs function similarly to bank deposits but provide investors with significantly improved returns. However, if you prematurely withdraw the FD, the interest may be recalculated according to the bank's premature-withdrawal rules, and a penalty may apply. If the FD is renewed at maturity, the interest rate prevailing on the renewal date will generally apply. The repo rate hike may encourage banks to review the rates offered on new deposits, but a higher FD rate is not guaranteed. Banks determine deposit rates based on several factors, including: Therefore, compare the available tenures and applicable rates instead of assuming that every FD rate will rise by 25 basis points.
Corporate bond funds offer steady income through regular coupon payments issued twice yearly, with performance varying based on market conditions and credit ratings. According to recent data, ICICI Pru Corporate Bond Fund shows returns ranging from 4.89% to 7.41%, while Nippon India Corporate Bond Fund offers returns between 4.28% to 7.13%. These funds invest at least 80% of assets in AA+ and above rated corporate bonds, providing investors with exposure to well-established companies while maintaining relatively low credit risk. The risk premium for corporate bonds reflects the compensation investors receive for taking on additional credit risk compared to government securities, with highly rated corporate bonds typically offering lower interest rates than lower-rated alternatives due to reduced default probability.
Investors considering corporate FDs should evaluate the credit ratings of each FD issuer before making investment decisions, as reported by Business Standard. For corporate bond funds, fund managers carefully select corporate bonds that are highly rated (usually AA+ or AAA) and invest in them through professional research and risk management processes. The diversified nature of corporate bond funds reduces concentration risk, as money is spread across bonds from different high-quality companies and sectors. This diversification helps mitigate the risk of any single company default, making corporate bond funds generally more stable than direct corporate FD investments. To navigate the changing interest rate environment, consider the following strategies: Instead of investing your entire amount in one FD, you can divide it across deposits with different maturity dates. As each FD matures, you can review the prevailing rates and decide whether to reinvest it. FD laddering can provide periodic access to funds and reduce the risk of locking your entire deposit at a single interest rate. However, splitting deposits at the same bank does not increase the DICGC insurance cover, which applies per depositor per bank.
The decision between corporate FDs and corporate bond funds depends on individual risk tolerance and investment goals. Corporate FDs offer higher direct returns but carry specific company-level risks including potential defaults and limited deposit insurance coverage. Corporate bond funds provide diversified exposure with lower concentration risk through professional fund management, though they may offer slightly lower returns than direct corporate FD investments. Both options require careful consideration of enhanced returns against associated risks, with corporate bond funds suitable for conservative investors seeking stable yields ahead of FDs and those with investment horizons ranging from one to three years. The risk premium for these investments reflects the compensation investors receive for taking on additional credit risk, with corporate bond funds offering professional management and diversification benefits that may outweigh the slightly lower returns compared to direct corporate FD investments.