Borrowers receiving a ₹20,000 monthly raise face a critical decision between accelerating personal loan repayment or investing through mutual fund SIPs. According to reports from Mint, this additional income can significantly impact both debt reduction and long-term wealth creation strategies. Recent expert analysis emphasizes that prepayment offers clear financial benefits but does not automatically improve credit scores - lenders assess borrowers holistically based on repayment history and financial discipline over time.
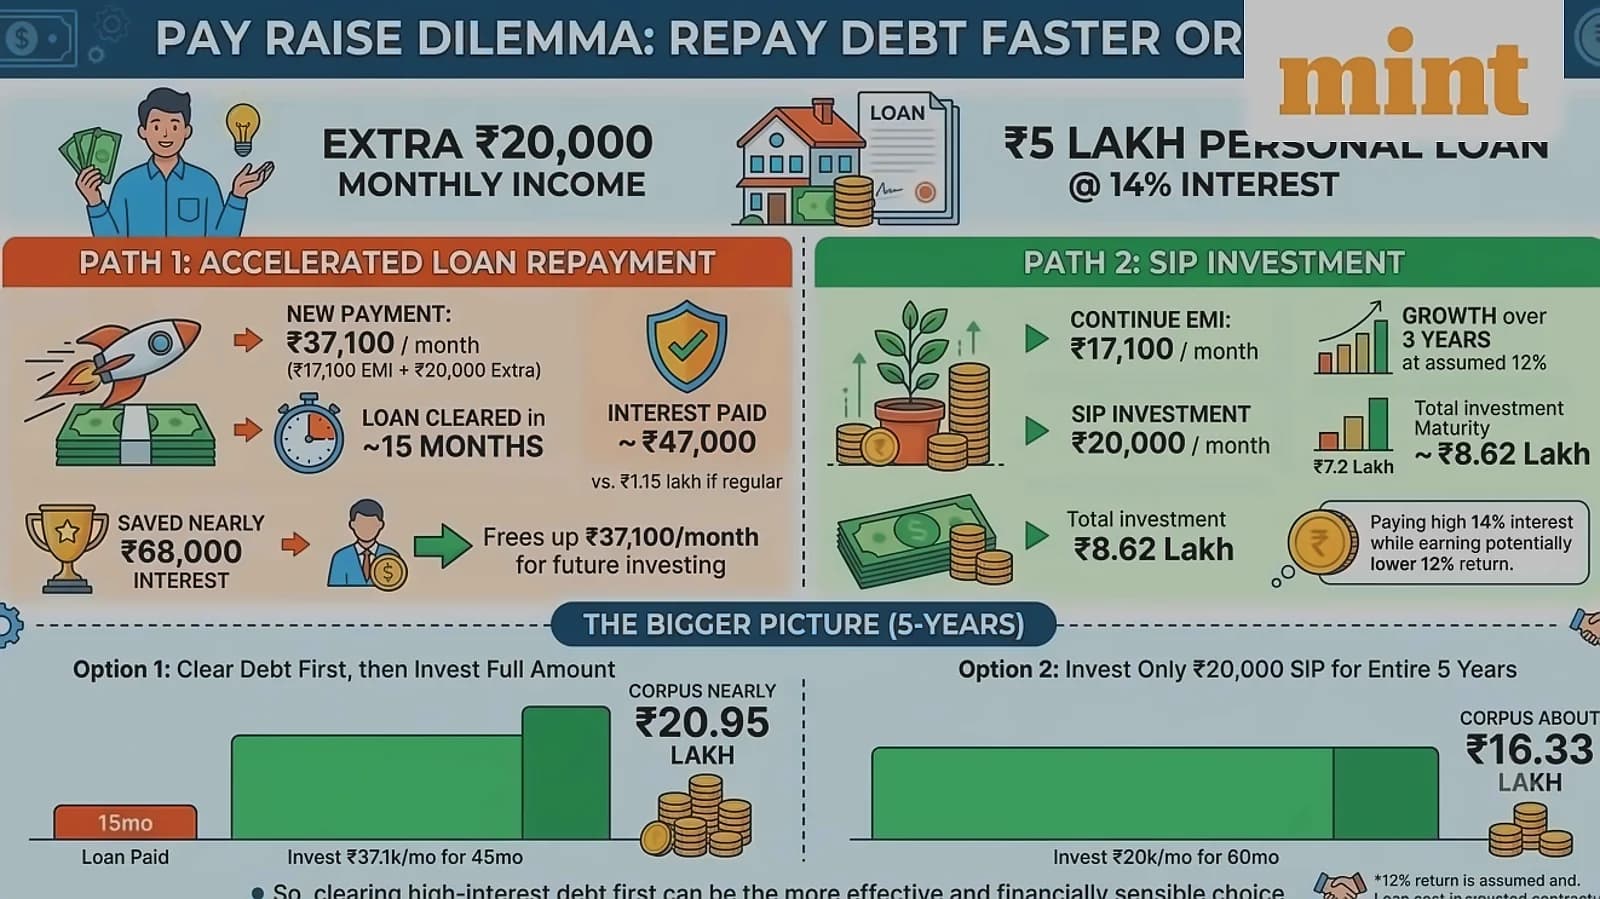
With a ₹5 lakh personal loan at 14% interest over three years, the monthly EMI of approximately ₹17,100 would result in total interest payments of ₹1.15 lakh under the standard repayment schedule. As reported by Mint, using the additional ₹20,000 monthly to increase loan repayment to ₹37,100 could clear the loan in about 15 months, reducing total interest costs to ₹47,000 and saving nearly ₹68,000 compared to the original plan. Recent analysis shows that prepaying ₹4.50 lakh at the start of a loan can remove ₹14.92 lakh in interest costs, while waiting twelve months reduces the savings to ₹13.62 lakh for the same amount. However, experts warn that borrowers should check applicable foreclosure charges and retain adequate emergency savings before committing to lump-sum prepayments.
Prepaying a loan will not damage your credit score in any lasting way, but it does not automatically lift it either, explains Vijendra Singh Shekhawat, CEO of Choice Finserv Private Limited. As reported by Mint, what lenders read is your repayment behaviour over time - a record of paying every instalment on the due date carries more weight than closing a loan early. For example, a borrower who pays every EMI on time but continues with a loan may demonstrate stronger repayment discipline than someone who closes a loan early after missing several instalments. Experts emphasize that timely EMI payments and responsible debt management are more important for maintaining a healthy credit profile than early loan closure, with consistency mattering more than speed in building a strong borrower profile.
Investing the ₹20,000 monthly in an equity mutual fund SIP with an assumed 12% annual return could grow to approximately ₹8.62 lakh over three years, requiring total investments of ₹7.2 lakh. However, clearing the loan first and then investing the freed-up ₹37,100 monthly for the remaining 45 months would create a corpus of nearly ₹20.95 lakh after five years at the same 12% annual return. Recent studies demonstrate that prepaying earns a guaranteed, tax-free return equal to the loan rate, while investments carry uncertain returns that are usually taxed. The decision becomes more complex when considering factors such as the personal loan's interest rate and the borrower's investment horizon, with prepayment fees being a key consideration for lenders.
The loan prepayment strategy offers significant advantages beyond immediate cost savings, with experts emphasizing that prepayment helps by lowering your debt and freeing up cash flow, creating substantial long-term savings. Once the loan is cleared, the entire ₹37,100 monthly can be redirected to investments, potentially creating a larger investment corpus compared to the SIP-only approach. However, experts caution that borrowers should diligently assess whether utilizing savings to meet prepayments could ultimately leave them in a difficult financial position and should check applicable foreclosure charges before committing to lump-sum payments. Recent research confirms that every rupee you prepay goes to principal, reducing the interest charged on future payments and creating substantial long-term savings, while maintaining adequate emergency savings remains crucial for financial discipline.