The Bombay Stock Exchange (BSE) has issued a formal warning to investors about international ETFs trading at steep premiums to their net asset value (NAV), advising extreme caution amid the current market volatility. According to BSE's latest notice published on September 25, 2026, "units of certain Exchange Traded Funds (ETFs), particularly those investing in overseas securities (‘international ETFs’) are trading at a substantial premium to their Net Asset Value (NAV), even though the NAVs of the underlying scheme of these ETFs have remained broadly stable." The exchange specifically warned that investors purchasing such units at steep premiums face the risk of an abrupt price fall unrelated to movements in overseas markets. BSE urged all investors and market participants to "exercise extreme caution and perform due diligence" and advised checking the NAV available on stock exchange websites or the Association of Mutual Funds in India before placing orders in international ETFs.
The Motilal Oswal Nasdaq Q50 ETF (MONQ50) experienced a dramatic reversal, crashing 20% on 22 September and losing about 46% from its peak in just two sessions. According to reports from The Financial Express, the ETF touched ₹471.99 on 21 September before falling to ₹317.04 and hitting the 20% lower circuit the following day. The correction occurred despite the underlying portfolio remaining broadly unchanged, highlighting how supply constraints can drive ETF prices far above fundamental value. As of September 23, MONQ50 units were still available at a premium of about 69%, trading at ₹202.92 against an NAV of ₹120.05. The latest developments show that MONQ50 was down another 20% intraday on 22 September, demonstrating the continued volatility in international ETF markets. BSE's warning comes as prices could correct sharply if overseas investment limits are increased or when the base price used to determine ETF price bands shifts to the previous day's NAV from April 1, 2027.
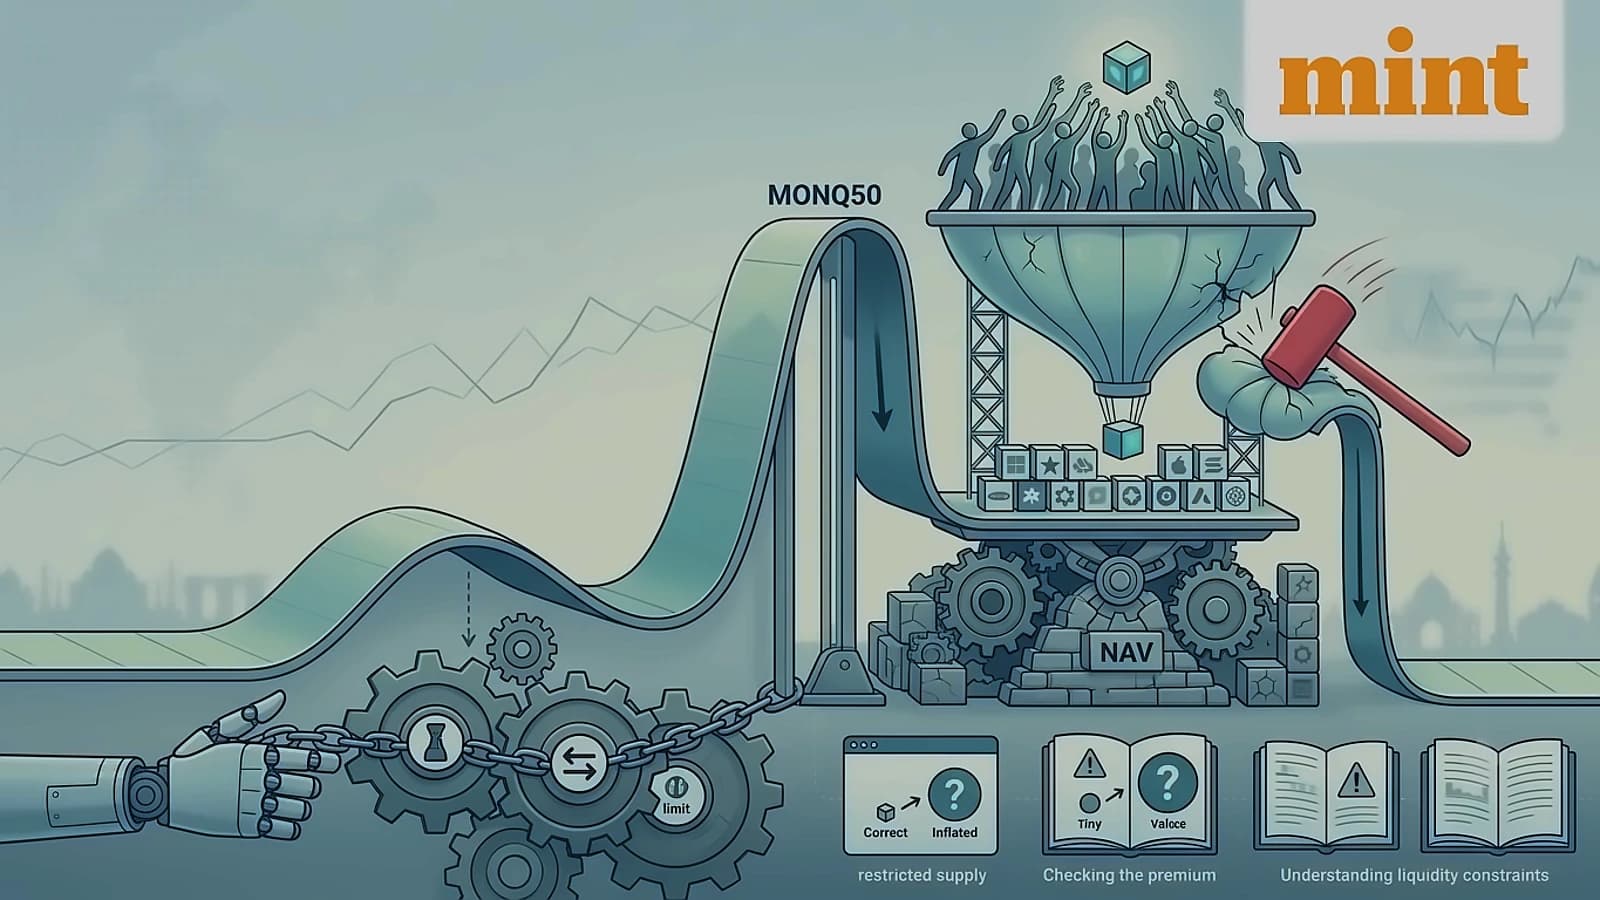
The ETF had been trading at an extraordinary premium to its net asset value (NAV), with MONQ50 trading at a premium of nearly 235% to its NAV by 18 September. As reported by The Financial Express, the ETF's market price was ₹396.30 on September 18 against an NAV of roughly ₹118, meaning the ETF continued to trade at a substantial premium even after the sharp fall. According to Business Standard, the average premium across international ETFs has generally been around 15–20 per cent over the past year, but has risen sharply since early September. As Mirae Asset Sharekhan reports, "In the case of the Motilal Oswal NASDAQ Q 50 ETF, the premium reached a maximum of 235 per cent on September 18, 2026." According to Mint, Indian investors are paying large premiums for Nasdaq and US ETF exposure, with other major international ETFs also trading at significant premiums: Mirae Asset NYSE FANG+ ETF (MAFANG) was trading at a premium of around 40%, Motilal Oswal Nasdaq 100 ETF (MON100) was around 21–24% above NAV, and Mirae Asset S&P 500 Top 50 ETF (MASPTOP50) was at a premium of about 18.6%. As Mint reports, Nippon India Hang Seng BeES (HNGSNGBEES) had a smaller premium of around 3%, showing the wide range of premium levels across different international ETFs.
The extreme price gap was attributed to supply constraints in international ETFs listed in India. As reported by The Financial Express, Souvik Biswas, Head of Research at Bajaj Capital, explained that the industry limit is USD 7 billion, meaning that additional units of an ETF cannot be created even if there is demand. With supply of units constrained, strong buying demand can push the ETF's exchange price substantially above the value of its underlying index. According to Business Standard, "If demand keeps rising while the number of available units remains fixed, the ETF can trade at a significant premium to NAV." According to Mint, Indian mutual funds face an industry-wide overseas investment limit of $7 billion, including a separate $1 billion limit for overseas ETFs. As Mint reports, Viram Shah, founder and CEO of Vested, explained that the premium is less about the valuation of US stocks and more about a supply-demand mismatch in India. BSE confirmed that the overseas investment limits available to mutual funds had been fully utilised, meaning mutual funds are restricted from creating new units of international ETFs. The numbers show how wide the gap became, with MONQ50's market price rising from ₹141.93 on 4 September to ₹396.30 on 18 September, while its NAV moved only from ₹118.74 to ₹118.14.
The recent price movements highlight the impact of SEBI's revised ETF price-band framework that took effect from September 7, 2026. Under the previous NAV-based mechanism, an ETF's price band was determined with reference to its T-2 day NAV, while the new framework references the T-1 day closing price based on the last 30 minutes volume weighted average price (VWAP). This change significantly expanded MONQ50's trading range, with the upper band expanding from approximately ₹142.60 to ₹170.32 on September 7, and further to ₹196.91 on September 8. As Motilal Oswal noted in its September 9 clarification, "the implication is that under the earlier NAV-based mechanism, the ETF's price band remained close to its NAV, whereas under the new price-based mechanism, the band moves along with the ETF's market price." The new rules set price bands based on the previous day's closing market price rather than NAV, allowing the premium to compound rapidly when ETFs trade significantly above NAV. The change is part of the ETF trading framework issued by SEBI on June 15, 2026, with provisions relating to base prices, price bands, pre-open call auctions and close-out procedures coming into effect on September 7.
The episode highlights critical risks for international ETF investors, particularly when demand is unusually high and fresh units cannot be created easily. According to The Financial Express reports, investors should check the iNAV (Indicative Net Asset Value) against the ETF's market price before buying. As Business Standard reports, "An investor's return depends on both the NAV and the gap between NAV and the ETF's market price." As Mirae Asset Sharekhan explains, "If an ETF with an NAV of Rs 100 is purchased at Rs 150, representing a 50 per cent premium, and the premium subsequently normalises to 20 per cent, the market price could fall to Rs 126 even if the NAV rises to Rs 105," highlighting how buyers can lose despite underlying asset growth. A high premium may indicate strong current demand, but a small change in sentiment can cause that premium to collapse. As noted by experts, when an ETF trades 20%, 50% or more than 200% above its NAV, investors are taking different risks beyond just the performance of underlying US companies, as they are also betting that another investor will continue to pay the premium. The latest correction demonstrates how quickly these premiums can unwind, with MONQ50's market price falling ₹178.66 from its peak of ₹471.99 in just two weeks, while its underlying NAV remained relatively stable. Viram Shah warns that "a falling premium also does not automatically make an ETF cheap. A premium falling from 235% to 111% is still a very substantial premium, and still more than double the price of buying the same index abroad." BSE's warning emphasizes that prices could correct sharply if overseas investment limits are increased or when the base price used to determine ETF price bands shifts to the previous day's NAV from April 1, 2027.