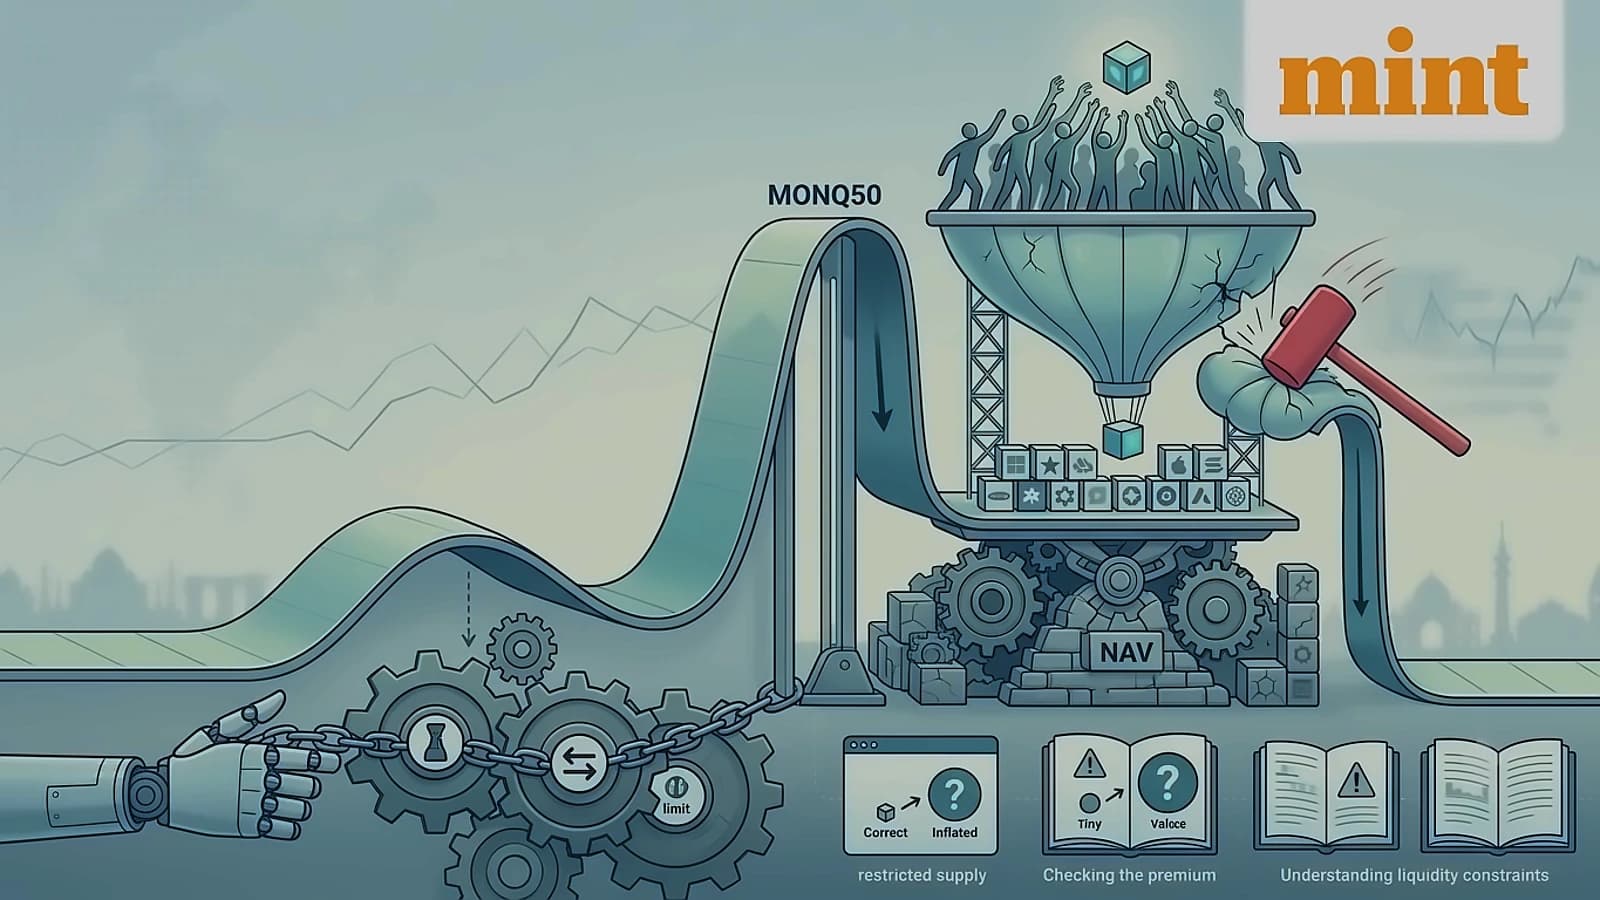
The National Stock Exchange has issued a cautionary advisory to investors regarding international exchange-traded funds experiencing significant price premiums. According to reports from The Economic Times, the NSE warned that several ETFs were trading at significant premiums to their underlying net asset values, creating risks for investors purchasing at inflated prices. The exchange emphasized that purchasing such units at steep premiums may be exposed to the risk of an abrupt fall in prices, unrelated to movements in the underlying securities. As per the latest NSE press release of September 25, 2026, the exchange specifically warned that buyers at steep premiums risk an abrupt price fall unrelated to the underlying. The latest developments show this warning becoming increasingly relevant as premiums have reached concerning levels across multiple global ETFs.
The Motilal Oswal Nasdaq Q50 ETF has experienced a dramatic premium surge, with its gap between price and NAV climbing from 63% on September 30 to 110% on October 7. According to latest market data, the ETF's price rose 33% over the week, with 18% of that gain occurring on October 7 alone, when it traded as high as ₹263.04 before closing at ₹258.57. The premium surge was driven by heavy trading activity, with ₹70 crore of Q50 units changing hands on October 7, about 14 times its 52-week average of ₹5.1 crore a day. As per The Hindu BusinessLine, the ETF's units closed at ₹246 on the BSE against a reported NAV of ₹120.05 on Friday, meaning investors were paying more than twice the underlying value of the ETF's assets. While the current premium remains below its September 18 peak of 235%, the recent recovery from the September 28 low of 57% demonstrates the volatility in these international ETF markets.
The substantial premiums in international ETFs stem from overseas investment limits available to Indian mutual funds being exhausted, restricting the creation of fresh units. According to The Hindu BusinessLine, demand exceeding available supply of ETF units is one of the main reasons behind such premiums. The creation and redemption mechanism operates through authorized participants and market makers, subject to prescribed unit sizes and conditions. In international ETFs where fresh unit creation is restricted, even these participants may be unable to undertake usual arbitrage activities that would narrow the premium. SEBI provides limited safeguards for investors when ETFs become illiquid, allowing direct redemption under specified conditions including the ETF trading at a discount of more than 1% to NAV for seven consecutive days or absence of exchange quotes for three consecutive days.
According to The Economic Times and AMFI data, the surge in overseas investment demand has been driven by significant performance differentials between Indian and international markets. Assets in mutual fund schemes investing abroad rose nearly 55% year-on-year to about ₹485 billion in August 2026, while investor folios increased more than 40% during the same period. The performance gap has been substantial, with the Nifty 50 falling about 8% and the Sensex about 9% over the past year, while the Nasdaq-100 gained roughly 24%. This performance differential continues to drive strong demand for international ETFs, even as premiums reach concerning levels. At current exchange rates, ₹100 of US shares costs ₹210 through the Q50 and ₹113 through the Nasdaq 100 ETF, representing the additional premium investors must pay for international exposure.