According to the September 2026 report from DSP Mutual Fund titled "NETRA - Early Signals Through Charts," investors with 50% of their portfolio in flexi-cap funds may face significant overlap when adding another equity fund category. The report finds that only 25% to 36% of the equity exposure is genuinely different across key fund categories when compared with the average flexi-cap equity portfolio. As reported by Mint, the message is straightforward: "You may own more of the same than you think. You need less." This concept extends beyond fund categories to individual stock holdings, where two funds from two different fund houses, with two different names and two different star ratings, can still end up owning many of the same large-cap companies. When that happens, investors aren't diversified - they're duplicated, as highlighted in recent analysis from Financial Friend.
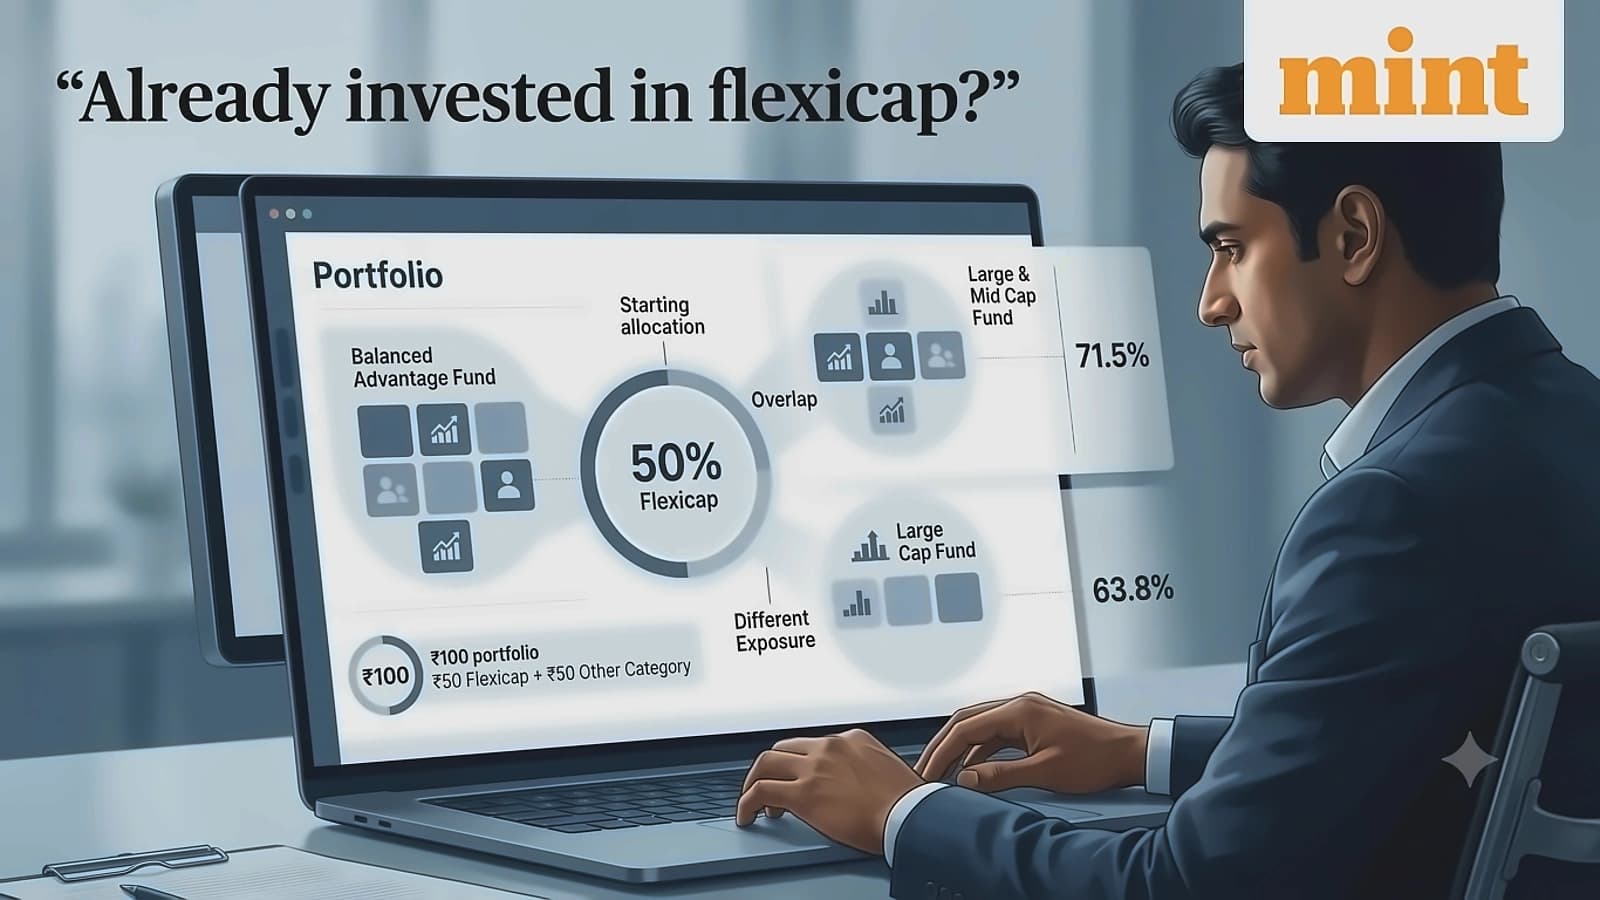
The report compares four categories, creating six possible pairwise combinations to assess overlap. Among the categories highlighted, Balanced Advantage Funds (BAFs) show the highest overlap with flexi-cap funds. According to the analysis, if an additional ₹50 investment is made in a BAF, 75.3% of its equity exposure is already represented through the flexi-cap portfolio, leaving only 24.7% as different exposure. For large & mid-cap funds, 71.5% of the equity exposure is already present, while just 28.5% is different. Large-cap funds show slightly lower overlap at 63.8% present and 36.2% different. This overlap becomes particularly problematic when investors own multiple funds from different sources, as four of them may be large-cap-oriented and all four hold significant positions in the same handful of blue-chip stocks, effectively creating one concentrated bet across five different fund statements.
Across the six combinations analyzed, the report finds 53% to 76% of equity exposure is common between the two categories. The three flexi-cap comparisons demonstrate significant overlap: 75.3% with BAFs, 71.5% with large & mid-cap, and 63.8% with large-cap. As reported by Mint, the broader point is that category labels alone cannot tell investors how diversified their portfolios really are. The analysis emphasizes that investors may need to examine underlying holdings and identify how much of new funds are genuinely different from existing investments. Recent research from Financial Friend confirms this, showing that two funds with completely different names, different fund houses, and even different categories can still hold significant positions in the same set of companies or sectors, creating concentration risk disguised as diversification.
For investors considering a ₹100 equity portfolio allocation, with ₹50 already in flexi-cap funds, adding another ₹50 to large-cap, large & mid-cap, or balanced advantage funds may not provide as much new equity exposure as expected. According to the report, instead of simply adding another category, investors may need to look at underlying holdings and identify how much of the new fund is genuinely different from what they already own. The analysis suggests that category labels alone cannot determine portfolio diversification, requiring investors to examine individual stock holdings across different fund categories. Recent guidance from Financial Friend reinforces this approach, emphasizing that a good portfolio is defined by purpose and clarity, not by the number of funds in it, with the key question being "Does this fund serve a different purpose than the others? Does it genuinely add something the rest of the portfolio doesn't already have?"
To avoid common mutual fund mistakes, investors should regularly review their Consolidated Account Statement (CAS) and use tools like CasAnalyser to get a portfolio-level view. The starting point is understanding that "more funds" doesn't automatically mean more safety - a well-constructed portfolio is defined by whether each fund serves a specific purpose and fits your asset allocation, risk capacity, and goals. Key questions to ask include "Do I know every mutual fund I currently own by name?", "Are two or more of my funds likely holding many of the same stocks or sectors?", and "What is my total invested amount across all platforms and folios?" Most importantly, investors should attach every SIP/lump sum to a named goal and horizon, as "I invest in mutual funds" without specific purpose tells you very little about whether the fund or time horizon is appropriate. The fundamental principle is that "buy and hold" is a sound long-term principle, but "buy and forget" is not the same thing - regular portfolio reviews are essential for maintaining diversification and suitability over time.