SS Retail shares surged nearly 7% on 28 September, gaining 83% since its IPO debut. According to reports from LiveMint, the stock made a strong debut on 23 September, listing at a substantial premium to its issue price. On the BSE, the stock opened at ₹639.10, up 50.73% from the IPO price, surging as much as 80.87% during the session to ₹766.90 and eventually closing at ₹765.15, marking a gain of 80.45%. On the NSE, SS Retail shares debuted at ₹624, representing a 47.16% premium over the issue price, ending the session at ₹748.80, up 76.60%.
The ₹500-crore SS Retail IPO received an overwhelming response, with bids 103.30 times subscribed on the final day of bidding. As reported by LiveMint, the issue comprised a fresh issue of shares worth up to ₹360 crore and an Offer-for-Sale (OFS) of up to ₹140 crore, with a price band of ₹403– ₹424 per share. Following the sharp gains at its listing, the company's market capitalisation stood at ₹5,690.24 crore, which has since reduced to ₹5,331.41 crore as of today. The strong debut was supported by the company's asset-light COFO model and strong ROE/ROCE metrics.
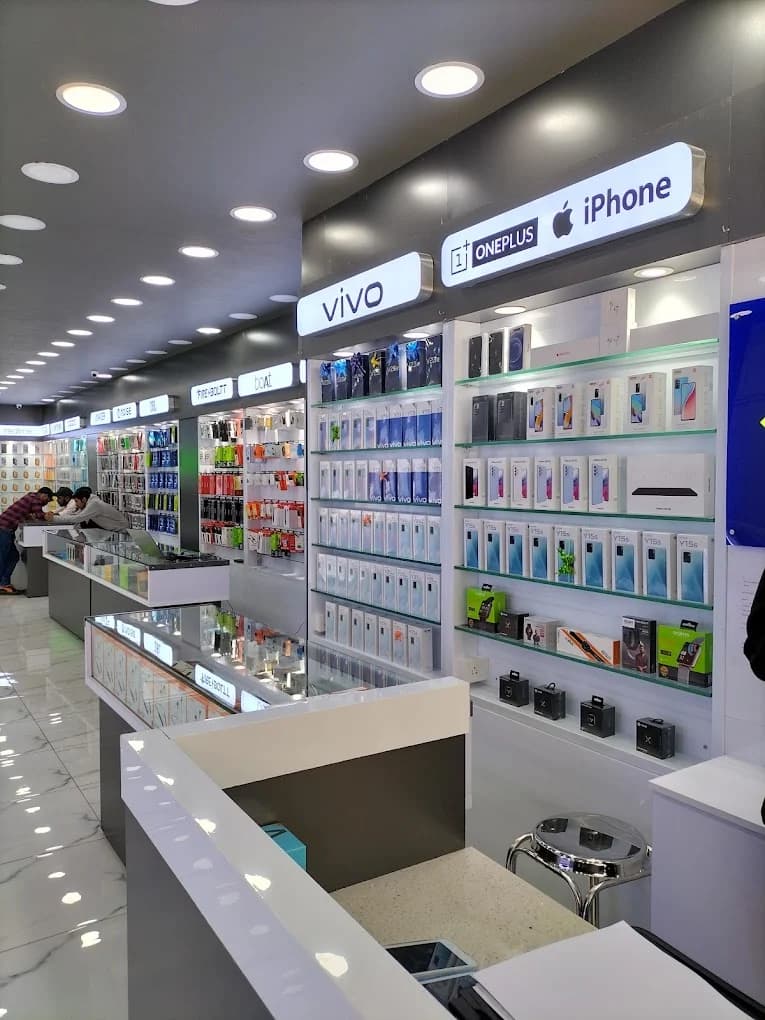
According to LiveMint reports, SS Retail operates a multi-brand retail chain selling mobile phones, accessories and other electronic products, with a focus on Tier-II, Tier-III and smaller cities. As of 31 March 2026, the company operated 503 stores across 215 cities, including 458 stores in Maharashtra. The company operates under the SS Mobile, Mobile Exchange Wala and The Mobile Space brands through various models including company-owned and company-operated (COCO), company-owned and franchisee-operated (COFO), and franchisee-owned and franchisee-operated (FOFO) models. The company has presence across Maharashtra, Karnataka, Madhya Pradesh, Goa and Gujarat.
As reported by LiveMint, the Indian mobile phone market is projected to grow at a 9.2% CAGR to ₹5,198 billion by FY30, while the pre-owned smartphone market is expected to grow at a 12.7% CAGR to ₹1,419 billion. The mobile accessories market is projected to reach ₹968 billion by FY30, growing at a 15.5% CAGR. Shivani Nyati from Swastika Investmart Ltd noted that while the company made a strong debut supported by strong ROE/ROCE and its asset-light COFO model, valuations appear demanding at around 46.5x FY26 P/E.
According to LiveMint analysis, given the strong listing and limited margin of safety at current valuations, Swastika Investmart's post-listing view is Neutral. The company's growth prospects could depend on its ability to benefit from organised retail, changing consumer preferences and expansion of its store network. Key factors to track include quarterly revenue growth, same-store sales, margins, store expansion and cash-flow generation. For long-term investors, the company's performance will be influenced by its ability to capitalize on the growing mobile and electronic products market in India.