India's wood-products industry presents significant growth opportunities as homes shrink but demand for smarter storage solutions increases. According to Euromonitor, demand for wood and wood products in India reached US$17.2 billion in 2024, while industry production stood at US$22.7 billion. The market remains highly fragmented, with the top five companies accounting for only 4.2% of total production value in 2024, highlighting substantial room for organised manufacturers to gain market share. The plywood segment alone is projected to grow from ₹24,785 crore in 2025 to ₹39,190 crore by 2034, representing a CAGR of 5.22% during the forecast period.
Greenply Industries reported strong Q1 FY27 results with consolidated revenue of ₹724.9 crore, up 20.7% YoY from ₹600.8 crore in Q1 FY26. The company's MDF revenue increased 32.8% YoY to ₹195.7 crore, while plywood and allied products generated ₹526.6 crore, up 16.0% YoY. Most significantly, MDF volumes increased 24.7% YoY to 57,805 cubic metres, indicating substantial underlying volume growth rather than pricing-driven increases. The company maintains a 22% market share in India's organised plywood market and has expanded into furniture fittings through its joint venture Greenply Samet Pvt. Ltd.
Century Plyboards delivered impressive Q1 FY27 results with revenue of ₹1,561.38 crore, up 33.5% YoY from ₹1,169.36 crore in Q1 FY26. The company's particle-board business showed exceptional growth with revenue rising 156.6% YoY to ₹87.65 crore, while total volumes increased 155.7% YoY to 41,680 cubic metres. The segment EBITDA turned positive at ₹2.91 crore compared to a ₹1.28 crore loss in Q1 FY26, marking a significant shift from proving demand to demonstrating profitability. Century maintains a market share of around 29% in India's organised plywood sector and operates through a pan-India network of 4,161 dealers and 19,072 retailers.
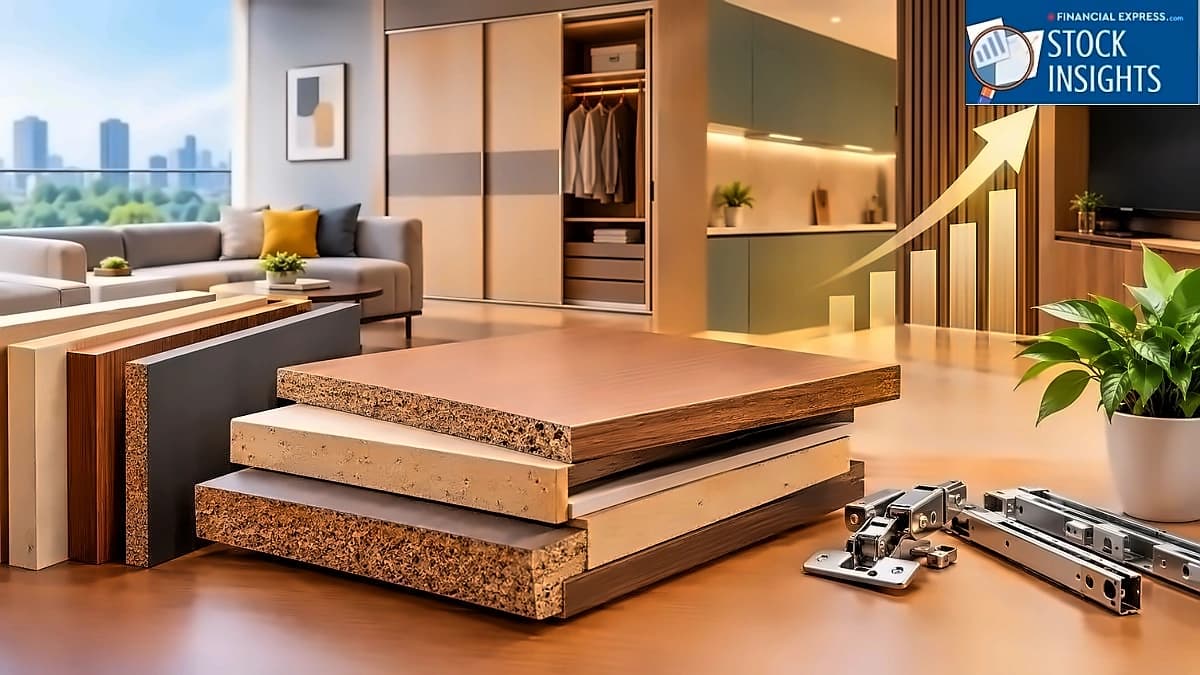
Both companies face different valuation challenges despite growth opportunities. Century Plyboards trades at a premium P/E of 53.71 compared to Greenply's 32.45, reflecting market expectations for stronger earnings growth. However, Greenply's reported return on capital employed (ROCE) of 14.33% exceeds Century's 11.46%, suggesting more efficient capital utilisation. Equirus Securities maintains a Buy recommendation for Greenply with a ₹391 target price, while Motilal Oswal retains its Buy rating for Century with a ₹893 target. The investment case now centers on execution capabilities, with companies needing to demonstrate that space-efficient living trends can translate into sustainable earnings growth and improved returns on capital invested.