Despite ongoing market volatility from geopolitical tensions, crude oil prices, and foreign selling pressure, analysts identify significant opportunities for disciplined investors. According to Axis Direct's Uttam Kumar Srimal, Q2FY27 earnings and management commentary will be key market drivers, with investors focusing on revenue growth, margin trends, and pricing power. Vinit Bolinjkar from Ventura remains positive on Indian equities over the next 2-3 years, supported by rising incomes, premiumisation, and manufacturing localisation trends.
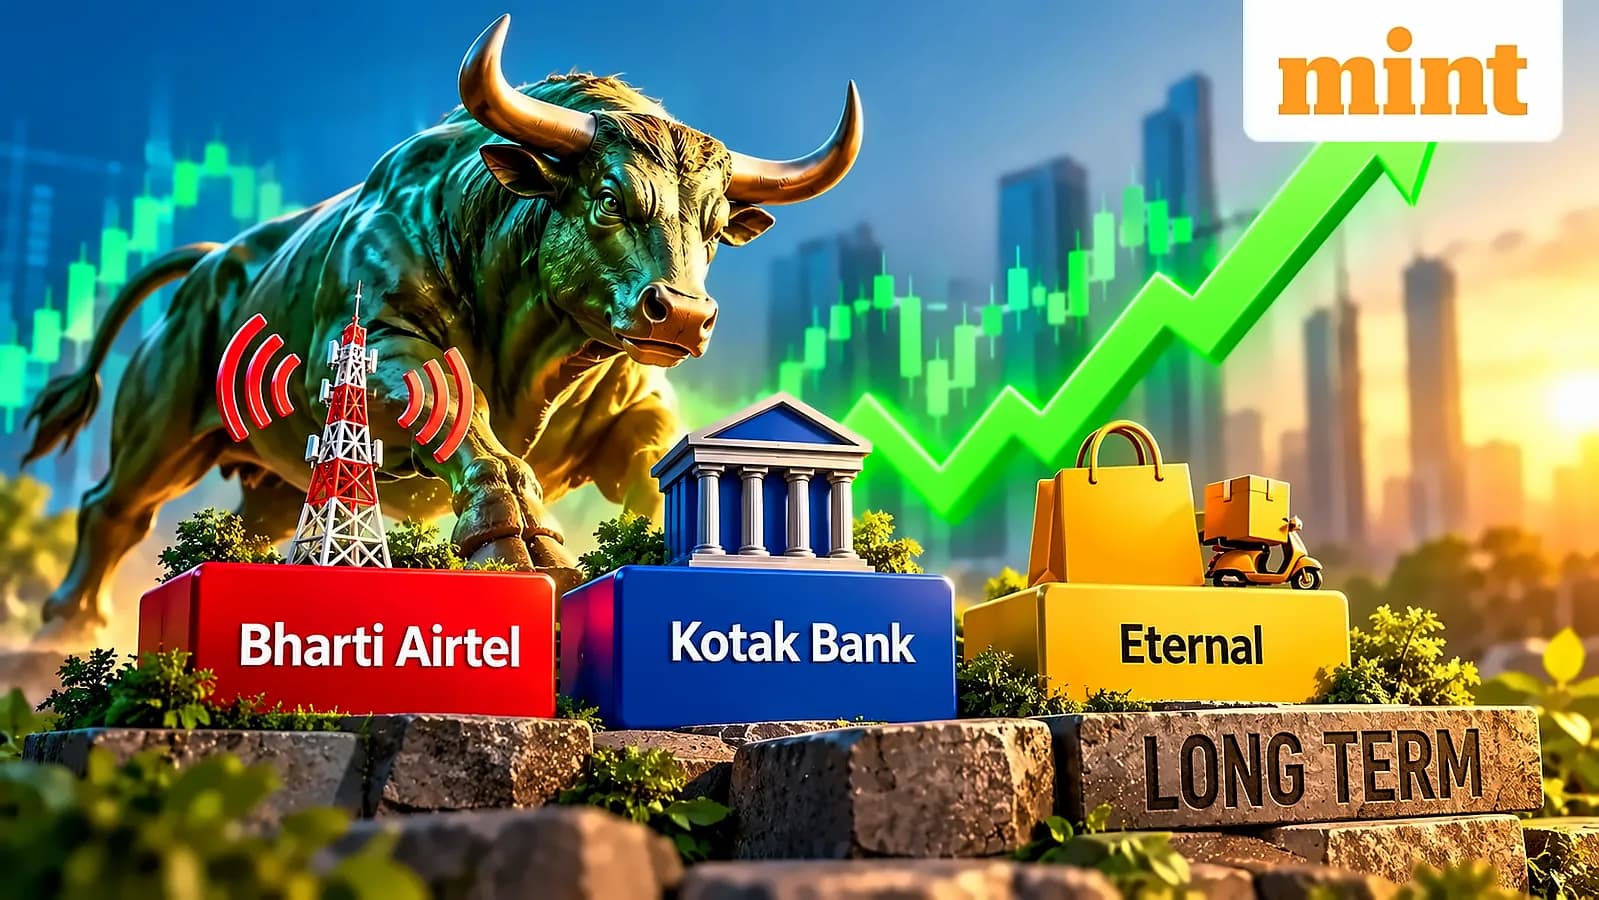
Kotak Mahindra Bank emerges as a top banking pick with a target price of ₹500 against its previous close of ₹439. As reported by Axis Direct, the bank is positioned to deliver nearly 17% loan CAGR over FY26–29E, supported by secured lending strength and the Deutsche Bank India retail acquisition. The bank maintains healthy fee income and expects sustainable 2%+ RoA over the medium term. LG Electronics India also features prominently with both experts recommending it, with Ventura setting a target price of ₹2,141 versus Axis Direct's ₹1,965*. The company's management remains optimistic about mid-teen revenue growth and early double-digit EBITDA margins for FY27.
Bharti Airtel receives strong analyst backing with a target price of ₹2,530 against its previous close of ₹1,806.50. According to Axis Direct, the company's strong subscriber gains and ARPU momentum drive the positive outlook, while the company continues expanding its 139,000 km optical fibre backbone and integrating AI platforms. Ventura's Vipul Organics pick shows revenue growth from ₹175 crore in FY26 to ₹453 crore by FY29E, with EBITDA margin improving from 9.8% to 13.9%. The company's growth is driven by Sayakha capacity expansion and higher-value speciality chemicals.
India's consumer durables market is witnessing an uneven festive-season recovery with premiumisation and weather-led sales supporting select categories. According to The Economic Times, after a sluggish start during Ganesh Chaturthi and Pitru Paksha, demand improved with the onset of Navratri, with sales growing 25-30% year-on-year. Air conditioners have seen a sharp pickup with volumes rising over 60% YoY in recent weeks, while television sales are holding up driven by a shift towards larger screens with select premium categories recording volume growth of 60-100% YoY. However, panel shortages and limited chip availability have pushed television prices up by 22-25%, affecting affordability and delaying replacement purchases.
Park Medi World emerges as a healthcare sector standout with a target price of ₹406 against its previous close of ₹235.55. Ventura projects revenue, EBITDA and PAT CAGR of 26.8%, 28.8% and 33.4% respectively over FY26–FY29E, driven by rapid bed additions and healthy occupancy rates. Dr. Agarwals Health Care is positioned to benefit from organised eye care shift with revenue and EBITDA expected to grow at about 21% and 22% CAGR over FY26–FY29E. Sammaan Capital shows strong recovery potential with AUM expected to grow from ₹53,160 crore in FY26 to ₹1,27,880 crore by FY29E, supported by IHC's ₹8,850 crore capital infusion.