Prabhudas Lilladher has issued a buy rating on Jindal Steel with a target price of ₹1,245 in its research report dated October 24, 2026. According to the brokerage's analysis, the stock is currently trading at attractive valuations of 6.3x/5.8x EV of FY28/29E EBITDA. The revised target price represents a slight reduction from the earlier target of ₹1,265, while maintaining the bullish outlook on the steel major.
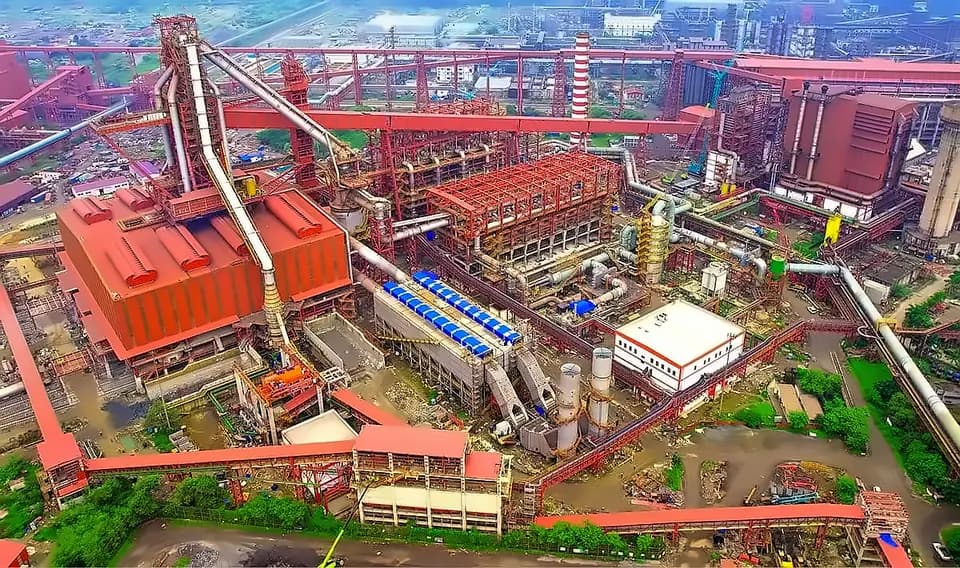
Jindal Steel delivered robust operational performance in Q2FY27, demonstrating strong operational metrics across key parameters. As reported by Prabhudas Lilladher, sales volumes increased 27% YoY, driven by the strong ramp-up of blast furnaces at Angul and inventory liquidation supported by resilient domestic demand. The company maintained Cons NSR at flat QoQ levels, as higher flat product realizations offset weakness in longs along with better performance from global subsidiaries.
Despite facing headwinds from higher raw material costs and ocean freight costs, Jindal Steel maintained strong profitability metrics. According to Prabhudas Lilladher's analysis, adjusted EBITDA per tonne stood at ₹10,522 in Q2FY27. The company successfully implemented a timely switch over to methane from coal gasification plants, which avoided productivity losses during the LPG crisis. Management expects production to ramp up further in H2FY27 with the recent commissioning of the slurry pipeline and ramp-up of other Angul facilities.
Looking ahead, Prabhudas Lilladher has revised its estimates upward, expecting EBITDA CAGR of 25% over FY26-29E. The brokerage has tweaked its FY28/29E EBITDA estimates by 1% each on higher coking coal expectations. At the current market price, the stock offers attractive valuations, with the target price of ₹1,245 based on 7.5x EV of Sep'28E EBITDA valuation methodology.