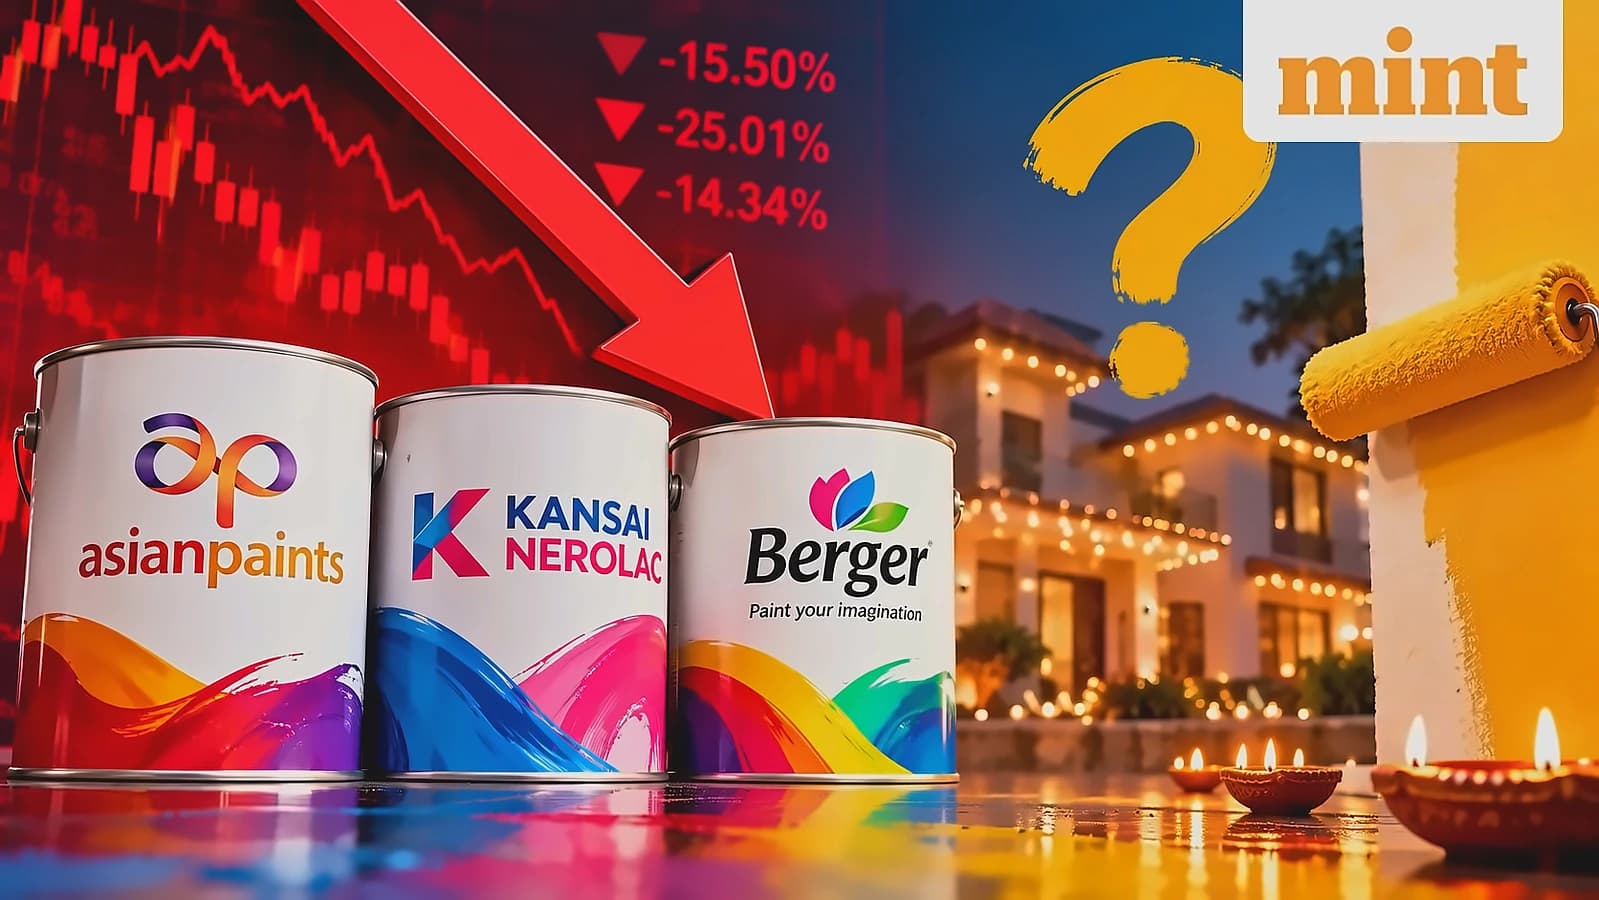
Paint stocks have faced significant pressure this year, with Asian Paints declining 15.5% year-to-date, Kansai Nerolac falling 25.01%, and Berger Paints India dropping 14.34%. According to reports from LiveMint, despite these declines, Elara Securities anticipates signs of recovery with 12-13% revenue growth expected during Q2 FY27. The brokerage maintains an 'Accumulate' rating on both Asian Paints and Berger Paints, recommending investors wait for festive-season demand recovery. With the festive season approaching, investors are watching for signs of a recovery in demand and margins across the sector.
Paint demand remains subdued as dealers work through excess inventory accumulated in Q1 amid softer secondary offtake. As reported by LiveMint, dealer inventory is currently estimated at 2.5-3 months, compared with the normal level of 1.5-2 months. August was particularly weak, though September showed some improvement as dealers began stocking premium paints ahead of the festive season. Primary sales picked up modestly in September, with companies expected to lead growth including Berger Paints with 12.8% revenue growth and Kansai Nerolac growing 12%. Among the companies covered by the brokerage, Berger Paints is expected to lead with revenue growth of 12.8%, supported by an average price hike of around 8%, while Asian Paints' decorative business revenue is likely to increase 10% with volume growth of around 5%.
Competitive intensity remains elevated, with Asian Paints' Neo Bharat having a lower landed price at the dealer level than regular distemper, potentially reversing Q1 mix gains. According to LiveMint, Birla Opus reduced dealer schemes by 5-6% over the past two months, narrowing its dealer margin advantage over Asian Paints to around 5% from nearly 10% earlier. The brokerage expects EBITDA margins to decline by around 70 basis points year-on-year in Q2, primarily due to elevated crude prices, with Asian Paints' margin expected to fall by around 117 basis points. However, Berger Paints is expected to be an exception with EBITDA margin likely to improve by around 50 basis points YoY, helped by a favourable base.
Input costs remain a key concern as Brent crude rose from around $70 a barrel in early July to nearly $97 by the end of September. As reported by LiveMint, Elara Securities expects EBITDA margins to decline by around 70 basis points year-on-year in Q2, with Asian Paints' margin falling by around 117 basis points and Kansai Nerolac's margin dropping by around 49 basis points. However, price hikes taken so far should provide some cushion against the higher input costs. The margin outlook will remain closely linked to crude prices, though Q3 could see some improvement, supported by better growth and a favourable product mix.
The brokerage identifies festive-season demand, dealer inventory normalisation, competitive intensity and crude oil prices as key monitorables for the sector. According to LiveMint, while Q3 could see some improvement supported by better growth and favourable product mix, the margin outlook will remain closely linked to crude prices. Elara Securities said its interactions with paint dealers indicate that demand remained soft through the quarter, with secondary sales yet to show a meaningful improvement. Despite near-term demand and margin pressures, the brokerage maintains its positive outlook on the sector's recovery potential ahead of the festive season.