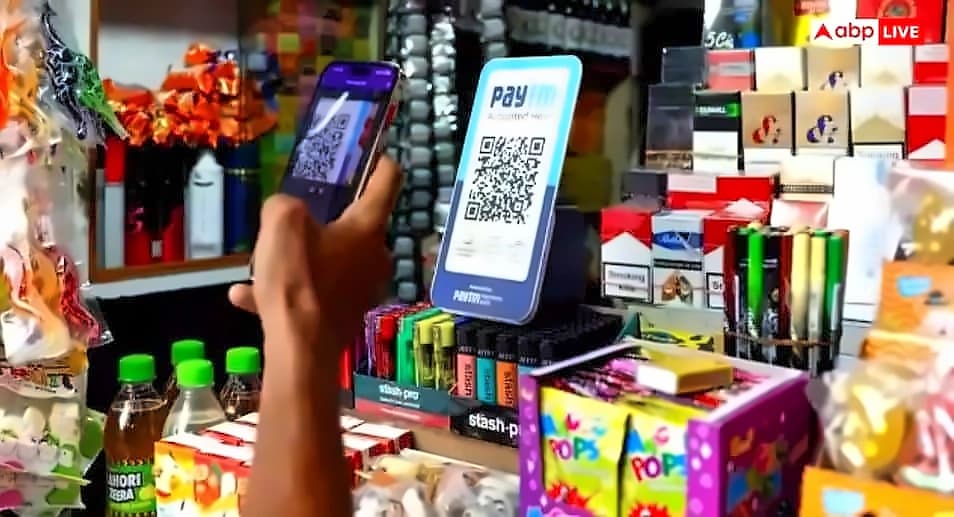
The Reserve Bank of India has introduced a 0.4% Merchant Discount Rate (MDR) on UPI merchant payments exceeding ₹2,000. According to reports from Upstox Securities, this new charge represents a significant development in the digital payments landscape, affecting how merchants process UPI transactions above the specified threshold. The implementation of this MDR structure marks a shift in the cost structure of UPI transactions for merchants and payment companies. UPI charges are changing from October 15, 2026, with the new three-slab MDR structure affecting person-to-merchant (P2M) transactions above ₹2,000, while person-to-person (P2P) transfers remain completely free at any amount. The ₹2,000 threshold is not a universal UPI transaction limit but specifically marks where merchant-side MDR begins to apply, with transactions up to ₹2,000 remaining exempt from MDR charges. A Finance Ministry statement noted that "UPI transactions accounting for 70% of the total transaction value will remain completely outside the MDR framework," highlighting the limited scope of these charges.
The new MDR structure is expected to have significant implications for payment companies operating in the UPI ecosystem. As reported by Upstox Securities, the charge will affect how these companies structure their pricing models and revenue streams from UPI transactions. The implementation represents a change in the cost structure that payment companies must factor into their business planning and operational strategies. This reverses six years of zero-cost UPI for merchants, dating back to 2020 when India made UPI and RuPay debit transactions free to drive adoption. The Finance Ministry explicitly denied plans to introduce UPI charges as recently as mid-2025, making this genuinely new policy rather than a long-standing rule. According to NPCI's FAQ document, MDR on UPI is structured to be much lower than all traditional card-based transaction fees, with standard credit card MDRs typically ranging from 1.5% to 2.5% per transaction and debit card MDRs capped up to 0.90%.
The ₹2,000 transaction threshold for the new MDR applies specifically to UPI merchant payments and represents the exemption line in NPCI's new three-slab merchant MDR structure. According to the reports, this threshold level has been established as the point at which the 0.4% MDR charge becomes applicable. Customers pay nothing under this framework - the responsibility sits with merchants, whose exact costs depend on transaction size, category, and payment method. Transactions up to ₹2,000 account for more than 95% of P2M UPI transactions, making the threshold relevant primarily for merchants rather than consumers. The ₹2,000 figure is not a universal UPI transaction limit or blanket fee threshold, but specifically marks where merchant-side MDR begins to apply. Normal bank-account-to-bank-account UPI between individuals remains entirely unaffected by this number.
The new three-slab MDR structure breaks down as follows: nothing up to ₹2,000, 0.4% between ₹2,000 and ₹75,000, and a flat ₹300 above ₹75,000. As reported by SocioLabs, the math works out cleanly since 0.4% of ₹75,000 is exactly ₹300. UPI charges are calculated on actual transaction value, and providers may flag unusual splitting patterns as irregular. Splitting a single ₹4,000 payment into two ₹2,000 payments doesn't meaningfully help a business, as your total revenue and total MDR exposure don't actually change. According to NPCI's detailed FAQ document, for a ₹3,000 purchase, applying the 0.4% rate results in an MDR fee of ₹12 paid by the merchant to its acquiring bank, while for a ₹50,000 purchase, a 0.4% fee equals ₹200. For high-value purchases, any transaction above ₹75,000 is capped at the fixed ₹300 maximum, regardless of the actual percentage calculation. Different UPI apps (Google Pay, PhonePe, Paytm) charge merchants differently for standard bank-account UPI acceptance - the MDR slabs are set by NPCI uniformly, not by individual apps, though their own commercial service fees may vary. Capital market transactions, including payments towards Mutual Funds, Securities, Stockbrokers, and Dealers, is set at a nominal 0.02% of the transaction value with a maximum capping of ₹300.
The new MDR structure affects businesses differently based on their transaction patterns. Small businesses with mostly sub-₹2,000 transactions see minimal impact - most day-to-day retail payments stay exempt. However, businesses with higher average order values (electronics, furniture, wholesale) will feel the 0.4% or flat ₹300 more directly and should factor this into margin calculations going forward. Settlement and reconciliation processes require attention - businesses should confirm with their bank or aggregator exactly how MDR gets deducted and ensure their accounting correctly reflects it, particularly for GST documentation purposes. Eligible small merchants under the P2PM category can continue receiving zero MDR for transactions up to ₹1 lakh per month through UPI QR codes, covering small retailers, neighbourhood shops and street vendors. Certain essential sectors such as railways, telecommunications, insurance, fuel and agricultural inputs will attract a flat MDR of ₹5 rather than the standard 0.4% rate. Whether small businesses will actually "stop accepting UPI" over this remains to be seen, but the more realistic outcome is businesses adapting their pricing strategies accordingly. The NPCI document notes that "this cost difference helps merchants lower their payment processing expenses while accepting digital transactions," emphasizing the competitive advantage of UPI over traditional card-based payments.