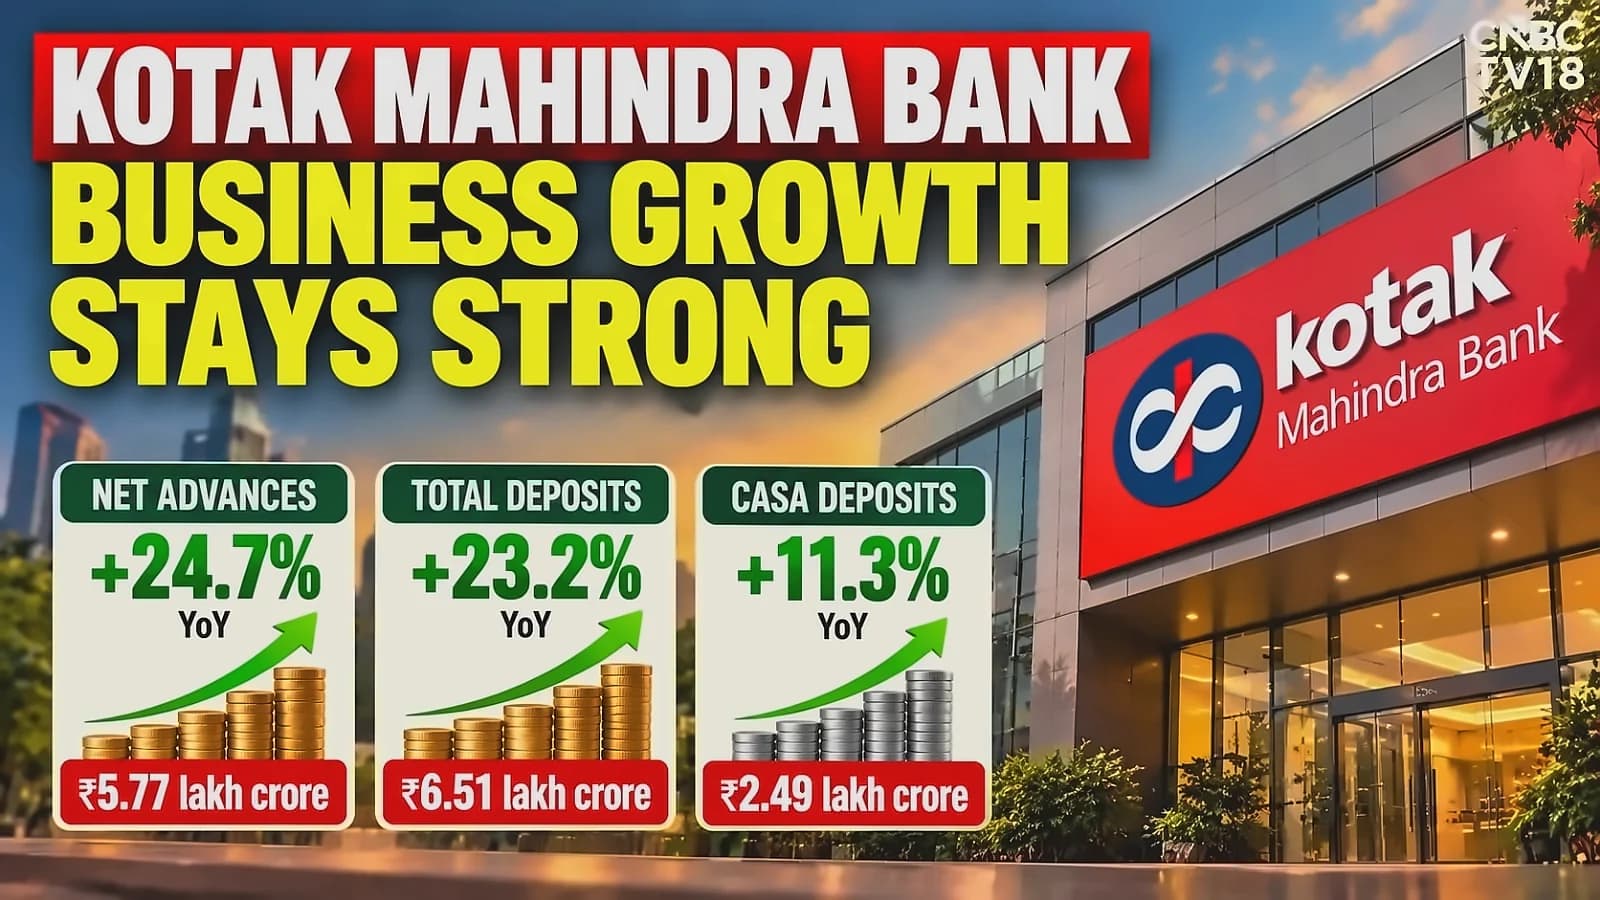
HDFC Bank has overtaken ICICI Bank as the preferred pick in the private banking space following the appointment of Anup Bagchi, with the pecking order among private lenders completely reversed over the past week. According to CNBC TV18, HDFC Bank now claims the top spot, trading at an attractive 1.6 times price-to-book, followed by Kotak Mahindra Bank at 2.2 times and ICICI Bank at 2.5 times. Previously, ICICI Bank served as a safe haven for investors due to its strong execution and expected management continuity, with hopes that the 55-year-old Bagchi would eventually take over and lead for another five years. However, his transition to HDFC Bank has introduced doubt into that continuity, prompting a shift in market preference. The leadership change arrives as the government seeks to curb internal infighting at HDFC Bank—evidenced by Rajiv's board appointment—while preserving the institution's private-sector character.
Bagchi brings over 34 years of comprehensive banking experience to his new role, having worked across multiple critical areas including treasury, wholesale banking, capital markets (leading ICICI Securities), insurance, corporate banking, liabilities and retail operations. As per Mint, those who know the veteran banker from his days at ICICI Bank describe him as the strategist the bank needs today to mop up deposits, drive growth, raise current account and savings account (CASA) deposits and fire up the net interest margins. His experience during ICICI Bank's digital and technology journey may prove particularly valuable for HDFC Bank's digital transformation efforts. According to NDTV Profit sources, Bagchi's extensive exposure to retail banking and technology, as well as his ability to stay closely involved in operations and drive execution, were key strengths that set him apart from other candidates during the assessment process. Bagchi served as executive director of ICICI Bank from 2017 to 2023, overseeing retail, business, and rural banking, and subsequently wholesale banking, where he played a key role in strengthening the bank's retail franchise and successfully navigated the demonetisation period with limited business disruption. The RBI has approved Bagchi's appointment for a three-year term beginning October 27, 2026, marking a significant leadership transition for the private sector lender.
HDFC Bank reported robust growth in Q2 FY27, with period-end gross advances rising 16.3% year-on-year to approximately ₹32.20 lakh crore as of September 30, 2026, compared with ₹27.69 lakh crore a year earlier. As reported by The Economic Times, the bank's average deposits stood at ₹31.67 lakh crore during the September 2026 quarter, up 16.8% from ₹27.11 lakh crore in the corresponding period last year. Average CASA deposits rose 10.7% YoY to ₹9.71 lakh crore from ₹8.77 lakh crore in the September 2025 quarter, showing sequential improvement in low-cost deposit mobilization. The bank's underlying deposit growth remained strong at around 15% YoY, excluding FCNR deposits, while underlying loan growth moderated to 14.3%, excluding FCTL, and remained slower than the system. According to Macquarie's latest report, HDFC Bank's Q2FY27 pre-quarter update showed moderate AUM growth of 15.3% year-on-year and 5.8% quarter-on-quarter, trailing peers, while deposits rose 18.8% YoY and 4.9% QoQ, boosted by $11.5 billion in FCNR inflows. The report noted that growth remains skewed towards term deposits and CASA is weak, with CASA averaging 10.7% YoY and 1.5% QoQ and period-end CASA showing growth of 10.8% YoY and 2.6% QoQ.
Multiple brokerages have issued positive ratings on HDFC Bank following Bagchi's appointment, citing the removal of management succession overhang as a key catalyst. Morgan Stanley maintains an 'Overweight' rating with a target price of ₹1,025, noting that the CEO succession issue had been a drag on the stock, which has underperformed the BSE Bankex index by 19 percentage points on a year-to-date basis. Jefferies maintained its 'Buy' rating with a target price of ₹970, implying an upside potential of around 35%, following Bagchi's appointment as MD & CEO for three years from October 27. The brokerage described the appointment as strategically positive and said it could support a re-rating, identifying execution, strategic direction and continuity of Kaizad Bharucha as key factors. Citi retained its Buy rating with a target price of ₹970, implying an upside potential of around 35%, following the appointment. JP Morgan believes the appointment of an external candidate as CEO is a positive inflection point, maintaining an 'Overweight' rating with a target price of ₹990, while noting that HDFC Bank shares trade at around 25% discount to ICICI Bank. Motilal Oswal Financial Services maintains a 'Buy' rating with a target price of ₹925, implying an upside of 28% from the previous close of ₹721, expecting the bank's operating performance to improve from FY28E onward. Prabhudas Lilladher has also joined the positive chorus, recommending a 'Buy' rating with a target price of ₹950, maintaining their multiple at 1.9x on March 2028 core adjusted book value. Emkay Global Financial has now joined the bullish chorus, recommending a 'Buy' rating with a target price of ₹1,225, noting that the prolonged underperformance of HDFCB shares has made the valuation attractive and the stock should see a sustained re-rating as the new leadership delivers on key priorities. According to Bloomberg data, the bank currently has 47 buy ratings and two holds, with a 40.1% return potential, with over the past week receiving 14 'buy' ratings and five 'outperform' ratings from 21 brokerage firms.
HDFC Bank shares fell 2.16% even as banking indices gained, closing at ₹705.65 despite the broader market recovery. As per Business Standard, the country's largest bank by market capitalisation closed at ₹705.65, even as it had 47 buy ratings and two holds, with a 40.1% return potential. The stock has fallen 28% in 2026, underperforming the Nifty 50, which is down 14% this year. According to The Economic Times, HDFC Bank shares rose 2% to ₹734.20 in early trade before erasing all gains and falling nearly 3% from the day's high to ₹714 as of 10:20 am. The decline came even as the broader market rebounded after an eight-week losing streak. On short-term charts, price action has comfortably settled above the 20-day and 50-day SMAs, reconfirming positive momentum, with both daily and weekly Relative Strength Index (RSI) indicators crossing into positive territory after rebounding from oversold zones. Market indicators suggest the current relief rally could extend toward the ₹760–785 target zone, with immediate downside support established at ₹700–705, according to technical analysts. Sudeep Shah from SBI Securities sees the stock finding immediate resistance in the ₹755–760 zone, which coincides with the 20-week EMA, while Rs 685–680 is likely to act as the next key support zone. The company currently has a market capitalisation of more than ₹11 lakh crore.
ICICI Securities has joined the bullish chorus on HDFC Bank, recommending a 'Buy' rating with a target price of ₹920 in its research report dated October 04, 2026. The brokerage maintains its BUY rating with an unchanged target price of ₹920, valuing the stock at ~1.8x FY28E ABV. According to ICICI Securities, the appointment of a credible banker with longevity could ease the protracted overhang on the stock and allow an opportune strategic reset. While the franchise remains strong, the successor must steady the ship by rebuilding stakeholder confidence and revisiting priorities. The agenda likely includes bridging execution/communication gaps while galvanising an ~0.2mn-strong workforce. After enjoying leadership on growth, CoF and RoE, HDFCB now stands at the private banks' average. Bagchi's vision and progress towards managing the growth–profitability conundrum, regaining its tech/CoF competitiveness and reviving retail/CASA growth while sustaining AQ would be keenly watched to assign premium/discount vs peers. The macro backdrop, with hardening rates, seems supportive for the bank's prospects. Meanwhile, Macquarie retained an 'outperform' rating (target price of ₹875) and noted that while the incoming CEO may have a clear mandate to reinvigorate loan growth, particularly in the retail portfolio, and reclaim deposit market share, with a sharper focus on rebuilding the CASA franchise.