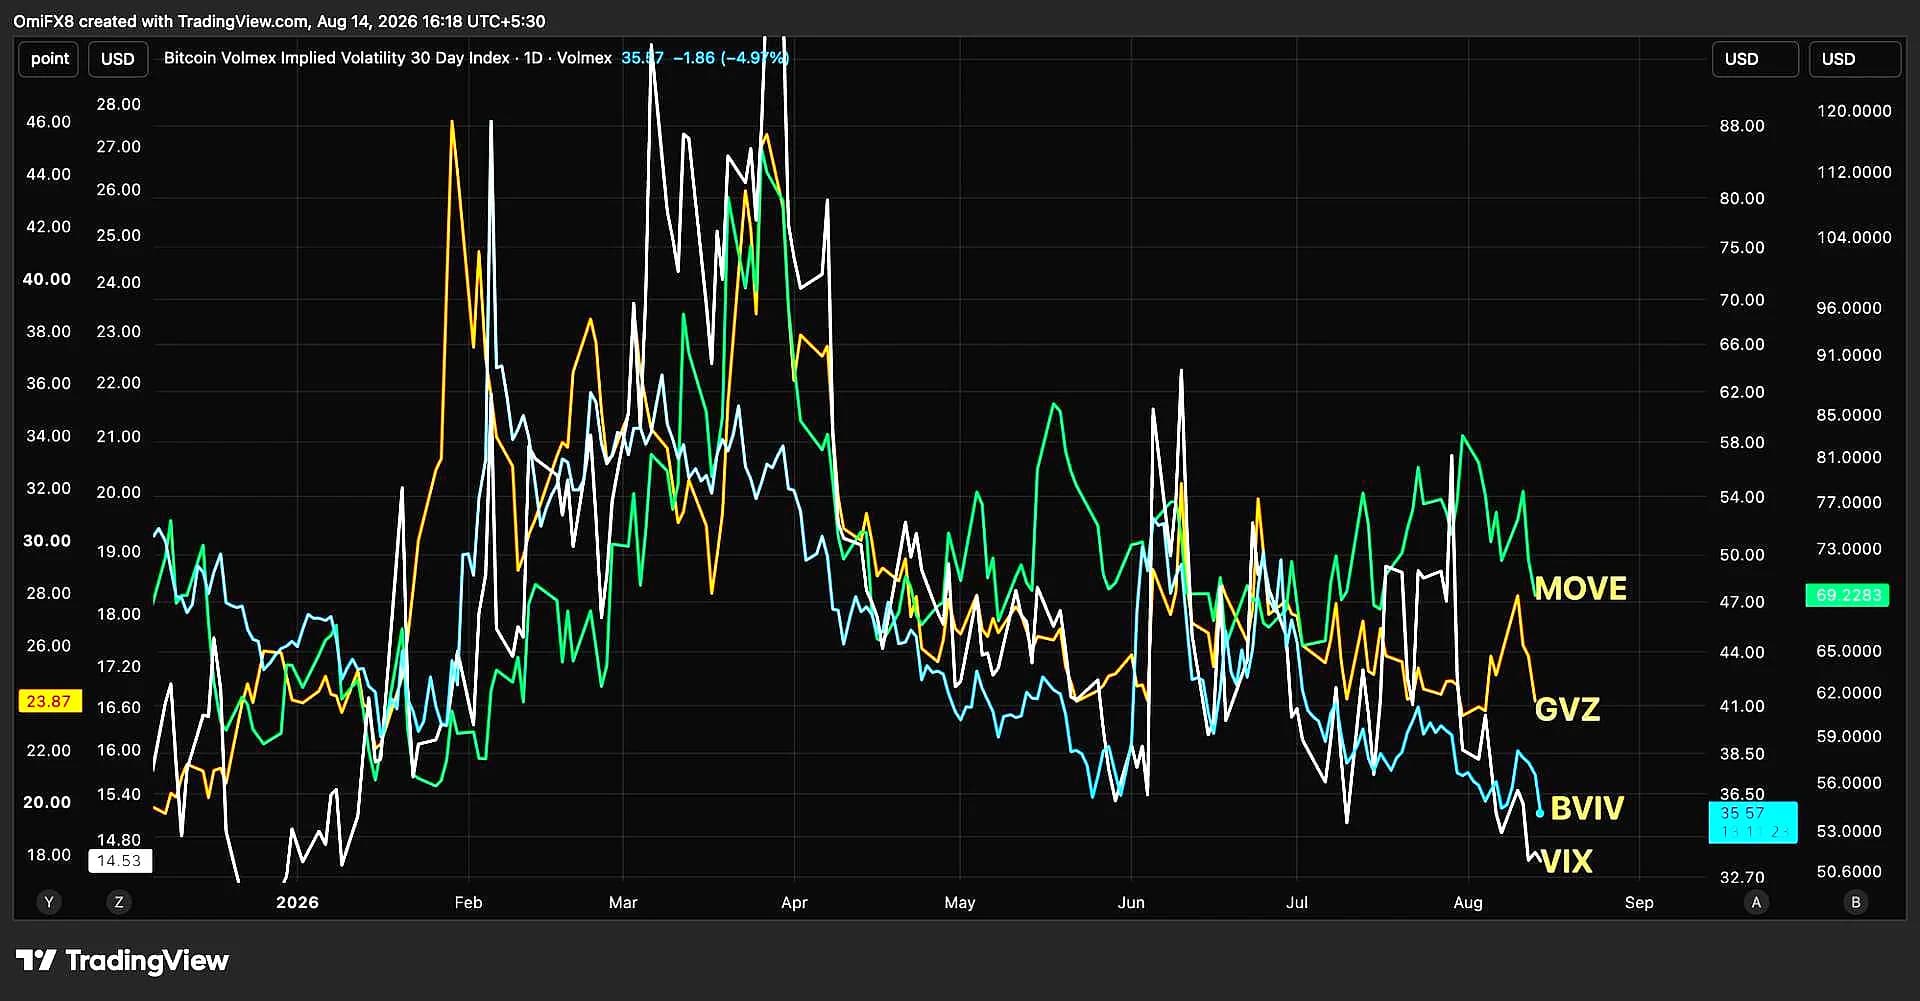
Bitcoin's options market has shown a dramatic shift toward defensive positioning as traders seek protection against potential further declines. According to Glassnode, Bitcoin's 25-delta options skew climbed from 5.2% to 8.6% over the preceding week, reflecting a growing premium for downside protection relative to bullish options. The implied-versus-realized volatility spread shifted from -3.8% to +2.1% over the week, indicating that volatility embedded in options prices moved above the cryptocurrency's recent realized volatility. This change reflects a market increasingly willing to pay a premium for exposure to potential future price swings after a period of comparatively restrained trading activity.
Despite the defensive options positioning, leveraged futures traders continue maintaining bullish exposure amid persistent spot selling. As reported by Glassnode, aggregate funding payments by perpetual futures longs jumped 49.4% to $1.6 million, suggesting continued demand for leveraged bullish exposure despite weak buying activity in the underlying market. This divergence leaves Bitcoin exposed to renewed volatility if spot selling persists and leveraged traders are forced to reduce positions, particularly as investors prepare for another Federal Reserve interest-rate decision later this month. The contrasting positions emerged as Bitcoin struggled to recover from October's selloff, with the cryptocurrency trading near $81,481 at press time, about 1.3% below Monday's level.
The current market dynamics reveal a significant gap between options pricing and actual price performance. According to recent analysis, the options market is pricing Bitcoin volatility at 38.3% annually, while the price has recently delivered 20.2% volatility over the past two weeks. This 18-point gap suggests that options traders are anticipating more volatile conditions than the current market has experienced. The 38.3% figure comes from Deribit's volatility index (DVOL), which measures volatility traders are paying for through option prices over the next 30 days. This gap analysis provides insights into potential market direction into mid-November, particularly for leveraged positions and the upcoming October 30 expiry.
The defensive positioning comes as the overall options market continues expanding significantly. According to Glassnode, Bitcoin options open interest rose 3.1% to $38.6 billion from $37.4 billion the prior week, suggesting outstanding derivative positions continued to expand despite weak spot market momentum. When including options on crypto-native platforms, the figure rises to roughly $76 billion. ETF options alone represent about 47% of the bitcoin options market, which is mainly owned by Deribit. IBIT options have tripled since January 2025, when open interest was about $11 billion. The growing use of options is reflected in BlackRock's expanding bitcoin-related fund lineup, with the company introducing the iShares Bitcoin Premium Income ETF (BITA) and filing for a bitcoin buffer ETF that uses options to limit losses.