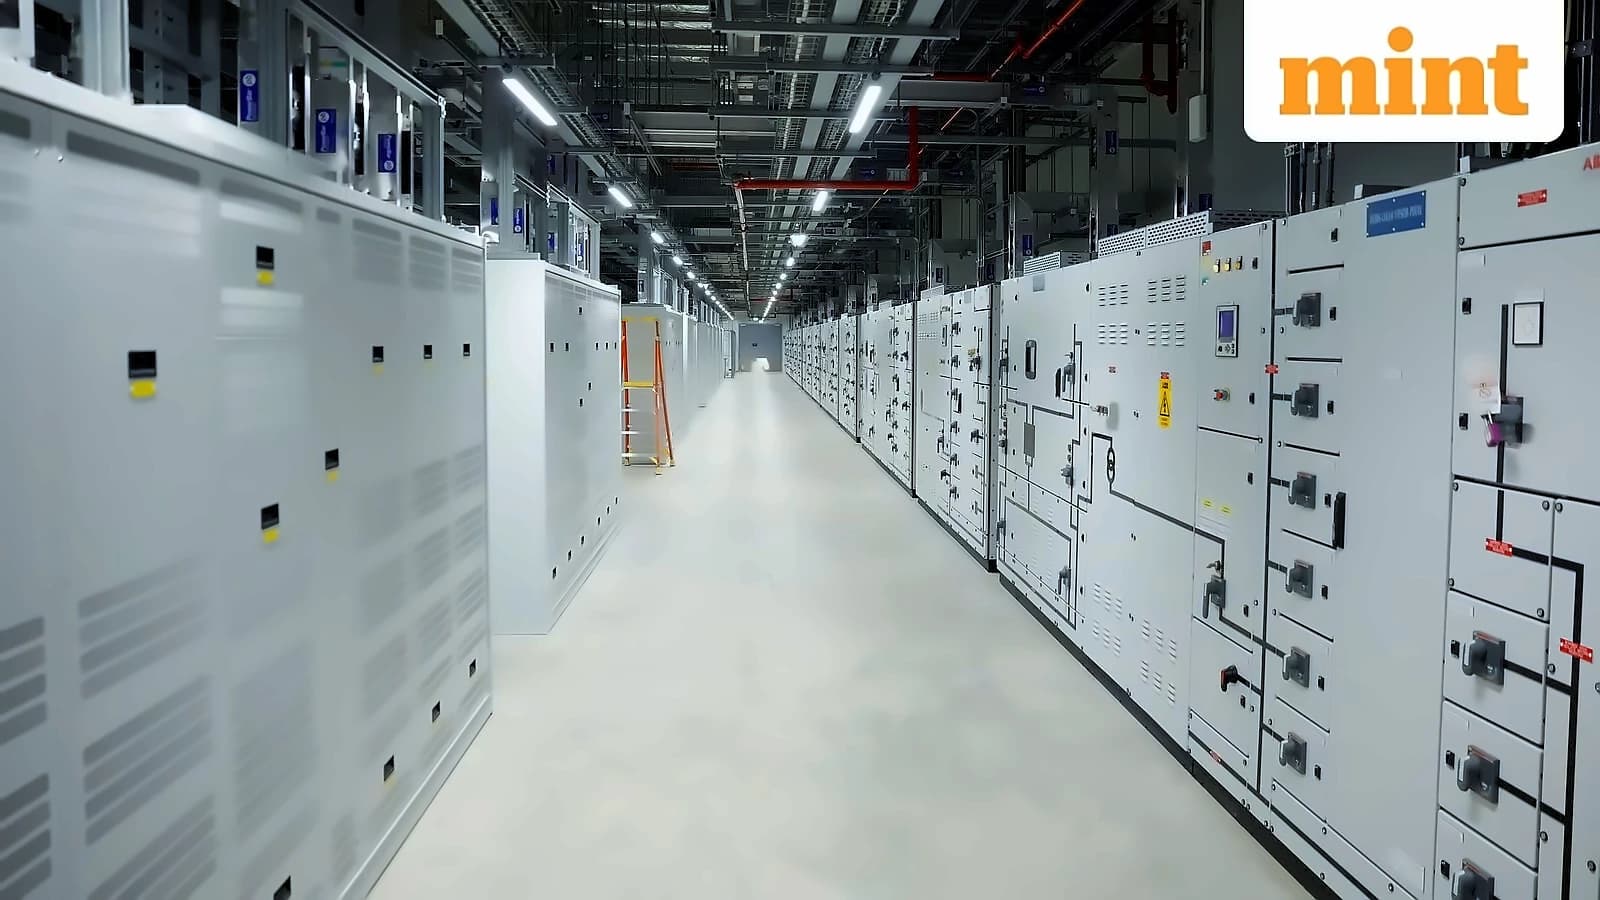
India's data centre capacity is set to more than double by 2030, promising a multi-billion-dollar opportunity for wires and cables manufacturers. But for Polycab India and R R Kabel, the story is more about potential than immediate profit. Both companies see data centres as a long-term opportunity, yet neither has quantified a significant order book from this segment today. The real drivers of their recent performance are domestic demand, copper prices, and operational efficiency—not hyperscale build-outs.
The Data Centre Opportunity: Size and Reality
India's operational data centre capacity stood at approximately 1.8 GW in the first half of 2026, with another 3.9 GW under construction or planned. Full delivery of this pipeline could take capacity to 5.6 GW by 2030, more than tripling the current base. Another report projects capacity reaching about 5 GW by 2030, backed by nearly $30 billion in cumulative investment commitments.
Polycab India management estimates the total data centre cable market at INR 20,000–25,000 crore, spread over roughly 6–8 years. The company assumes about INR 3.5 crore of cable per MW, split 50–60% between conventional cable and optical fibre. That's meaningful, but small next to Polycab's quarterly revenue of INR 9,987 crore in Q2 FY27. Transcript +2
R R Kabel is even more cautious. Management describes data centres as still in the "announcement phase rather than execution." The company has started receiving a few orders for conventional cables, but data centre cables remain a very small share of revenue. Transcript +1
Why Hyperscale Data Centres Need More Cable
Hyperscale data centres, driven by artificial intelligence and cloud computing, require higher power densities. This places greater demands on power distribution, backup systems, and thermal management. High-bandwidth fibre is equally critical to move data between compute, users, and global networks.
This technical profile suggests more low-voltage and medium-voltage power cabling per facility, plus substantial optical fibre. However, neither company discloses cable density per square foot. The general logic is that larger, more power-intensive campuses need more cable, but this hasn't yet translated into distinct, quantified orders.
Strategic Moves: Optical Fibre and High Voltage
R R Kabel made its entry into optical fibre through the acquisition of U M Cables, a wholly-owned subsidiary of Usha Martin, for INR 77 crore in September 2026. The deal provides ready manufacturing assets, existing approvals, and an operating track record, shortening the time to build these capabilities organically. However, the target's turnover has declined from INR 135.34 crore in FY24 to INR 78.19 crore in FY26. The company has not disclosed specific plans to serve hyperscale data centres or 5G fiberization through this acquisition.
On the power side, R R Kabel can already manufacture cables up to 66 kV. Its INR 1,200 crore capex plan aims to reach 220 kV, with about 80% of the spend directed toward cables. Higher-voltage capability positions the company to supply power feeds to large campuses, but management has not explicitly tied this expansion to data centres. Transcript +1
Polycab India is building an Extra High Voltage (EHV) facility in Halol, Gujarat, with a technology know-how agreement with Brugg Cables of Switzerland for systems up to 550 kV. Commissioning is now expected in FY28, delayed from earlier targets. This plant targets utility transmission and underground cabling in Tier 1 and 2 cities, not data centres directly. Management notes that about 50% of domestic EHV consumption is currently imported, representing a ready market. Transcript +2
Q2 FY27 Performance: Growth, Margins, and Mix
Both companies delivered strong growth in Q2 FY27, but the drivers were largely domestic and copper-related, not data centres.
R R Kabel reported revenue of INR 3,284 crore, up 52% year-on-year. Wires and Cables segment profit before tax and interest rose 57% to INR 282 crore, driven by volume growth, higher realizations, and operating leverage. Exports contributed 32% of revenue, up from 27% a year earlier. Investor Presentation +2
The FMEG (fast-moving electrical goods) segment, however, remains loss-making. The H1 FY27 loss margin narrowed to -2.2% from -4.5% a year earlier, with a loss of INR 124 crore against INR 188 crore in H1 FY26. Management targets operating breakeven for FY27. Investor Presentation +1
Polycab India grew revenue 53% to INR 9,898.9 crore, with net profit up 43% to INR 990 crore. EBITDA margin, however, declined to 14.4% from about 15.8% a year earlier [stock_agent]. The Wires and Cables segment delivered an EBIT margin of 14.2%, while the EPC business reported a 7.2% margin, down sharply from 18.1% a year earlier. Investor Presentation +2
It warns that margins will "normalize to a certain level" over the longer term, with a long-term guidance range of 11–13% for Wires and Cables. Transcript +2
Capital Efficiency and Valuation
Both companies demonstrate strong capital efficiency. Polycab India reported ROCE of 35.73% and ROE of 24.81% for FY26, while R R Kabel showed ROCE of 32.26% and ROE of 20.83% [stock_agent]. These figures exceed the industry averages I could verify, though specific industry ROCE and ROE benchmarks were not available in the data.
R R Kabel improved its net working capital days to 46 at September 2026 from 50 at June 2026, driven by higher creditor days. This efficiency helps fund capacity expansion, but internal accruals alone may not cover the INR 600–650 crore capex planned for FY27. Borrowings have risen from about INR 232 crore at March 2026 to about INR 473 crore at September 2026. Investor Presentation +2
Polycab India maintains a net cash position of INR 4,520 crore and reported net working capital of just 11 days on an average basis in Q2 FY27. Investor Presentation +1
Valuations remain rich. Polycab India trades at a P/E of 36.45x, and R R Kabel at 35.80x, both well above the Capital Goods sector average of 20.15x [stock_agent]. I could not verify the three-year median P/E figures or the 23.3x industry average cited in the query. The premium reflects strong growth and returns, but it also assumes margin sustainability and continued execution.
Export Exposure and Global Data Centre Demand
R R Kabel is a major exporter, with sales to 67 countries and an export share of 32% in Q2 FY27. Management says export margins are lower than domestic margins but are improving on a shift toward cables and higher-value wires. The US data centre opportunity is described as "very big," but the company is still onboarding customers and faces tariff uncertainty. Investor Presentation +4
Polycab India has a smaller export footprint at 5% of revenue in Q2 FY27, but management targets above 10% by FY30. The company reports "definite demand" from US data centres, AI, and energy transformation, sold through its institutional business. However, it cannot trace where its cables end up in the end market. Investor Presentation +2
Export dynamics differ significantly from domestic opportunities. R R Kabel's exports are distribution-led and concentrated in Europe and the Middle East, which accounted for 75–80% of export revenue in Q2 FY26. Polycab's exports are more institutional and project-based. Order sizes, customer concentration, and margin profiles vary widely across markets, but neither company discloses export-specific margins or order books. Transcript
Execution Risks and the Path Ahead
The conversion of announced data centre projects into actual revenue faces several risks. Project slippage of 1–2 years is a real possibility, as analysts have noted. Polycab India has already experienced delays, with its EHV plant commissioning pushed to FY28 and EPC revenue fluctuating due to project timing. Transcript +1
For R R Kabel, the UM Cables acquisition presents integration challenges. The target's declining turnover must be stabilised before it can contribute meaningfully. The company has not disclosed an FY28 ramp-up plan for this facility.
Volume guidance also depends on broader market trends. R R Kabel expects about 18% volume growth for FY27, with H2 historically stronger. Polycab guides volume growth at 1.5x market growth through FY30 but has flagged a high base in Q3. Transcript +3
Ultimately, data centres represent a promising tailwind, but they are not yet a material driver of revenue or margins for either company. The near-term story remains domestic growth, operational efficiency, and managing through copper volatility. The data centre opportunity is real, but it will unfold over years, not quarters.