Mahindra & Mahindra delivered exceptional financial results for the September quarter, with consolidated profit after tax (PAT) rising 30% year-on-year to ₹5,100 crore, making it the first carmaker to report net-profit growth during the September quarter. According to Mint, the company's consolidated revenue from operations grew 25% year-on-year to ₹57,553 crore from ₹46,101 crore in Q2 FY26. The results reflect the company's continued focus on expanding its market presence and operational efficiency, with the automotive segment driving significant growth in profitability. For the half year ended September 30, 2026, consolidated PAT stood at ₹10,042 crore, up 29% year-on-year, while consolidated revenue grew 26% to ₹1,15,741 crore. The Board of Directors approved the unaudited financial results on November 5, 2026, with Return on Equity (annualized) standing at 21.0%. As per Mint, the surge in profit came after both market leader Maruti Suzuki and the country's fourth-largest carmaker Hyundai Motor India reported steep drops in profits due to rising commodity prices, with Maruti Suzuki reporting a 26% drop to ₹2,466 crore and Hyundai Motor India recording a 24% decline to ₹1,196 crore.
The quarter showed mixed performance across M&M's auto and farm segments, with farm EBIT margin standing at 16.8%, declining 176 basis points quarter-on-quarter, while auto EBIT margin came in at 7.7%, improving 58 basis points quarter-on-quarter. According to The Hindu BusinessLine, this mixed performance contributed to the overall strong consolidated results despite challenges in specific segments. The farm equipment segment reported a 9% decline in consolidated PAT to ₹1,053 crore, with revenue declining 6% to ₹9,572 crore during the quarter due to a deficit monsoon and delayed festive season. The farm segment contributed 30% of FY28CL EBIT, meaning a 5% swing in tractor volumes would have less than a 2% impact on the sum-of-the-parts valuation, as noted by CLSA. The farm business responded by refreshing its product line, adjusting prices, accelerating exports, and exiting certain international markets to address headwinds from inflation, monsoon deficit, and sharp drop in global demand. Jefferies noted that M&M derives 30-40% of its EBIT from farm division, with the tractor industry experiencing a 15% decline in September-October amid below-normal rains and high base. M&M's management has also decided to cut its FY27 tractor sales outlook to flattish growth levels, while experts predict overall volumes are likely to decline 3% in the current fiscal year.
The market responded positively to M&M's quarterly earnings announcement, with shares surging 5% to a high of ₹3,283.80 on the National Stock Exchange following the results disclosure. As reported by ET Now, the brokerage house remained positive on the stock as earnings were in line with expectations, with core revenue being 1% above and EBIT 2% below house estimate. Goldman Sachs maintained a 'Buy' rating and raised its target price to ₹3,850 from ₹3,700, while Elara Capital reiterated a 'Buy' rating but cut its target price to ₹4,130 from ₹4,578. The Hindu BusinessLine reports that CLSA maintained its high-conviction outperform rating with a target price of ₹4,650, noting that M&M is trading at 15 times FY28CL EPS, compared with its 10-year average price-to-earnings multiple of 17 times. Citi maintained its buy rating with a target price of ₹4,330, noting that the second-quarter performance was ahead of expectations, driven by better-than-estimated EBITDA margins. Bernstein maintained its outperform rating with a target price of ₹4,100, highlighting that M&M's wider earnings base proved valuable during the quarter, with contributions from businesses beyond the standalone auto and farm franchises helping the group sustain growth. Jefferies maintained its 'Buy' rating with a target price of ₹4,000, implying 23% upside from the current price of ₹3,256, while Motilal Oswal maintained its 'Buy' call with a target price of ₹3,850, implying 18% upside. Friday's rally comes after a 6% surge on November 5, right after the company posted its Q2 results on the stock exchanges, with trading activity surpassing 61.15 lakh equity shares as of noon deals.
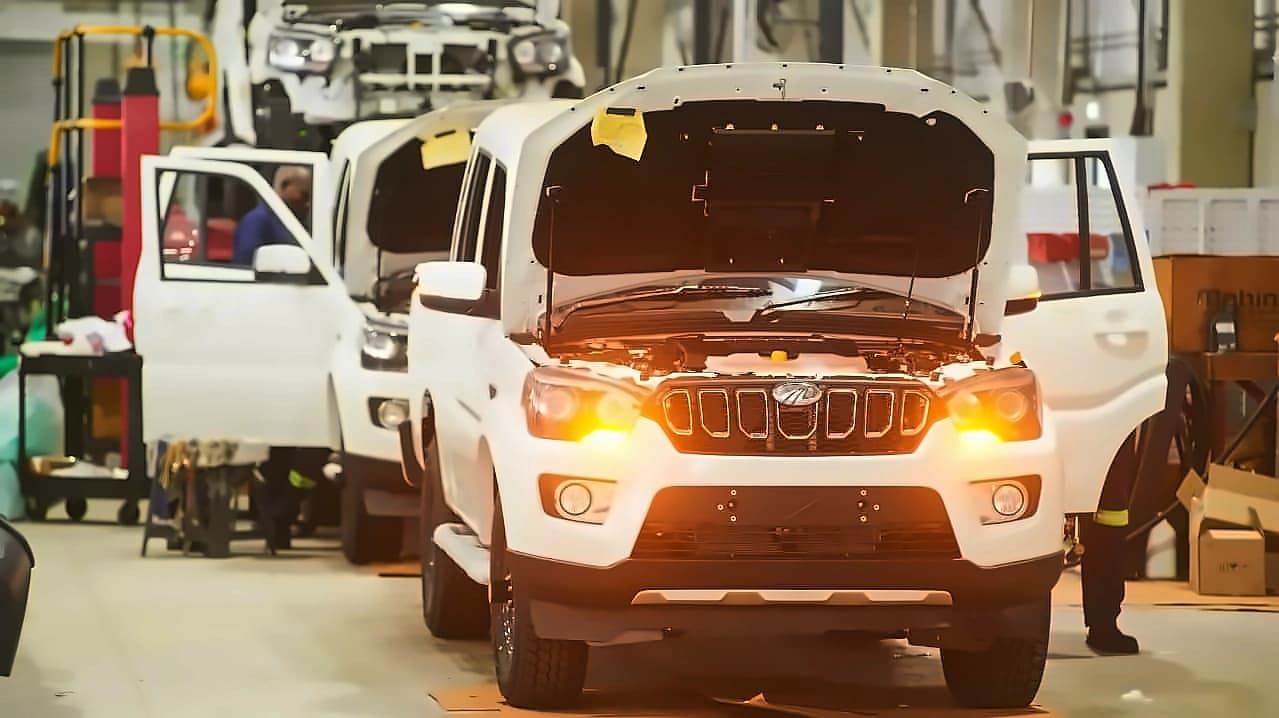
The automotive segment was the primary growth driver, with sales of passenger vehicles growing 26% year-on-year to 183,000 units during the quarter. According to Mint, M&M's automobile volumes rose 26% year-on-year to 330,896 vehicles during the quarter, including sales by subsidiaries. Utility vehicle volumes stood at around 183,000 units, with Mahindra holding a revenue market share of 24.3% in the SUV segment, retaining the number one position. The company also crossed one lakh cumulative electric SUV sales since launch, demonstrating strong momentum in the electric vehicle segment, with the electric SUV portfolio commanding a revenue market share of 30.1% during the quarter. NDTV Profit reports that SUV volumes grew 25% year on year, with the company selling 3.31 lakh vehicles during the quarter, an increase of 26% from a year earlier. The automobile business reported standalone profit before interest and tax (PBIT) of ₹2,614 crore, up 15% year-on-year, though the standalone PBIT margin stood at 7.7%. The share of profit from associates and joint ventures contributed ₹470 crore to the bottom line. To capitalise on growth, the company plans to launch four new models by June 2027, including an all-new electric vehicle, a passenger pickup truck, a model refresh, and a brand-new vehicle built on its latest NU_IQ platform. Jefferies expects passenger vehicle industry volumes to grow at 10% CAGR over FY26-29, with SUVs growing faster at 13%, noting that M&M's registration market share has more than doubled since FY21 to 13%.
Management has guided for mid-to-high teen SUV volume growth for M&M in FY27, with five new product launches planned by June 2027. According to Mint, the company plans to undertake several key initiatives across businesses to deliver strong growth in profits despite inflationary pressures. Anish Shah highlighted that the company is taking actions on pricing, hedging, product mix, and diversifying the supplier base. The farm business responded by refreshing its product line, adjusting prices, accelerating exports, and exiting certain international markets to address headwinds from inflation, monsoon deficit, and sharp drop in global demand. Despite current challenges, the company remains optimistic about future performance, with oil prices having come down in the past 24 hours providing additional hope for improved conditions in the third quarter. Motilal Oswal has increased its earnings estimate for FY27/FY28 by 7.5% each on account of better-than-expected segmental margins and higher other income. The brokerage believes that on the back of its healthy launch pipeline and positive consumer sentiment, management provided a strong outlook for FY27E across segments: M&M utility vehicle at mid-to-high teens, and the light commercial vehicle industry at double digits. Citi noted that management's outlook on utility vehicles remains positive, with volume growth expected to be supported by capacity expansion and new launches, while also highlighting an improving demand outlook for light commercial vehicles. Jefferies expects M&M's total auto volumes rising at 12% CAGR over FY26-29, with the automaker's first SUV on new NU-IQ platform planned for the first half of 2027. Market experts predict that upcoming launches, strong traction in electric vehicle segments, ongoing capacity expansion will power the company's growth despite cost pressure in the market.