Mahindra & Mahindra shares rallied 10.3% in three trading sessions following robust Q2FY27 results that exceeded expectations. The automaker delivered strong financial performance with standalone revenue rising 27% year-on-year to ₹42,477 crore, powered by 16% growth in volumes and 9% rise in realisations. The automotive business was the largest contributor, with revenue rising 36%, aided by a 26% increase in SUV volumes to 183,000 units. Mahindra retained its leadership in the SUV segment with a revenue market share of 24.3% and maintained its FY27 SUV volume guidance at the mid-to-high teens. The electric SUV business also gained traction with a 30.1% revenue market share, while the company plans five major product launches by June 2027, including a vehicle on its new NU_IQ platform and an all-new electric SUV.
Despite strong revenue growth, profitability remains a concern with standalone gross margin contracting 360 basis points year-on-year to 20.8%. EBITDA increased only 1.1% to ₹4,913 crore, with the EBITDA margin declining 300 basis points to 11.6%. Operating profit margins at the standalone level stood at 11.7% in Q2, slipping 290 basis points year-on-year and 54 basis points quarter-on-quarter. Commodity inflation, particularly in steel, copper and rubber, limited the benefits of higher automotive volumes. Mahindra has implemented price increases of about 5% in automotive and 4% in farm equipment to offset these pressures, with operating profit margins for the automobile segment expanding to 9.8% in Q2, compared with 8.9% in Q1, aided by favourable mix and cost efficiencies.
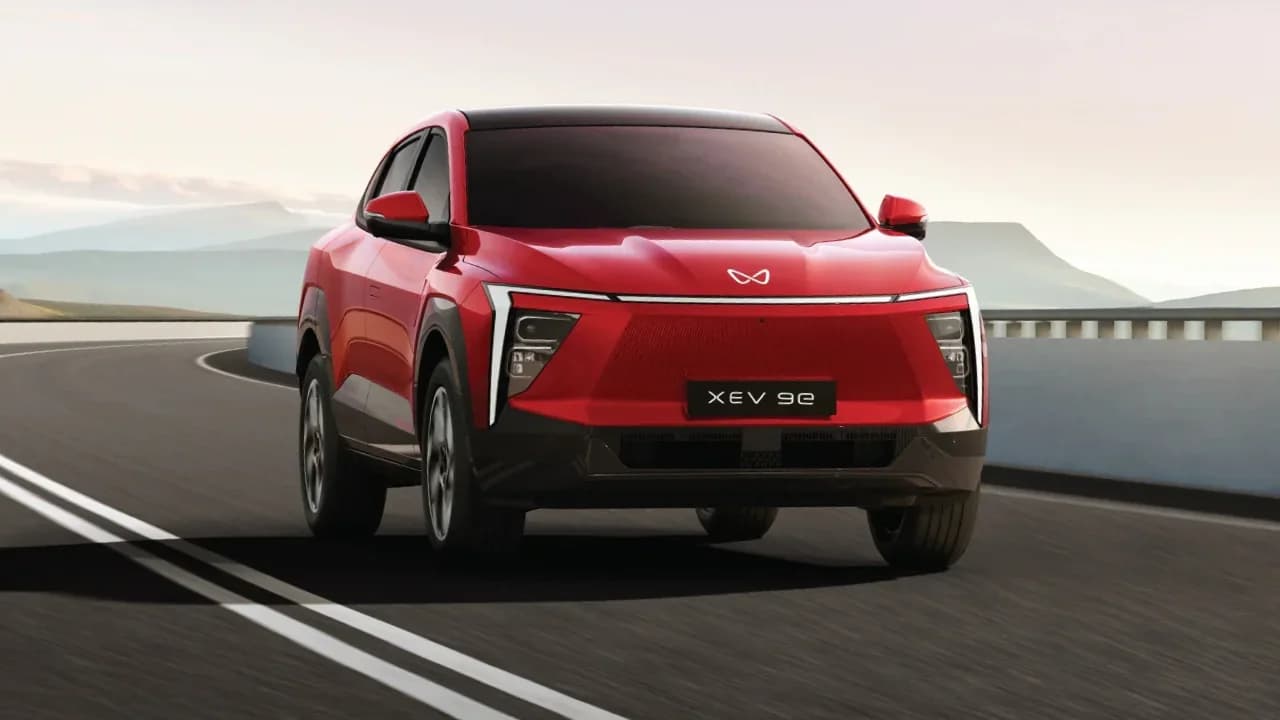
The SUV division remains the biggest growth trigger with demand significantly exceeding supply across key models such as Scorpio, Thar, XUV 7XO and the electric vehicle portfolio. M&M expects the segment to deliver mid-to-high-teen growth in FY27, supported by a strong order book, premiumisation and an expanding product portfolio. Electric vehicles are emerging as the next leg of growth, with EV penetration in M&M's SUV portfolio already surpassing the industry average, driven by strong response to the XEV range and the recent BE 6 Sporteq launch. M&M expects profitability in the EV business to steadily improve through localisation, scale benefits and operating leverage, while analysts see EVs becoming a meaningful contributor to earnings over the next few years.
The farm equipment segment faced significant headwinds during Q2FY27, with tractor volumes declining 6%, partly due to the festive calendar shift and weak rainfall in Maharashtra and Karnataka. Farm equipment revenue increased only 1% in Q2, remaining a drag on overall performance. The management consequently revised its FY27 domestic tractor industry growth outlook to flattish, from its earlier expectation of about 5% growth. According to The Economic Times, this implies an almost 10% decline in H2FY27 wholesales. The company's domestic tractor market share shrank 150 basis points year-on-year to 41.5% in Q2FY27. Segment margins declined 176 basis points quarter-on-quarter to 16.8%, reflecting weaker tractor volumes, commodity inflation and operating leverage. The revised outlook reflects weak monsoons, lower reservoir levels and drought-like conditions in key states.
M&M is expanding its monthly SUV/EV capacity from 64,500 units at the beginning of FY27 to 82,000 units by Q4FY27, with plans to expand to 92,000 units in FY28 and 132,000 units by FY31. The company's future pipeline also remains robust, with five launches scheduled before June 2027, including a new SUV on the NU_IQ platform, a new EV on INGLO platform, a Lifestyler vehicle, a major product refresh and a new light commercial vehicle. Beyond automobiles, businesses such as Mahindra Finance, Tech Mahindra, Last Mile Mobility, logistics and aerospace act as future growth drivers. The aerospace business is gaining scale with increasing global order wins and an ambition to achieve annual order inflows of around $1 billion by FY30, while financial services continue to benefit from improving asset quality.