Jefferies has maintained its Buy rating on JSW Infrastructure and raised its target price to ₹400 from ₹395, expecting a decade of double-digit growth. The brokerage sees port capacity expansion, a sharp rise in logistics earnings, and higher utilisation at new ports and terminals driving the company's growth through FY30 and beyond. Jefferies expects EBITDA to grow at over 30% annually between FY26 and FY30, with growth remaining above 15% annually beyond FY30. The positive outlook comes against the backdrop of improving activity across the ports and logistics sector.
According to reports from Jefferies, the brokerage has retained a positive view on the ports and logistics sector following strong industry performance. Overall port volumes increased 6% year-on-year during September, aided by robust activity at major ports. India's EXIM trade grew 13% from a year ago, driven by higher container traffic, coal shipments, petroleum, oil and lubricants (POL) cargo, as well as gems and jewellery exports. Container volumes continued to outperform rail volumes, supported by resilient transshipment traffic. However, non-major port volumes declined during the same period, indicating that growth was primarily concentrated in major port operations. The positive momentum is further supported by freight rates rebounding amid Middle East tensions and shipping disruptions.
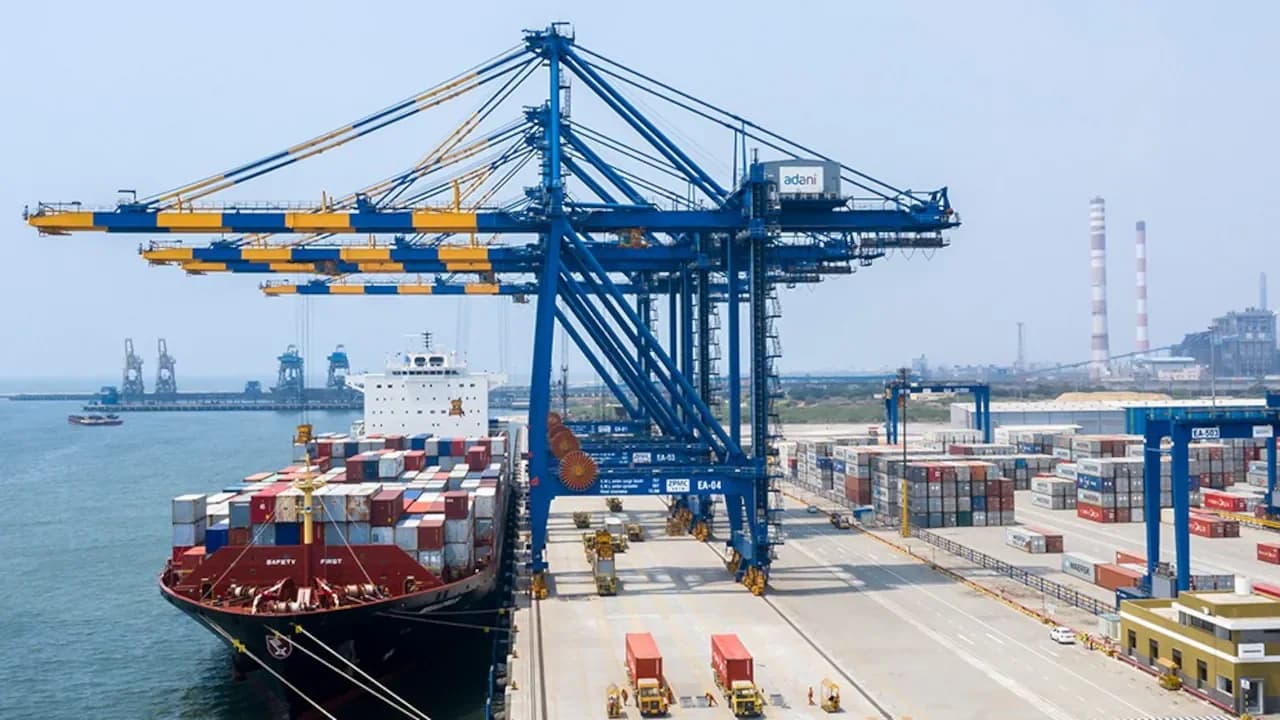
JSW Infrastructure has outlined ambitious expansion plans targeting 2.2x rise in port capacity and 14x rise in logistics EBITDA by FY30E, driving over 30% FY26-30E EBITDA CAGR for the company. The brokerage estimates 18% FY26-30E CAGR in volumes for JSWI, driven by 22% CAGR in JSW group cargo, primarily from JSW Steel (JSTL). JSTL targets 2.1x rise in its domestic capacity to 78 mt by FY32E, including 46% addition over FY30E-32E, where plans are evolving. Each tonne of steel requires 2.5-3 tonnes of raw material, which is expected to be handled by JSWI. The brokerage believes JSTL's expansion plans, coupled with potential in-sourcing of volumes by JSW group through JSWI, could add about 70 mt, representing around 30% addition to their FY30E volume forecasts.
Jefferies also sees the government's port privatisation plans as an opportunity for JSW Infrastructure to expand its presence. New terminals and higher utilisation could add to growth as the company increases capacity. The brokerage's positive view rests on both the sector's improving activity and the company's longer-term expansion plans. With port capacity and logistics earnings targeted to rise sharply by FY30, Jefferies expects JSW Infrastructure to sustain strong earnings growth over the next decade.
Among its sector preferences, Jefferies continues to favour Adani Ports and Special Economic Zone and JSW Infrastructure, citing their strong volume growth prospects and operational efficiencies. The brokerage is also constructive on Container Corporation of India (Concor), which it sees benefiting from enhanced connectivity between the Dedicated Freight Corridor and Jawaharlal Nehru Port, a development that could support long-term growth in container rail traffic. JSW Infrastructure has a target price of ₹400 based on 18x Sep'28E EV/EBITDA versus 16x for Adani Ports, to reflect JSWI's 25% FY28E-30E EBITDA CAGR versus 16% for Adani Ports.