The Reserve Bank of India's State of the Economy report warns that deficient rainfall could significantly affect the country's growth-inflation outlook, as the India Meteorological Department (IMD) projects south-west monsoon rainfall to be below normal this year. The latest data shows the rainfall deficit widening to 42.2% as of June 21 from 28.4% as of June 14, with the report stating that "an adverse south-west monsoon, if materialised, may weigh on the domestic growth-inflation outlook." The RBI's warning comes as the central bank maintains its current policy rate of 5.25% amid evolving economic conditions, with experts noting that easing crude oil prices and lower energy-related risks continue to support the current monetary policy stance. S&P Global has now projected India's economic growth to fall 110 basis points in fiscal year 2027, with real GDP growth estimated at 6.6% for fiscal year 2027, down from 7.7% in fiscal year 2026, citing energy-related pressures, expectations of a below-normal monsoon and slowing global economic growth.
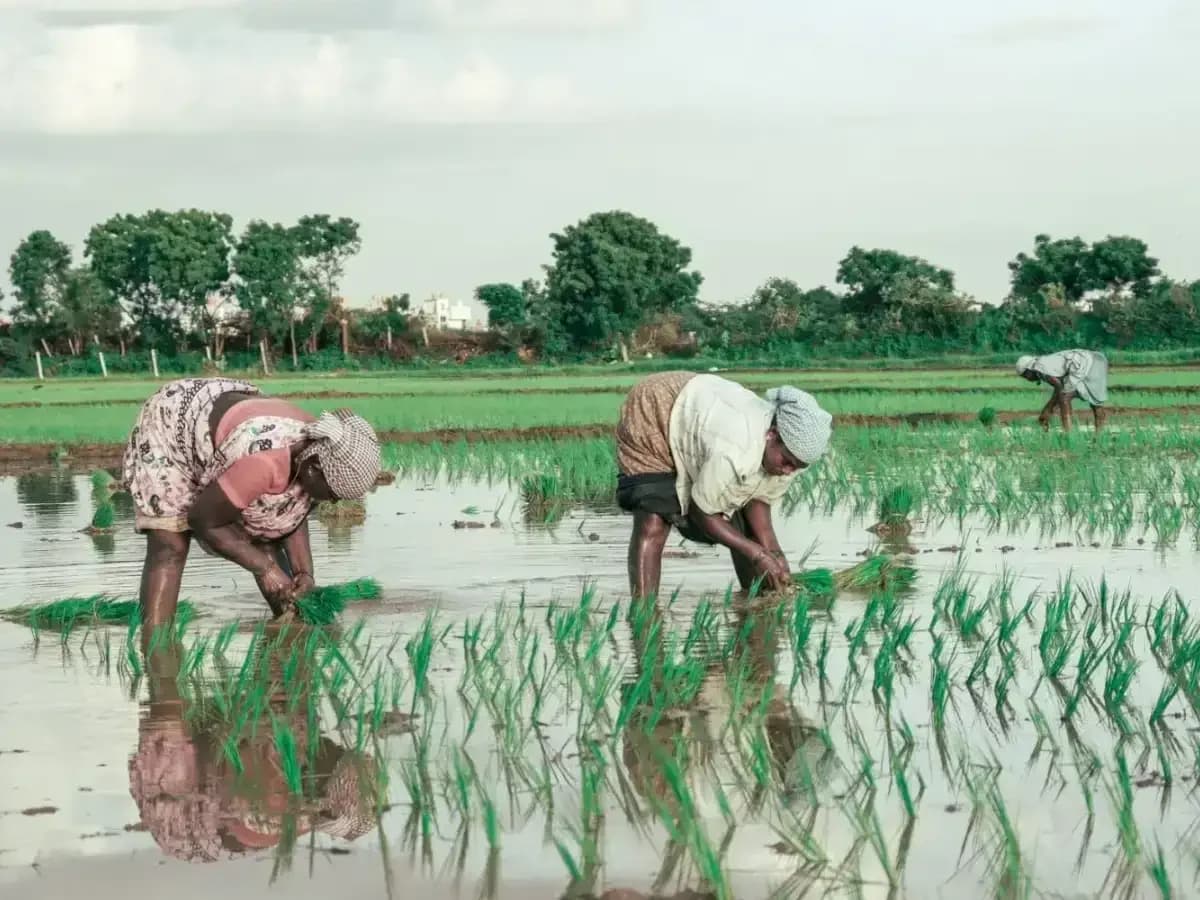
A recent QuantEco Research report projects India's gross value added (GVA) for agriculture and allied activities could slip to 0-1% in FY27, down from 3%, as an El Niño-induced deficient monsoon poses significant upside risks to food inflation. The report reveals that historically, agri GVA and monsoon deviation show a strong correlation of nearly 60%, meaning for every 1% shortfall in monsoon, around 40 basis points of agri GVA growth is sacrificed. However, agri-allied sectors, whose share has steadily risen from around 30% in 1990 to 40% in FY25, could possibly cushion the downside, with overall agri GVA in FY27 potentially remaining marginally positive. The most vulnerable crops include pulses, coarse cereals, oilseeds and cotton, with Maharashtra, Rajasthan, Karnataka, Jharkhand and Chhattisgarh being the most vulnerable states due to their low irrigated area coverage.
The RBI has revised upwards inflation outlook to 5.1% for the current fiscal, with CPI inflation for 2026-27 projected at 5.1%, representing a 300-basis point increase over the very benign rate of 2.1% for 2025-26. S&P Global has raised its inflation outlook for India, forecasting consumer price inflation at 5.1% in fiscal year 2027 compared with its earlier estimate of 4.9%. CPI inflation increased to 3.9% in May 2026 from 3.5% in the previous month, driven by broad-based increases across food, fuel and core components, as noted in the latest RBI report. Q3 inflation printed in at a high 5.9%, which is close to the upper tolerance level of 6%, with the peak of 5.9% in Q3 (October-December) may suggest the need for monetary policy action. S&P Global expects manufacturers to pass on higher energy costs to consumers, while recent increases in administered fuel prices, including petrol, diesel and cooking gas, are also likely to add to inflationary pressures.
The QuantEco Research report reveals that the inflationary impact of rainfall deficiencies is materially larger than the disinflationary benefit of rainfall surpluses, with every additional 1% shortfall in rainfall associated with an increase of roughly 25 basis points in food inflation. Conversely, in years of above-normal rainfall, every 1% improvement in rainfall reduces food inflation by only around 15 basis points. This asymmetry reflects the underlying demand-supply dynamics of food commodities, where demand for most food commodities is relatively inelastic, implying that consumption adjusts only marginally to changes in prices. The report notes that when deficient rainfall curtails agricultural output, the resulting supply shortfall is absorbed primarily through higher prices rather than lower consumption, with even modest production losses generating disproportionately large increases in food inflation. For 2026, a 10% rainfall shortfall can add at least 250-300 basis points to food inflation, translating into an incremental 100 basis points increase in FY27 headline CPI inflation.
The RBI has implemented some recent policy measures, including the expansion of the Fully Accessible Route (FAR) to longer-tenor government securities and tax exemptions for foreign investors in government securities, which are expected to strengthen demand for Indian sovereign debt and support capital inflows. FDI inflows gained strength, while foreign portfolio investment (FPI) recorded net outflows since March 2026. The report highlights that India's external sector continues to exhibit resilience in terms of a contained current account deficit and foreign exchange reserve buffers. On the liquidity situation, the report observed that surplus liquidity conditions moderated in May amid a continued rise in currency in circulation, the Reserve Bank's forex operations and a build-up of government cash balances, with the situation expected to ease going ahead as the drawdown of government cash balances is expected to augment system liquidity following the RBI's surplus transfer to the government. Given the expected rise in inflation, S&P Global believes the RBI will begin raising the repo rate from October, marking the start of monetary policy tightening in the second half of the financial year.