Sign in to fuzzto save your conversations, follow your research and come back anytime.

In the news
India's Green Hydrogen Race: Three Very Different Bets
3 Indian firms target ₹22L cr green hydrogen boom
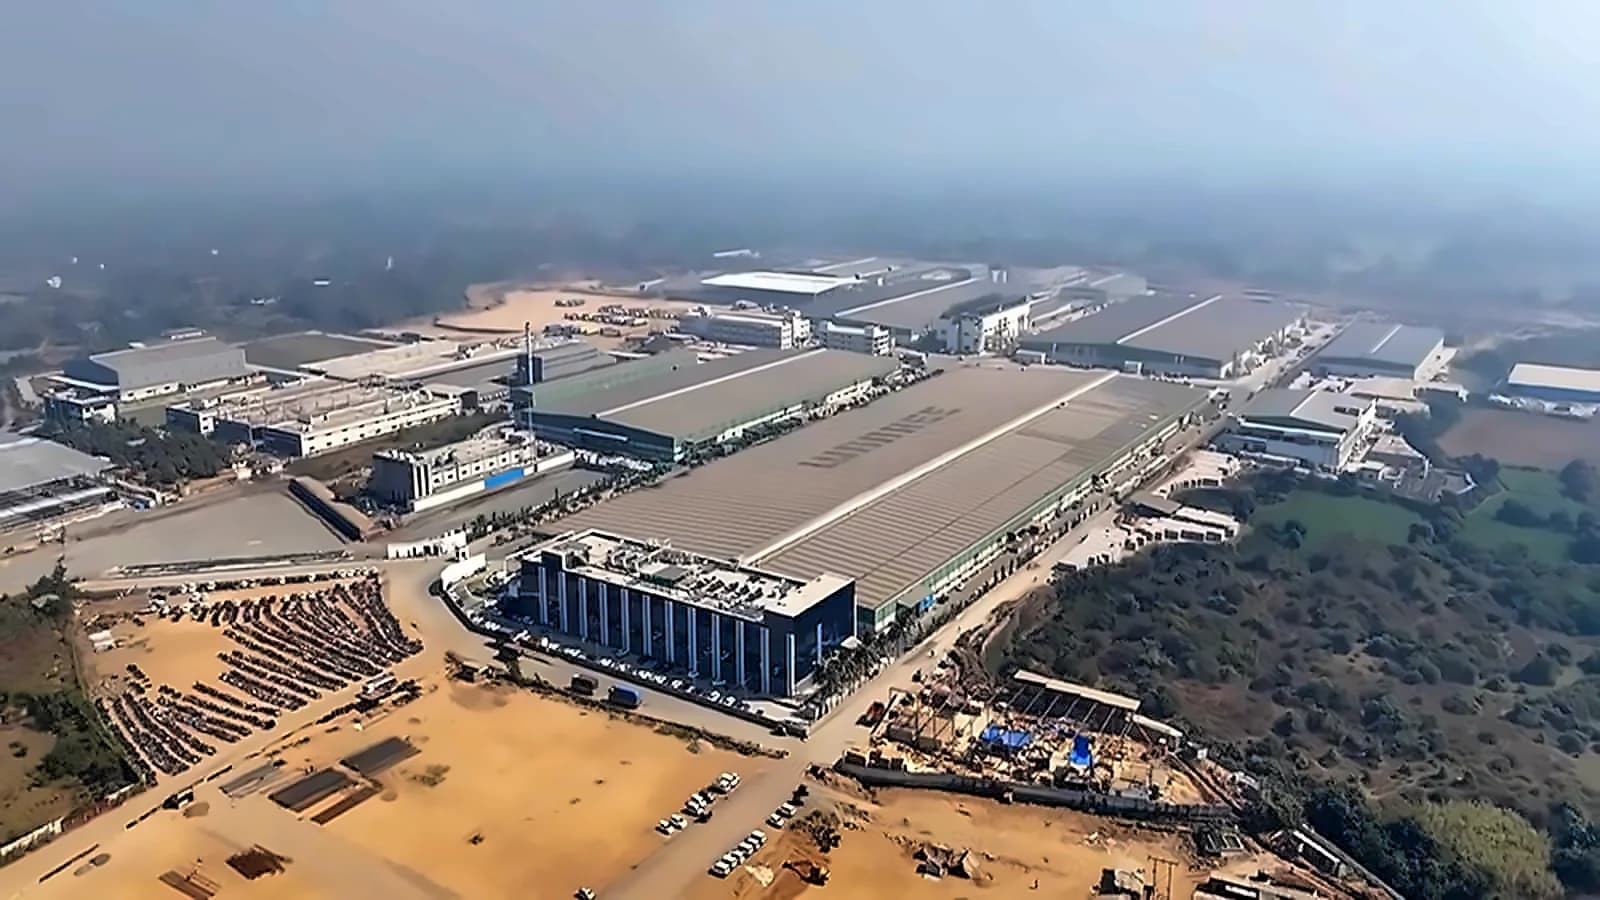
Waaree Energies starts 1.10 GW solar inverter production
India's renewable boom needs ₹4 lakh crore battery storage by FY32
Waaree-Indosolar Merger: The Hidden Logic Behind Solar Consolidation

Waaree Energies expands with new subsidiaries and solar orders
Waaree Energies shares gain 2% on 2 GW solar module order win
US Finalizes 249% Duties on Indian Solar Imports; Stocks in Focus
India's Industrial Revolution: The $100B Tech Empire
Coal India, ONGC turn ex-date Sept 4: ₹229 dividend payout amid market decline
Solar stocks decline 12-9% in past month amid mixed Q1 results
Waaree Energies Q1FY27 revenue surges 79%, order book hits record ₹61,500 crores

Waaree Energies shares rise 2.18% to ₹2,682 on strong growth
Waaree Energies Q1 FY27: Revenue Surge, Margin Pressure, and Growth Strategy
Swiggy Gets Mixed Buy Ratings; Targets ₹350-₹520
Solar Cell Mandate Deferral: What It Means for Manufacturers and Developers

Waaree ESS commissions 5.15 GWh battery storage facility

Waaree Energies shares up 0.17% on fresh 212 MW solar order win
6 Companies Target 155 GWh Energy Storage by 2030
Green energy stocks mixed on July 13 amid AI rotation and oil surge
The Quarter story
The two most recent quarterly results, compared side-by-side.
Waaree Energies drives strong revenue growth and a robust order book, though heavy capital spending and cost pressures are squeezing profit margins.
Revenue grew from ₹4,597 Cr in Q1 FY26 to ₹7,932 Cr in Q1 FY27, showing strong top-line momentum.
EBITDA margin slipped from 25.4% in Q1 FY26 to 18.2% in Q1 FY27, reflecting pricing and cost pressures.
Order book expanded from ₹24 Cr in Q2 FY26 to ₹61,500 Cr in Q1 FY27, ensuring clear revenue visibility.
PAT margin contracted from 16.8% in Q1 FY26 to 11.0% in Q1 FY27, highlighting margin erosion.
Module capacity increased from 18.7 GW in Q2 FY26 to 26 GW in Q1 FY27, confirming manufacturing scale-up.
Depreciation expense climbed from ₹182 Cr in Q1 FY26 to ₹330 Cr in Q1 FY27, weighing on profits due to heavy asset growth.
Retail revenue share rose from 18.6% in Q3 FY26 to 30.2% in Q1 FY27, highlighting successful channel diversification.
ROCE declined from 41.8% in Q2 FY26 to 28.5% in Q1 FY27, showing the impact of capital-intensive expansion.
Inventory changes improved from -₹760 Cr in Q1 FY26 to +₹97 Cr in Q1 FY27, signaling destocking completion.
Material costs rose from ₹2,962 Cr in Q1 FY26 to ₹4,844 Cr in Q1 FY27, adding pressure on operating margins.
Company insights, generated from the most recent coverage.
Waaree's 1 GW electrolyser ambition towers over its ₹152 Cr India order book (including a 2.5 MW contract) — capacity is being built years ahead of confirmed demand.
Board authorisation to raise up to ~₹10,000 Cr is the real swing factor — deploying it would dilute the net-cash balance sheet that currently lets Waaree outspend levered peers.
Capex is self-funding on paper: ~₹7,000 Cr cash at 30 June, ~30% already spent, and FY27 EBITDA guidance of ₹7,000–7,700 Cr covers most of the remaining ~₹22,000 Cr over three years.