Sign in to fuzzto save your conversations, follow your research and come back anytime.

The Quarter story
The two most recent quarterly results, compared side-by-side.
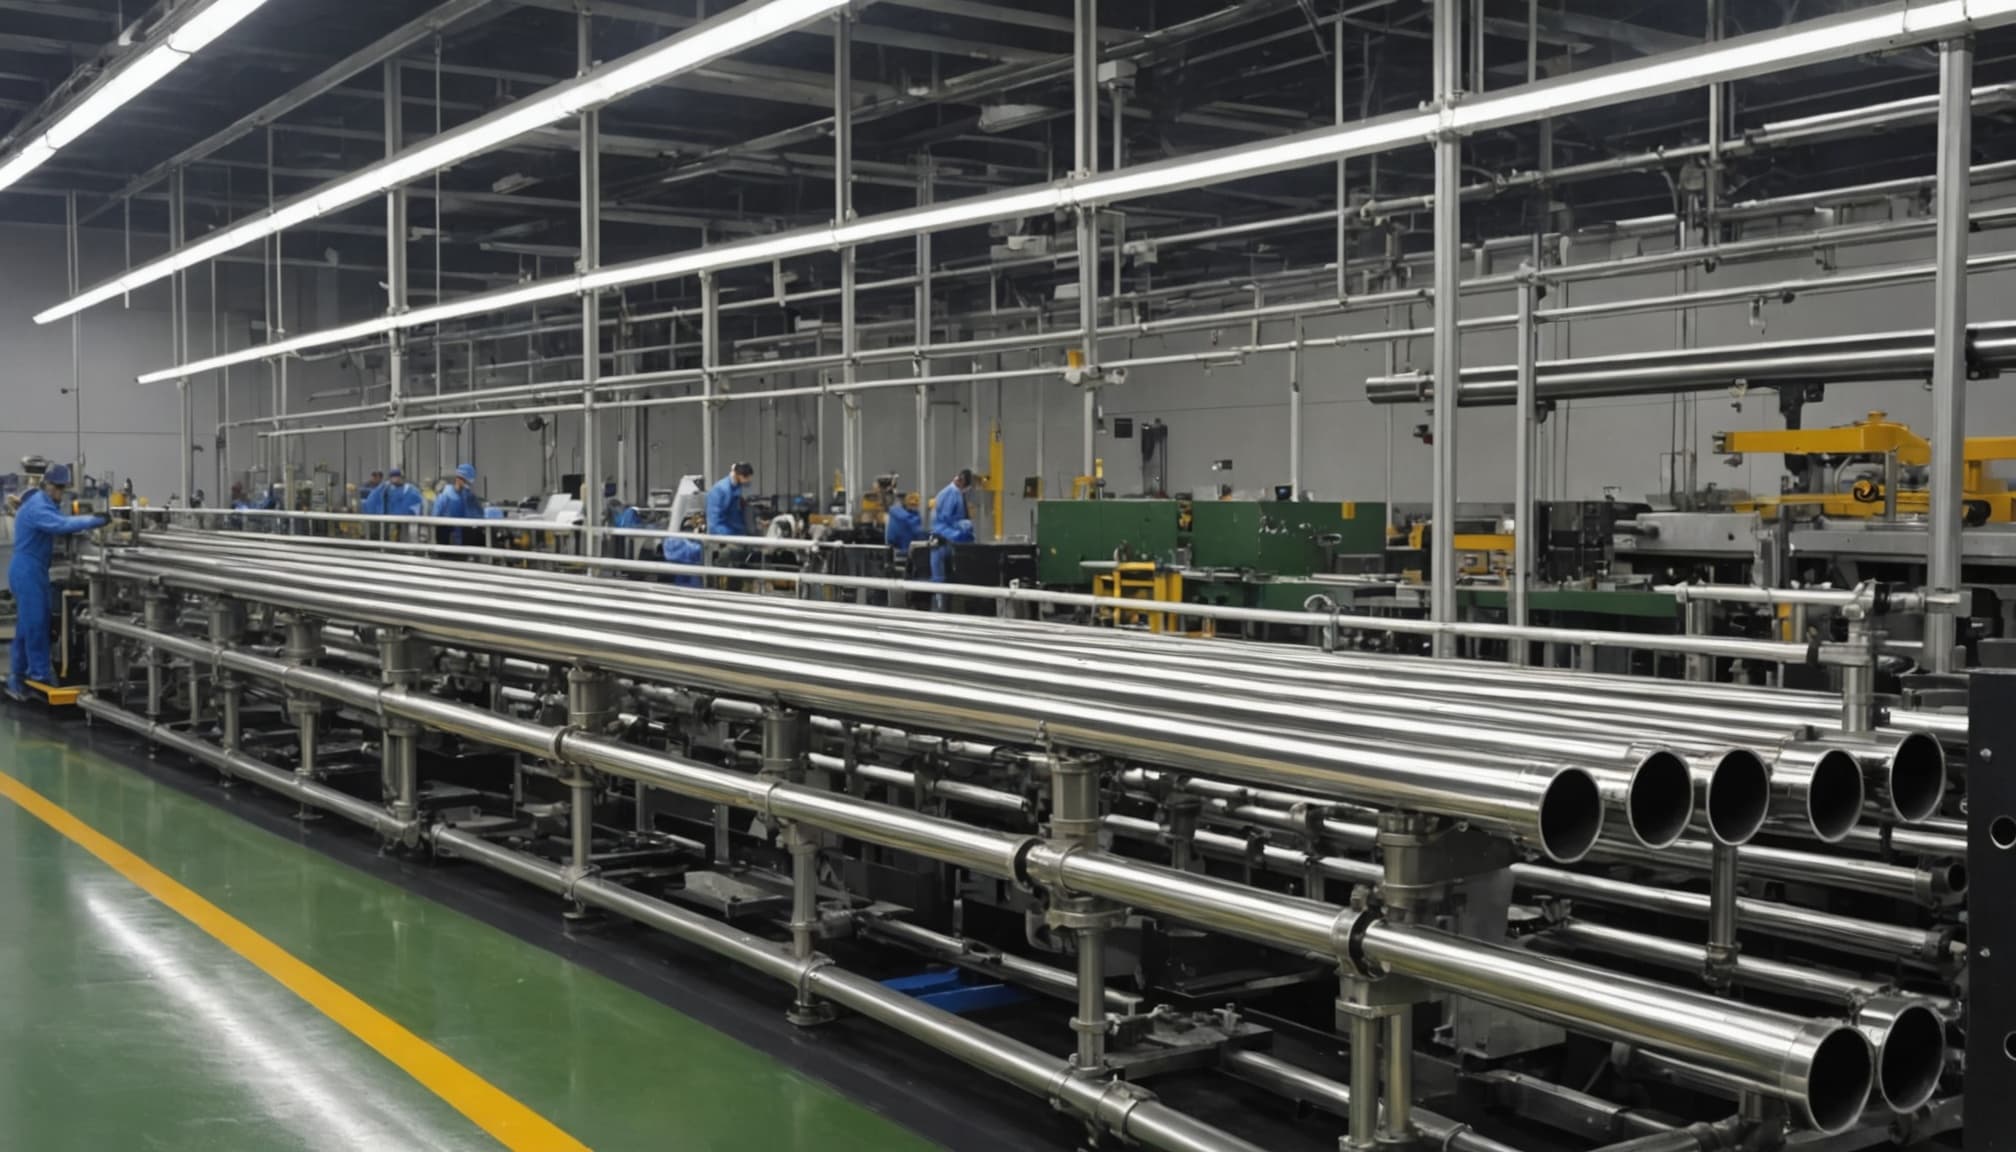
Venus Pipes & Tubes drives top-line growth through strong domestic and welded pipe demand, though rising input and operational costs are compressing net margins.
Revenue grew from ₹276.4 Cr to ₹320.5 Cr from Q1 FY26 to Q1 FY27 — strong demand across product lines
Cost of Goods Sold rose from ₹185.6 Cr to ₹207.7 Cr over five quarters — higher raw material and production costs are squeezing margins
Welded Pipes revenue surged from ₹103.6 Cr to ₹125.3 Cr over five quarters — segment momentum is driving top-line growth
PAT margin slipped from 9.0% to 8.2% from Q1 FY26 to Q1 FY27 — rising operational and employee costs are weighing on net profitability
Domestic sales share expanded from 63% to 71% from Q1 FY26 to Q1 FY27 — company is relying more on the stable local market
Export revenue fell from ₹103.1 Cr to ₹93.7 Cr over the period — overseas demand remains volatile and less predictable
Gross profit climbed from ₹90.8 Cr to ₹112.8 Cr over the period — pricing power is offsetting rising input costs
Other expenses jumped from ₹34.2 Cr to ₹45.6 Cr from Q1 FY26 to Q1 FY27 — administrative and overhead spending is outpacing revenue growth
EBITDA increased from ₹44.9 Cr to ₹51.5 Cr from Q1 FY26 to Q1 FY27 — core operating earnings remain resilient
Finance cost increased from ₹9.8 Cr to ₹11.3 Cr over five quarters — higher borrowing levels are adding to interest burdens
Company insights, generated from the most recent coverage.
Initial working capital requirements will rise due to accelerated capex and inventory buildup, but management expects borrowing needs to decline as EBITDA margins expand to 18-19%, improving cash conversion.
Spooling facility acts as a demand driver for internal components, targeting to lift welded pipe utilization from ~60% to >65% and fittings capacity utilization, enhancing overall asset turnover.
Scaling spooling revenue from 5% (FY27) to 10-15% (FY28) faces execution risks due to customer-specific approval processes taking 'a few months' each and compressed ramp-up timelines post-Q3 FY27 commissioning.