Sign in to fuzzto save your conversations, follow your research and come back anytime.

SBI Cards and Payment Services Limited is an Indian company that issues credit cards and acts as a corporate insurance agent. Incorporated in 1998 and a subsidiary of State Bank of India, it is the second-largest credit card issuer in India with over 16.8 million cards in force. The company offers a diverse portfolio of credit cards, including SBI Card-branded and co-branded cards, catering to various customer segments. It partners with Visa, MasterCard, and RuPay payment networks. SBI Cards has a wide customer acquisition network, including physical points of sale, digital platforms, and access to SBI's extensive branch network. The company has launched several new card products and partnerships across different categories to expand its offerings and reach.
In the news
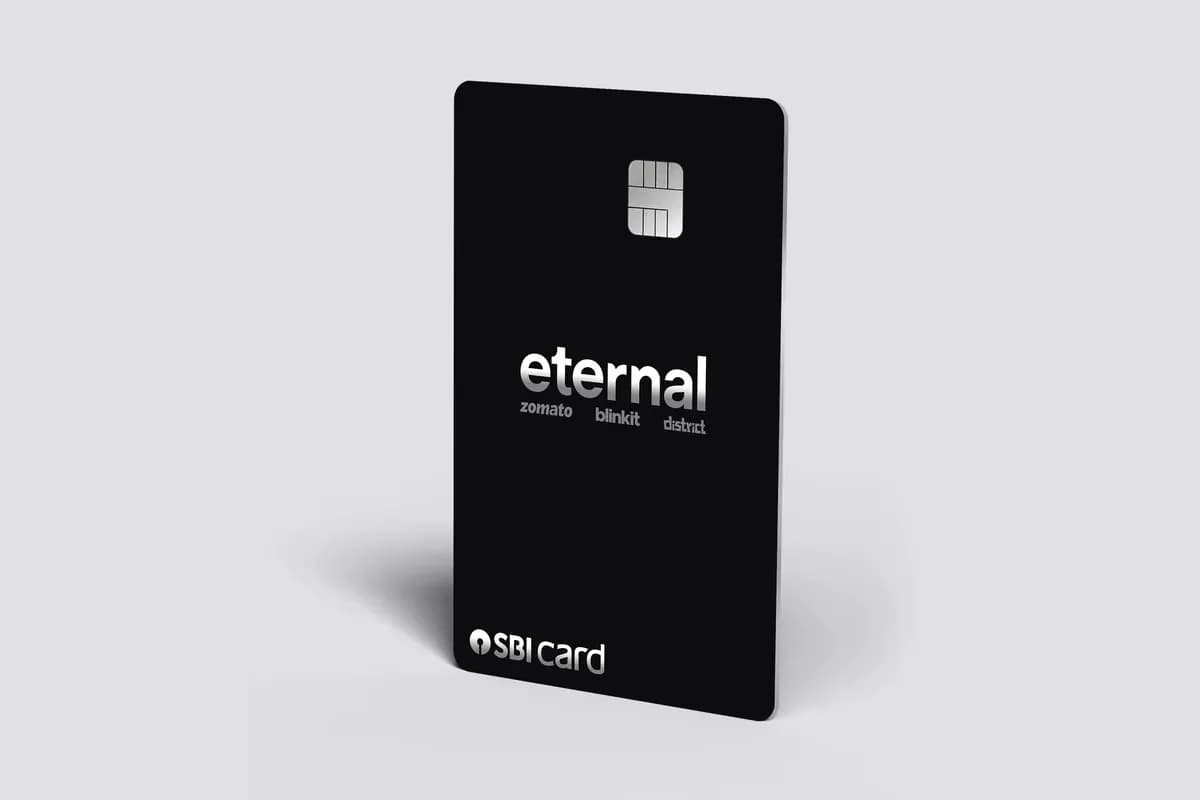
SBI Card, Eternal launch co-branded credit card with discounts
SBI Card launches fixed deposit backed Advantage SBI Card on YONO
India's Credit Card Profitability Crisis: The Revolver Revolution
SBI Card offers travel benefits for international trips
Credit card spends slip 2.4% YoY in July 2026 despite record issuances
SBI Card faces 34% downside risk as Bernstein cuts target
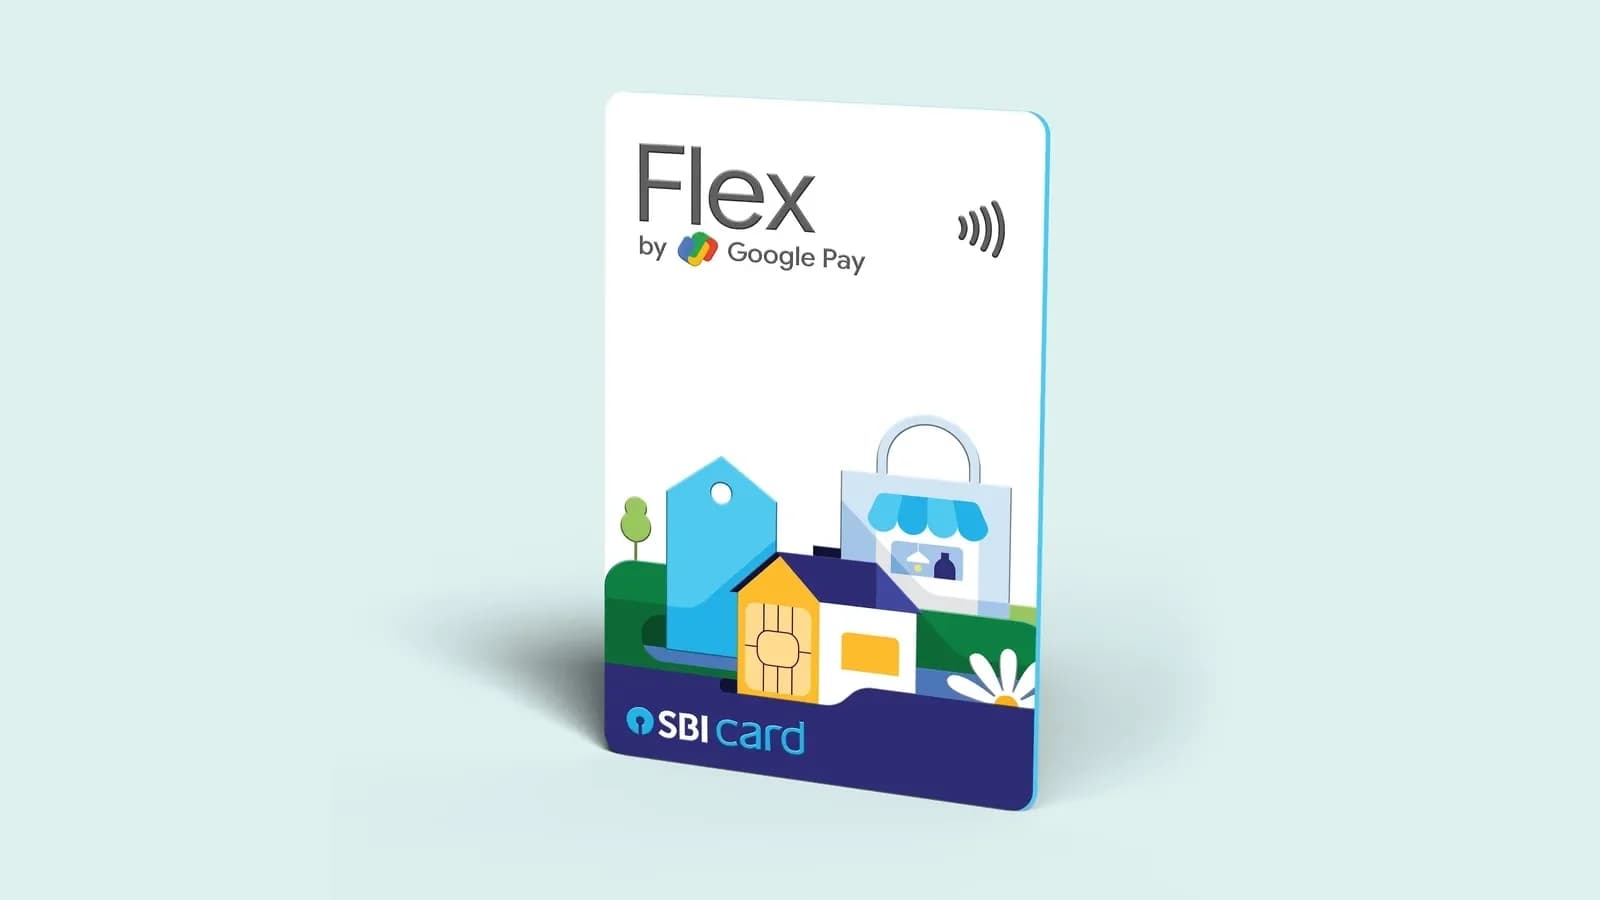
Google Pay launches second co-branded credit card with SBI Card
SBI Cards gets Neutral rating, target Rs 700: Motilal Oswal
SBI Cards Q1 FY27: Profit Growth Amid Strategic Shifts
SBI Card Q1 profit jumps 20% YoY to ₹664 crore, stock rises 4%
SBI Cards Q1 profit jumps 20% to ₹664.4 cr on lower provisions
SBI Cards Q1 Results Today: Key Metrics to Watch
Kotak Securities picks 3 stocks for short-term gains
5 Stocks to Buy: SBI Cards, JSW Energy, Fortis Healthcare
10 Financial Rule Changes Take Effect From July 1, 2026
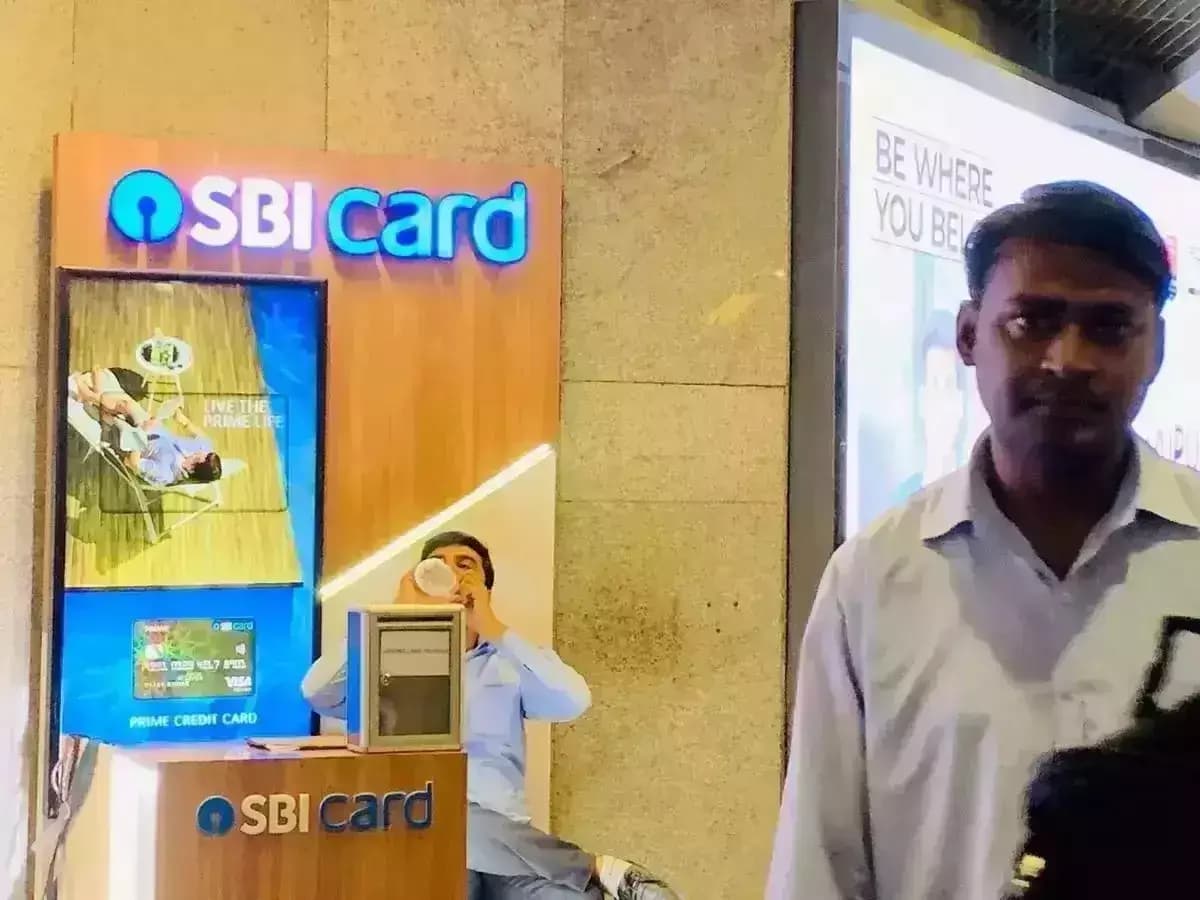
SBI Cards Leads May Card Additions as India Crosses 120M Milestone
74% of fraud cases linked to cards, Internet: RBI report
SBI Card Q4FY26: Asset quality improves, growth remains subdued
SBI Cards shares hit ₹623.8, credit card spends cross ₹23.62 trillion

NALCO Hold Rating, ₹395 Target: ICICI Securities
The Quarter story
The two most recent quarterly results, compared side-by-side.
SBI Cards drives strong spend growth and cleaner loan books, while rising operating costs and margin pressure test efficiency.
GNPA fell from 3.07% to 2.04% from Q1 FY26 to Q1 FY27 — steadily improving loan quality
Cost to Income Ratio rose from 50.3% to 58.7% from Q1 FY26 to Q1 FY27 — rising operational inefficiency
Total spends grew from ₹93,244 Cr to ₹118,475 Cr from Q1 FY26 to Q1 FY27 — robust transaction volume expansion
Net Interest Margin slipped from 11.2% to 10.8% from Q1 FY26 to Q1 FY27 — compressing lending margins
CAR improved from 23.2% to 25.6% from Q1 FY26 to Q1 FY27 — strong capital buffer for future lending
Operating Costs increased from 13.0% to 15.4% from Q1 FY26 to Q1 FY27 — higher cost intensity relative to revenue
Fees and commission income rose from ₹2,191 Cr to ₹2,406 Cr from Q1 FY26 to Q1 FY27 — steady non-interest revenue growth
Yield on assets fell from 17.0% to 16.0% from Q1 FY26 to Q1 FY27 — lower returns on the loan book
Profit After Tax climbed from ₹556 Cr to ₹664 Cr from Q1 FY26 to Q1 FY27 — consistent bottom-line recovery
Market Share in Cards in Force dipped from 19.1% to 18.6% from Q1 FY26 to Q1 FY27 — stagnant position in card issuance
Company insights, generated from the most recent coverage.
SBI Card is absent from Apple Pay's launch over unresolved fees — costly for a pure-play card issuer that lacks an integrated bank's diversification to absorb Apple's margin take.
With 45% of receivables coming from transactors, SBI Cards is more exposed to the structural shift towards payment-focused card usage than peers with higher revolver mixes.
SBI Cards' pure-play business model lacks the diversification benefits of integrated banks, increasing its vulnerability to industry-wide credit card margin compression.